U.S. strategic Oil Reserves under Pressure

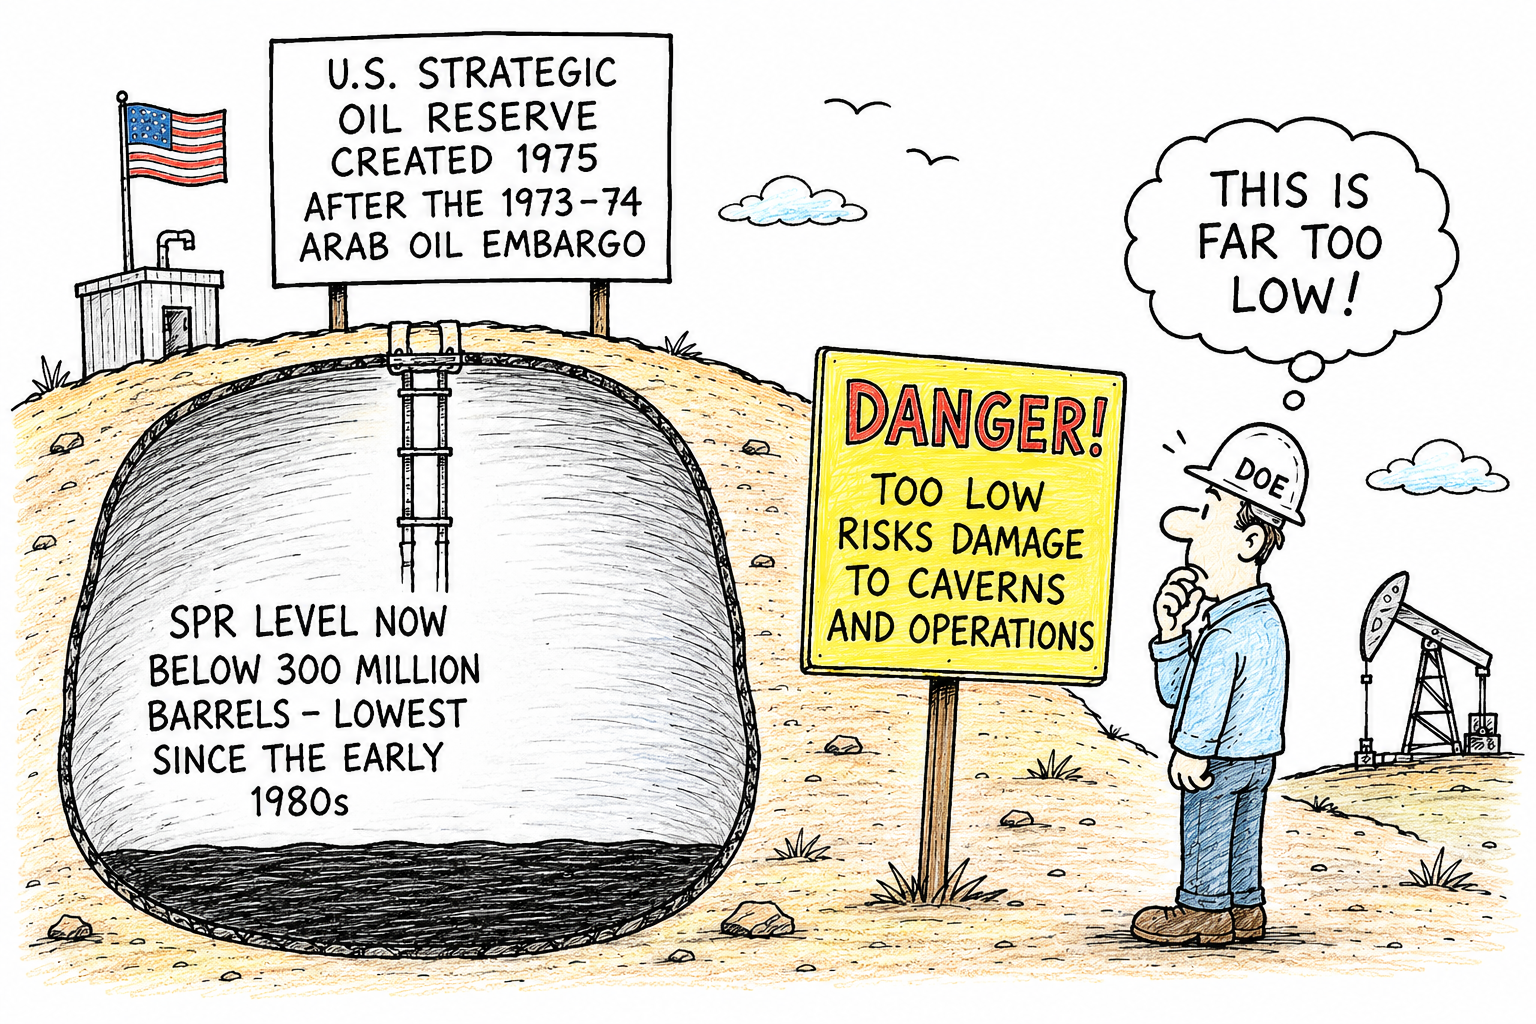
America’s Strategic Petroleum Reserve (SPR) was created in 1975, in the aftermath of the 1973–74 Arab oil embargo, when an oil supply shock exposed America’s vulnerability to disruptions in foreign energy supplies.

Its purpose was straightforward: provide the United States with an emergency stockpile of crude oil that could be released if supplies were suddenly threatened.

More than 50 years later, that safety net is looking increasingly fragile.

Depleted levels

The SPR has fallen to around, and now below, 300 million barrels — its lowest level since the early 1980s. The decline follows a succession of major releases, including the huge drawdown ordered in 2022 to help counter the surge in oil prices following Russia’s invasion of Ukraine.

The problem is not simply that America has less oil available during an emergency. The crude is stored deep underground in enormous salt caverns, and repeatedly removing and replacing large quantities of oil creates additional engineering and operational challenges.

Concerns have been raised that allowing inventories to fall too far could complicate the safe and efficient operation of some caverns.

Collapse

That does not mean the underground storage sites are on the verge of collapse. The SPR was specifically designed around the properties of salt formations, and the facilities are subject to extensive monitoring and maintenance.

But the reserve was never intended to be routinely used as a tool for managing ordinary fluctuations in oil prices.

Rebuilding it is also a slow process. Buying hundreds of millions of barrels requires money, suitable crude and sufficient time to inject it back into the caverns. The infrastructure itself must also remain operational.

That leaves Washington facing an uncomfortable dilemma. The SPR exists precisely to be used during an energy crisis.

But if it is drawn down too aggressively, America risks weakening the very emergency insurance policy created in 1975 to protect it.

The strategic question is no longer simply how much oil America has — but how much of its emergency reserve it can safely afford to use.
Is the AI Productivity Payoff Coming Any Time Soon?

The first phase of the artificial intelligence boom was largely about the companies building the technology. Nvidia, Microsoft, Amazon and other giants have poured billions into chips, data centres and cloud infrastructure, creating some of the biggest investment stories of recent years.

But the next phase could be rather different. The real financial payoff from AI may increasingly emerge inside ordinary businesses as companies discover that intelligent software can make their existing workforces significantly more productive.

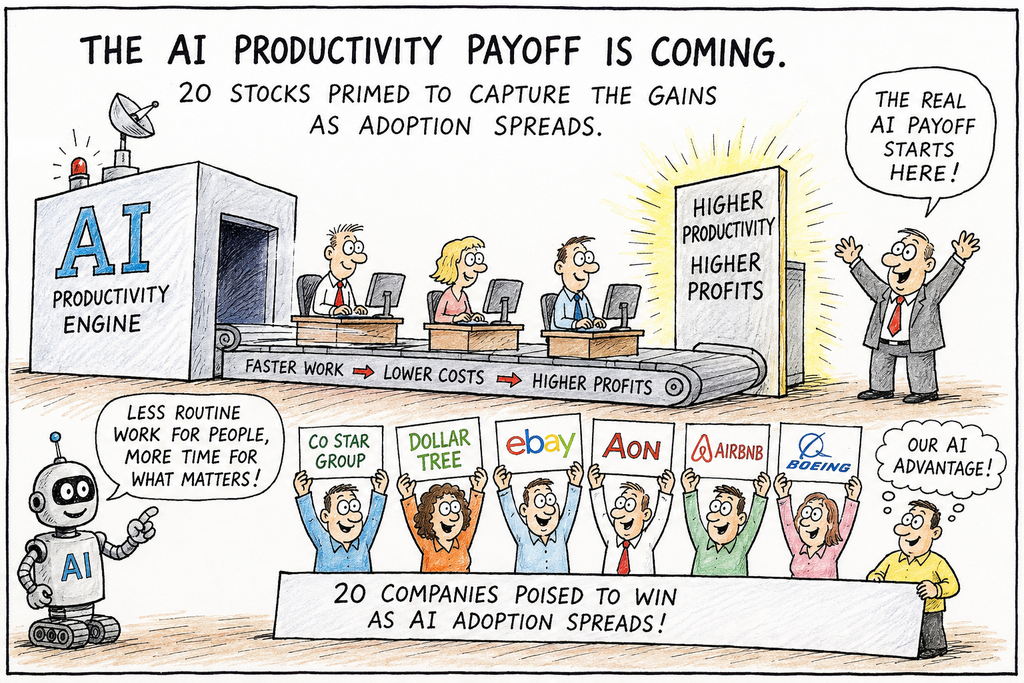
Goldman Sachs has reportedly identified 20 stocks it believes could be particularly well positioned to capture these gains as AI adoption spreads.

Big AI benefactors

The list includes CoStar Group, Dollar Tree, eBay, Arthur J. Gallagher, Brown & Brown, Axon Enterprise, Trade Desk, CMS Energy, Jacobs Solutions, Edison International, Aon, Marsh & McLennan, Kimberly-Clark, Willis Towers Watson, Airbnb, Iron Mountain, CBRE Group, RTX, Boeing and Expedia.

What makes the selection interesting is that most are not conventional AI companies. Goldman focused on businesses with substantial labour costs and significant exposure to occupations where AI could potentially automate or accelerate tasks.

Insurance

Insurance companies are particularly prominent. Aon, Marsh & McLennan, Arthur J. Gallagher, Brown & Brown and Willis Towers Watson employ thousands of people in areas involving analysis, administration, documentation and customer service.

AI could increasingly handle routine work, allowing employees to concentrate on more complex and valuable activities.

Travel, property and advertising businesses could also benefit through improved customer service, pricing, marketing and data analysis.

Productivity promise

However, the productivity revolution remains more promise than proven financial reality. Only a relatively small proportion of companies are currently quantifying AI’s direct contribution to earnings.

That could change rapidly. If businesses begin converting AI-driven efficiency into lower costs, higher margins and stronger profits, investors may start looking beyond the obvious AI winners.

The most important AI stocks of the next few years, therefore, may not necessarily be the companies selling the technology. They could be the companies quietly using it to do more with fewer resources.

The AI revolution may finally be moving from the data centre into the income statement.

America’s $40 Trillion Debt Problem

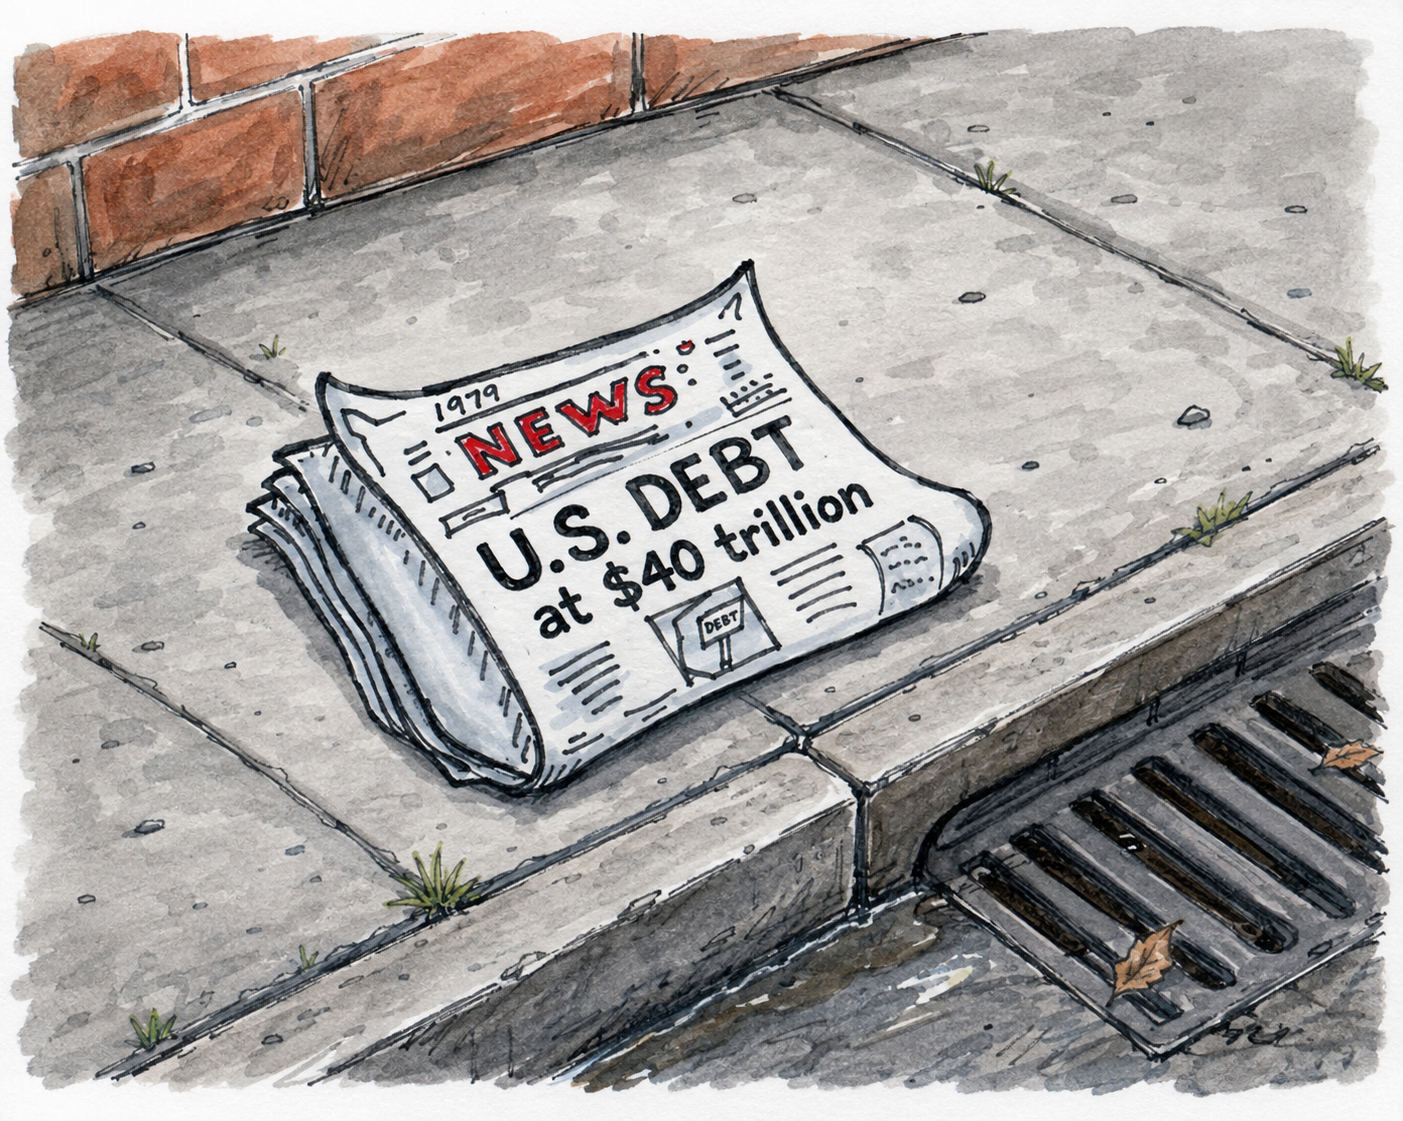
The United States has crossed a remarkable financial milestone, with federal debt now standing at more than $40 trillion.

The figure is difficult to comprehend, but the bigger concern is the speed at which the debt burden is continuing to grow.

Debt increased $3 Trillion in one year

America’s debt has increased by roughly $3 trillion over the past year alone. The federal government is still running substantial annual deficits, meaning it is spending considerably more than it collects in tax revenue.

As a result, more borrowing is required simply to keep government finances operating.

The consequences are becoming increasingly visible in the bond market. Investors expect to be compensated for lending money to the U.S. government, and rising Treasury yields mean that borrowing is becoming more expensive.

The yield on the 30-year Treasury has recently climbed above 5%, placing further pressure on government finances.

Interest at $1.2 Trillion per year

Interest payments are becoming one of Washington’s largest financial burdens, approaching $1.2 trillion a year.

That money does not build infrastructure, fund new programmes or reduce the deficit. It is largely the cost of servicing debt accumulated over many years.

The Treasury has also increased its bond-buying operations in an effort to improve market liquidity, highlighting concerns about conditions in the government bond market.

While such measures can help stabilise trading, they do not address the underlying problem: America continues to borrow heavily.

How high can it go?

The $40 trillion milestone therefore represents more than a headline figure. It raises difficult questions about how long the current trajectory can continue and whether politicians will eventually have to confront spending, taxation and entitlement reform.

For years, America’s ability to borrow has been treated as almost unlimited. But the combination of enormous debt, persistent deficits, rising interest costs and higher bond yields is changing that calculation.

The world’s largest economy is not facing an immediate debt crisis, but $40 trillion is a warning that the cost of delaying difficult decisions is becoming increasingly expensive.