Bank of England Raises Interest Rates to 4%

Graph showing the Bank of England's interest rate increase to 4% as of November 2026, with trends in previous rates indicated.

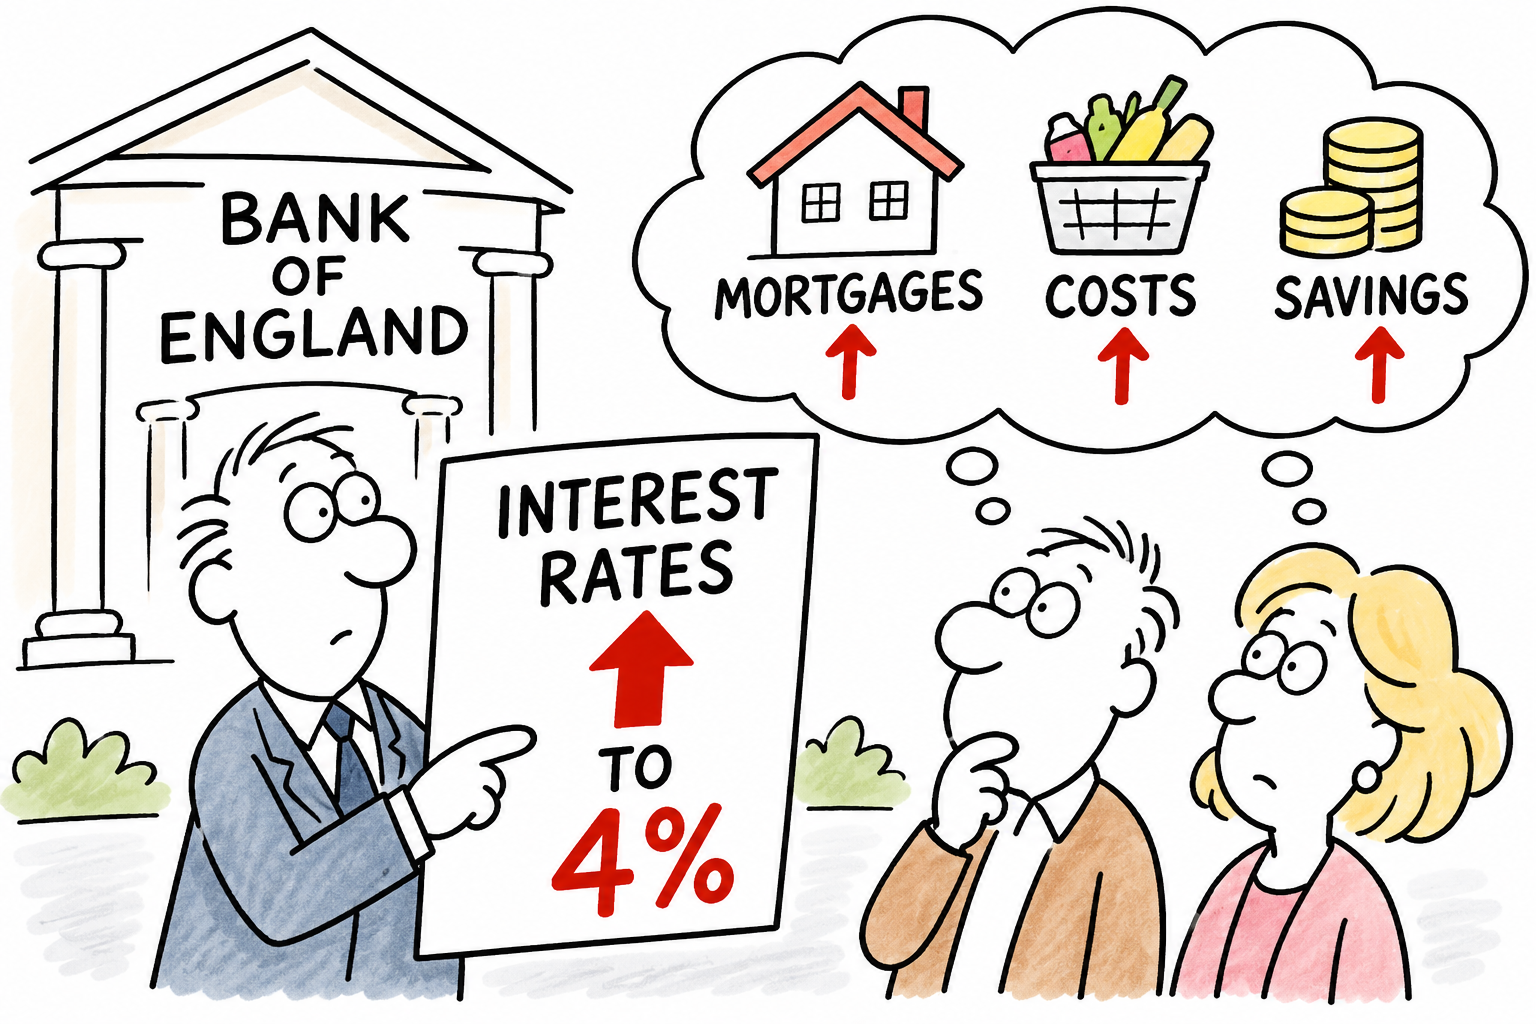
The Bank of England has raised interest rates for the first time in more than three years, increasing the base rate from 3.75% to 4% in a move aimed at tackling renewed inflationary pressures.

The decision, announced on Thursday 5th November 2026, followed growing concerns over rising energy prices, fuelled by the continuing conflict in the Middle East. and of the Russia-Ukraine war.

UK inflation reached 3.5% in September 2026, and the Bank now expects it could approach 5% by the middle of 2027.

Vote

The Monetary Policy Committee voted 8–1 in favour of a quarter-point increase, although one member wanted a larger rise to 4.25%.

Higher interest rates will increase borrowing costs for mortgage holders and businesses, while potentially offering better returns for savers.

The Bank has warned that further increases remain possible if energy prices continue to drive inflation higher.

The decision highlights the difficult balancing act facing policymakers: controlling inflation without damaging an already fragile economy.

AI Is Breaking Down the Barriers to Starting a Business

The power of AI empowering business start-ups

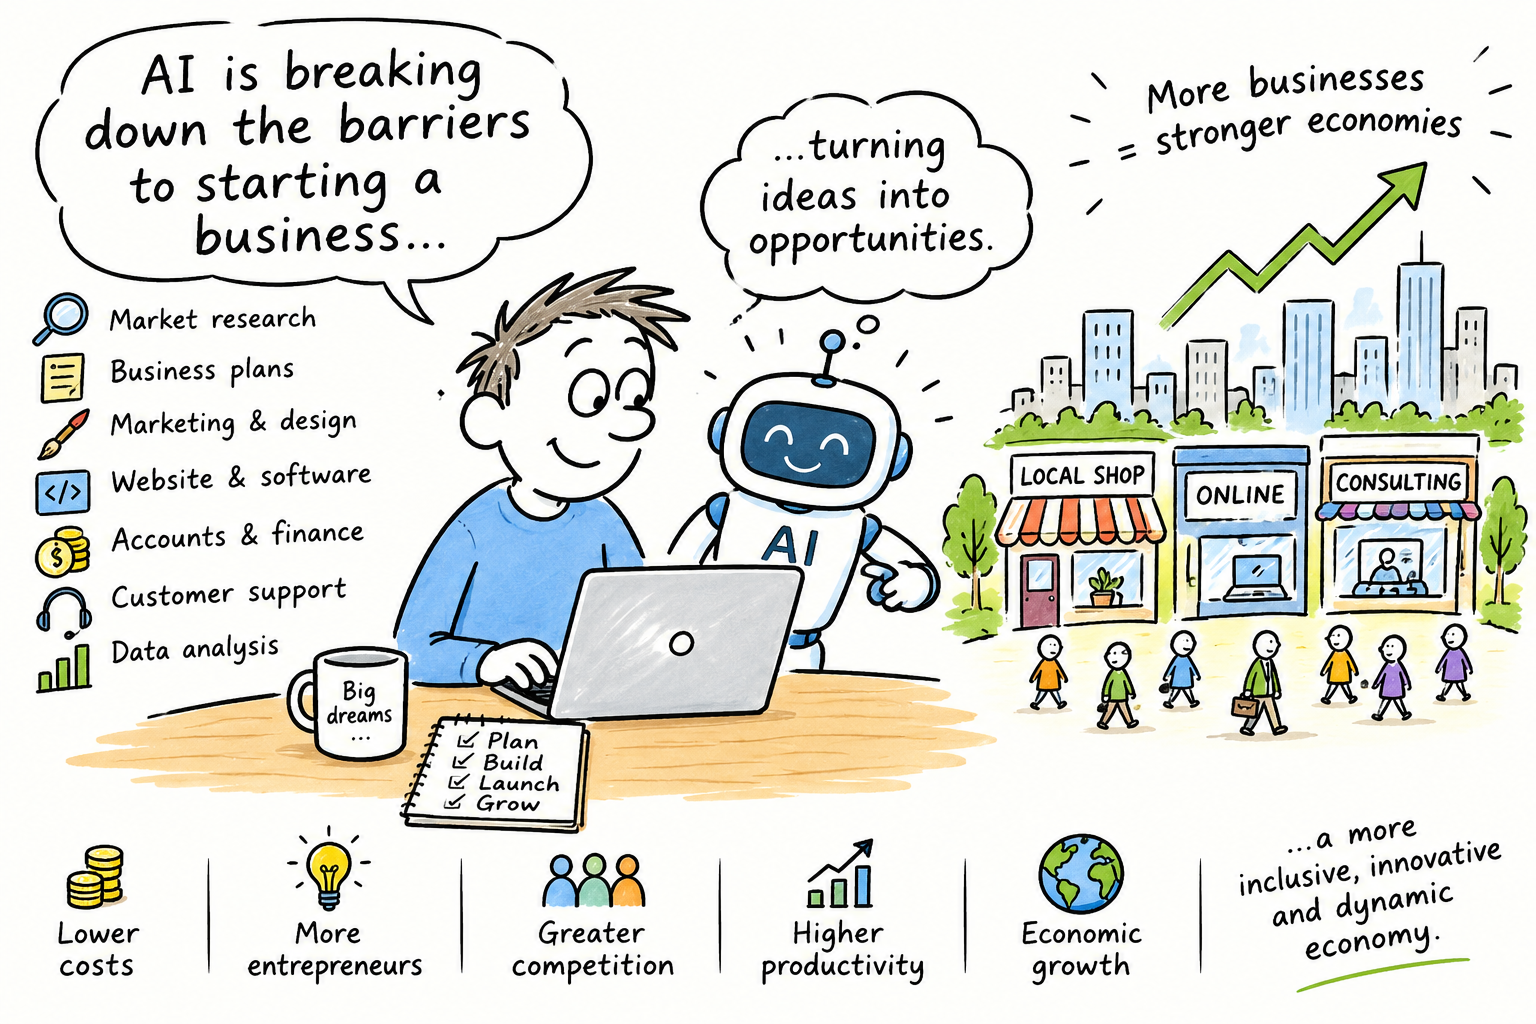
Artificial intelligence is beginning to reshape the economics of starting and running a business.

AI is easily accessible

What once required substantial financial investment, specialist skills and a team of employees can increasingly be achieved by an individual with a computer, an internet connection and access to AI tools.

The implications could extend well beyond entrepreneurship, potentially changing productivity, employment, competition and economic growth.

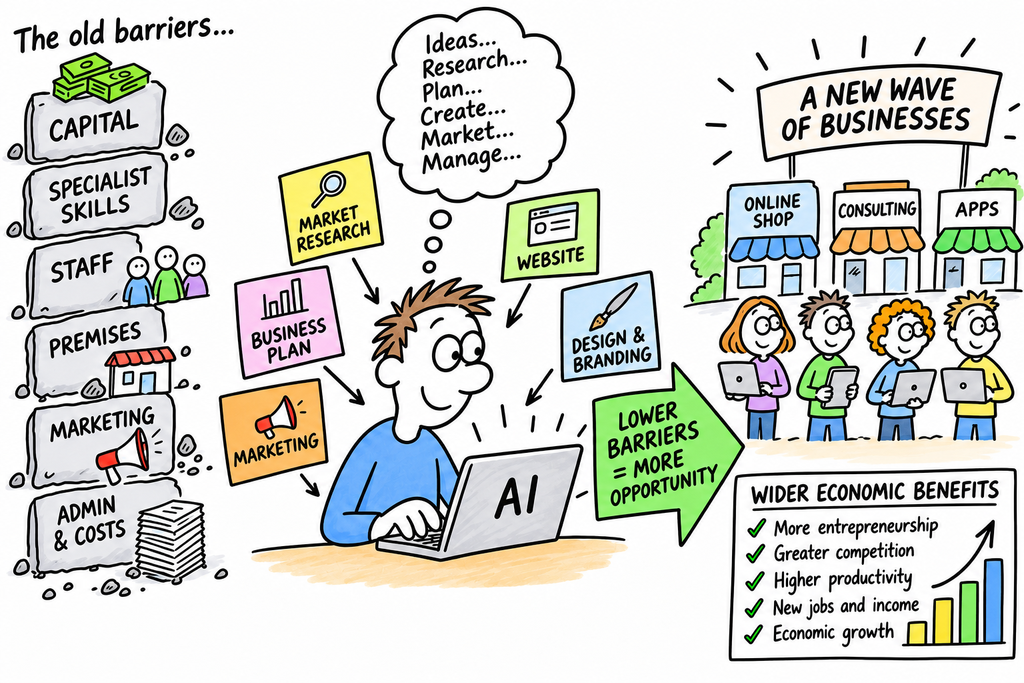
Traditionally, starting a business involved considerable upfront costs. Entrepreneurs needed to invest in staff, premises, marketing, professional services, technology and administration, often before generating their first pound of revenue.

These expenses created significant barriers to entry, particularly for individuals without access to capital or business connections.

AI is changing this economic equation

An individual can now use AI to conduct market research, develop business plans, build websites, write software, produce marketing campaigns, analyse financial information and manage customer enquiries.

Tasks that previously required several employees or expensive external consultants can increasingly be handled by one person at a fraction of the cost.

This has the potential to create a new generation of micro-businesses, independent entrepreneurs and highly productive one-person companies.

Lower operating costs could allow businesses to become profitable with considerably less revenue than was previously necessary.

For the many

The wider economic consequences could be significant. If millions of individuals can establish businesses with relatively little capital, entrepreneurship could become a much more accessible route to generating income and creating employment.

Smaller businesses may also become more competitive, challenging established corporations that have traditionally benefited from economies of scale, larger workforces and greater financial resources.

But first we will have a period of transition and discovery.

Productive

There is also a potentially important productivity dividend. Businesses able to produce more with fewer employees could reduce operating costs, improve margins and increase output.

At a national level, this could contribute to economic growth without requiring the same expansion in the workforce.

For governments struggling with ageing populations, labour shortages and weak productivity, AI could become an increasingly important economic tool.

Saturation

However, there is another side to the equation. As the cost of establishing a business falls, competition will intensify.

Markets could become saturated with similar products and services, while automation may displace certain administrative, creative and professional roles.

The economic benefits will depend partly on whether new businesses and industries create sufficient opportunities to offset employment lost elsewhere.

Access to AI will also matter. If the technology becomes concentrated among a small number of powerful companies, the savings generated by automation may not be distributed evenly.

Nevertheless, AI could represent a significant democratisation of business ownership. The traditional advantages of capital, staffing and infrastructure may become less important, while creativity, commercial judgement and the ability to identify opportunities become increasingly valuable.

The Next Wave

The next wave of business creation may not come from large corporations investing billions, but from individuals using AI to build businesses that previously would have been financially impossible.

AI is not eliminating the risks of entrepreneurship. It is, however, dramatically reducing the cost of trying. That could have profound implications for the future structure of the global economy.

AI: The Next Great Economic Boom – But at What Financial and Economic Cost?

The artificial intelligence revolution continues to dominate financial markets, attracting extraordinary investment from some of the world’s largest technology companies.

Yet beneath the enthusiasm, a growing number of economic, financial and political concerns are emerging. While technology shares have recently staged a recovery, the fundamental questions surrounding the sustainability of the AI investment boom remain unanswered.

The central issue is becoming increasingly difficult to ignore: can the commercial returns from artificial intelligence justify the enormous cost of building the infrastructure required to support it?

An unprecedented investment programme

Microsoft, Amazon, Alphabet, Meta, Oracle and many others are committing hundreds of billions of dollars to data centres, specialist processors and supporting infrastructure. Their ambitions are substantial, with AI expected to transform productivity, business operations, healthcare, manufacturing and countless other industries.

However, the scale of expenditure is creating growing financial pressures. The Bank of England has highlighted the increasing reliance on borrowing to finance AI infrastructure. Morgan Stanley reportedly estimated that global AI-related debt issuance had reached approximately $450 billion by early September 2026, more than double the total for the whole of 2025.

The Bank has also highlighted the growing involvement of private credit and more complicated financing arrangements. These developments raise questions about where the financial risks ultimately sit, particularly if expected commercial returns fail to materialise.

Debt itself is not necessarily a problem. Large companies routinely borrow to finance expansion. The concern is whether the investment will generate sufficient cash flow to service that borrowing while continuing to fund further development.

The returns question

Technology companies are investing on the assumption that AI adoption will eventually produce enormous commercial opportunities. However, the gap between infrastructure expenditure and demonstrable financial returns remains an important consideration.

Data centres are expensive to construct and operate. Specialist chips require continual investment, while electricity, cooling, water and network infrastructure add further costs.

The industry must also contend with rapidly changing technology. Today’s expensive processors and facilities could become less competitive as more efficient systems emerge.

There is also the possibility that investment is running ahead of commercial demand. Businesses are experimenting with AI, but widespread adoption does not automatically translate into sufficient revenue to justify the enormous infrastructure costs.

Investors will increasingly want evidence that AI-related revenues and productivity improvements are keeping pace with capital expenditure.

Chinese competition adds another complication

Competition from China represents another potential challenge.

Chinese developers have demonstrated that increasingly capable AI models can be produced using more cost-efficient approaches. This could put pressure on the pricing structures of American technology companies.

If businesses can access capable AI systems at considerably lower prices, the commercial returns expected by companies investing heavily in infrastructure could be affected.

The AI industry may ultimately become much larger, but that does not guarantee that every company currently investing in it will generate attractive returns.

The political landscape changes

The U.S. midterm elections have introduced another dimension.

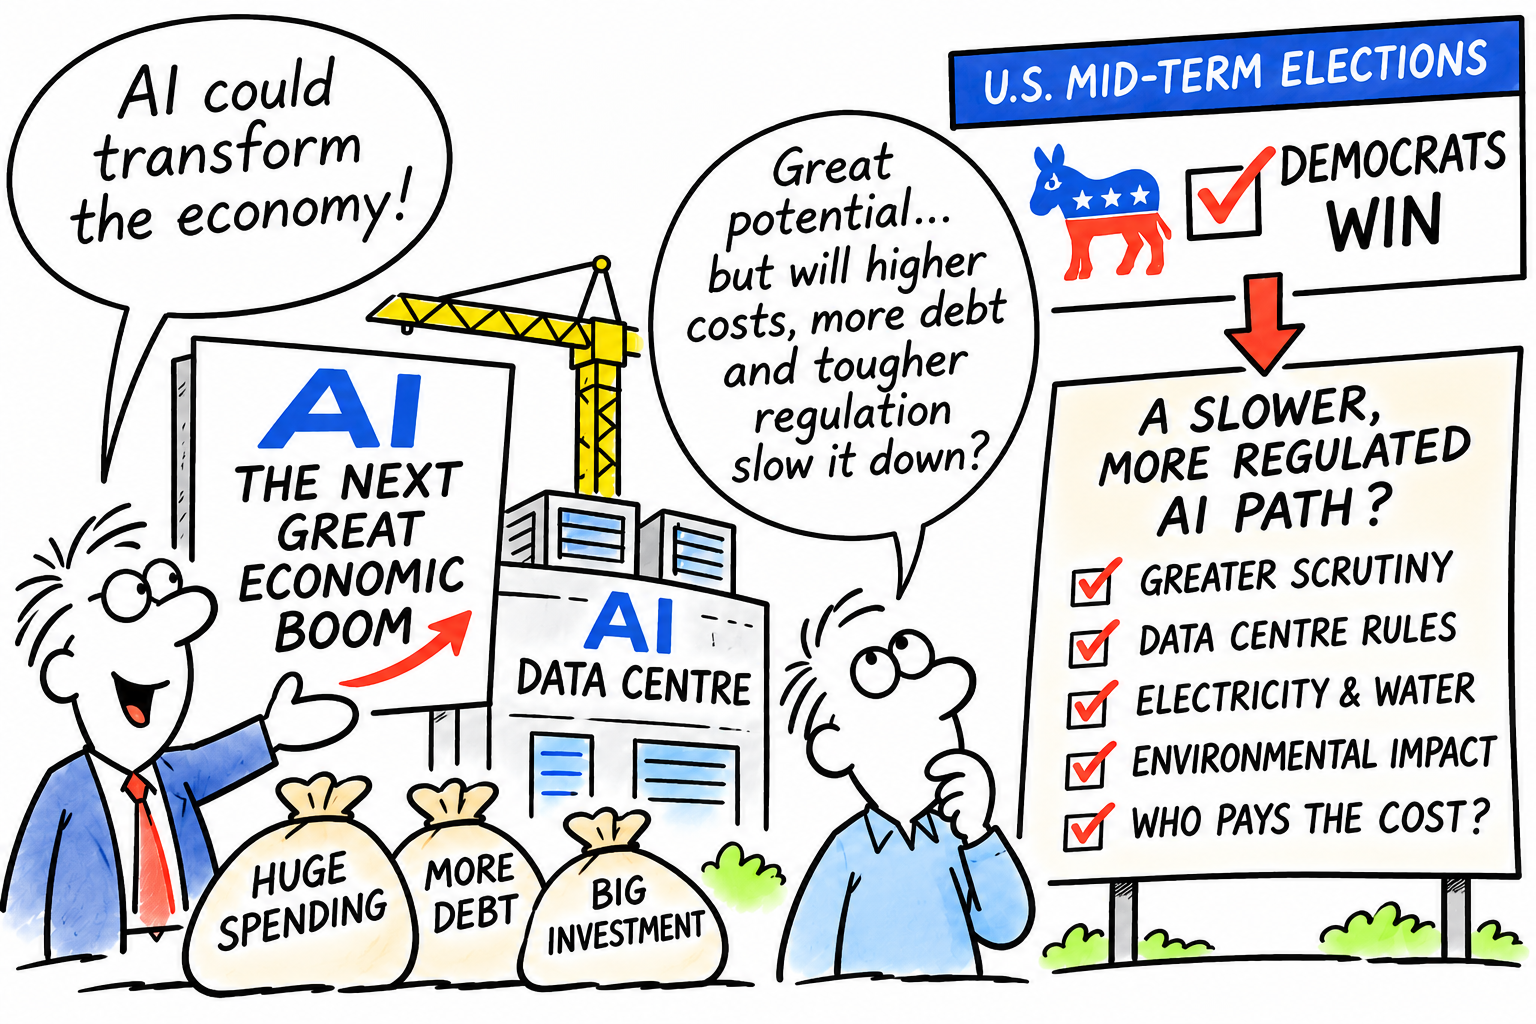
Democrats have secured control of both the House of Representatives and the Senate, creating a more challenging political environment for President Trump during the remainder of his term.

Technology companies could face increased scrutiny over data-centre construction, electricity consumption, environmental considerations, water supplies and AI regulation.

There are already disagreements in Washington over who should pay for the additional electricity infrastructure required by data centres. Some lawmakers want technology companies to shoulder more of the cost rather than passing it on to ordinary electricity consumers.

These concerns are particularly relevant in states such as Texas, where substantial AI infrastructure investment is planned.

Greater political scrutiny does not necessarily mean that AI development will stop. However, additional regulation, planning restrictions and infrastructure costs could slow the expansion or reduce the profitability of some projects.

Why is the Nasdaq recovering?

Despite these concerns, technology shares have recently demonstrated considerable resilience.

On 3rd November 2026, the Nasdaq gained approximately 0.83%, supported by a recovery in major AI and semiconductor shares. Nvidia, Broadcom and Micron were among the beneficiaries.

However, this recovery seemed to start ahead of the full midterm election results. Following the Democratic victories, global markets initially reacted negatively, reflecting concerns about potential regulatory changes and the future pace of AI infrastructure investment.

The recovery in technology shares should therefore not be interpreted as evidence that the underlying problems have disappeared.

Investors may be buying following recent declines, taking advantage of lower valuations or closing short positions. Such activity can produce substantial market recoveries without any corresponding improvement in the industry’s financial fundamentals.

A defining moment for investors

The AI revolution could ultimately prove to be one of the most important technological developments in modern economic history. Its potential should not be underestimated.

However, technological success and investment success are not necessarily the same thing.

The companies building the infrastructure must demonstrate that their investments can generate sustainable revenues, adequate cash flow and acceptable returns. Meanwhile, increasing borrowing, competition, resource constraints and political intervention could complicate that process.

For investors, the next stage of the AI story may be less about excitement surrounding technological possibilities and more about financial discipline.

Capital expenditure, debt issuance, free cash flow, AI-related revenues and institutional investment decisions deserve particularly close attention.

The wider economic consequences also matter. If AI delivers the productivity improvements its supporters anticipate, the benefits could extend well beyond the technology sector.

Conversely, if investment expectations become disconnected from commercial reality, the financial consequences could reach credit markets and the wider economy.

The AI revolution may be gathering momentum, but the investment boom financing it is approaching an important test.

The question is no longer simply how transformative AI might become. It is whether the extraordinary sums being committed today can generate sufficient economic value tomorrow.

For investors, that distinction could become increasingly important.

Britain Told to Prepare for Disruption: Why Now?

UK prepare warning!

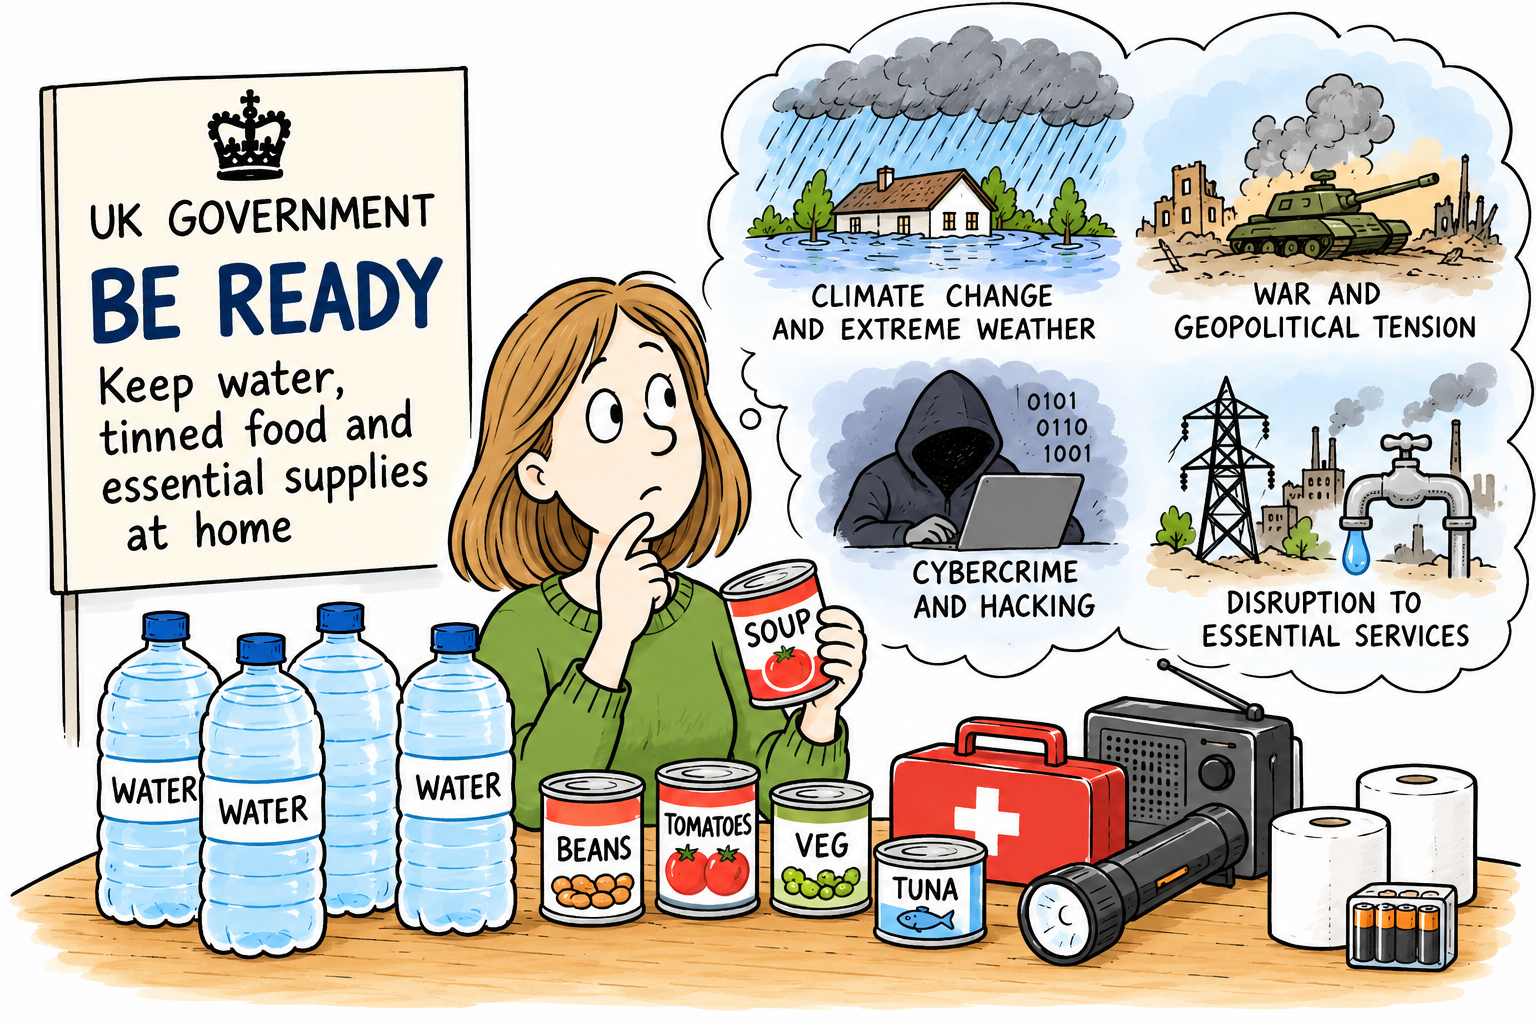
The British government’s advised UK households on 22nd October 2026 to prepare for emergencies by keeping essential supplies, including drinking water and tinned food.

This has raised an obvious question: what does the government know that the public should be worried about? Or is this ‘nothing’ other than sensible thinking?

The answer is more complicated than the prospect of an imminent war or national emergency.

Britain faces a combination of risks, from climate change and extreme weather to cyberattacks, international conflict and disruption to essential services.

The concern is that several problems could occur simultaneously, leaving households temporarily without electricity, water, communications or access to shops.

Why now?

The international security environment has deteriorated. The war in Ukraine, tensions in the Middle East, increasingly confrontational relations between major powers and the vulnerability of critical infrastructure have all reinforced the importance of national preparedness.

Cybercrime and state-sponsored cyberattacks also threaten systems on which modern life depends, including energy networks, financial services and water supplies.

Climate change presents a different but equally practical challenge. Flooding, storms, drought and extreme temperatures can disrupt transport, damage infrastructure and interrupt supplies.

Britain’s reliance on interconnected systems means that a problem in one area can quickly affect another.

The government’s message reflects a growing recognition that emergency services cannot necessarily reach everyone immediately during a major incident. Households may need to manage independently while essential services are restored.

What is really behind the announcement?

The timing is significant. On 22nd October 2026, the Cabinet Office announced a new three-year “Be Ready” campaign.

The advice asks people to prepare to manage for three days, including keeping bottled water and non-perishable food at home.

The government says only 13% of people feel prepared for an emergency that could cut them off from essential services.

A recent PHP software security incident, which reportedly triggered millions of hacking attempts, has also highlighted the potential consequences of cyber vulnerabilities.

Officials have warned about the growing threats posed by hostile states, organised crime and the use of artificial intelligence to identify weaknesses in computer systems.

There is, however, an important distinction between preparing for a risk and predicting that it will happen.

There is no confirmed evidence in the published announcement that the government expects an imminent war, nationwide blackout or collapse of essential supplies.

Its stated objective is to improve the country’s ability to withstand emergencies, rather than to signal that a particular disaster is approaching.

It is not just the UK, other European countries such as, Germany, Sweden, Finland, Netherlands, Norway and France have also offered this warning

A warning worth taking seriously

The underlying message is that modern Britain is vulnerable to disruptions that could affect millions of people.

Electricity, water, banking, communications and food distribution are interconnected. A serious failure in one system can have consequences far beyond its original cause.

The government is also seeking to reduce pressure on emergency services by encouraging households to cope independently during the initial stages of an incident.

The recommendation is modest: prepare gradually, keep essential supplies and avoid panic buying. For a household, three days of drinking water means approximately nine litres per person, with additional water needed for cooking and hygiene.

Rising risks

The real reason for the announcement is therefore a combination of rising risks, lessons from recent disruptions and a recognition that public preparedness remains inadequate.

Whether the next emergency comes from extreme weather, a cyberattack or international conflict, the government wants Britain to be less dependent on an immediate rescue.

Electricity: A major grid failure could disrupt homes, businesses, transport and public services.

Heating/Energy/Oil: During a winter outage, homes could become dangerously cold, particularly if heating systems depend on electricity.

Water: Pumping and treatment systems can be affected by prolonged electricity failures.

Food: Supermarkets, refrigeration, distribution centres and payment systems all depend on reliable power.

Communications: Mobile networks and internet services may become unavailable if backup systems are exhausted.

Cybersecurity: An attack on critical infrastructure could cause disruption even when there is no physical damage.

That is sensible contingency planning. It is not proof of a secret warning. But it does underline an uncomfortable reality?

The stability of everyday life depends on infrastructure and international systems that individuals cannot control, and which may not always work when they are needed most.

Be prepared is the clear message!

You have been warned!

Britain’s £3 Trillion Debt: The Oil Fund Norway Built and the UK Never Did

UK debt and no wealth fund problem

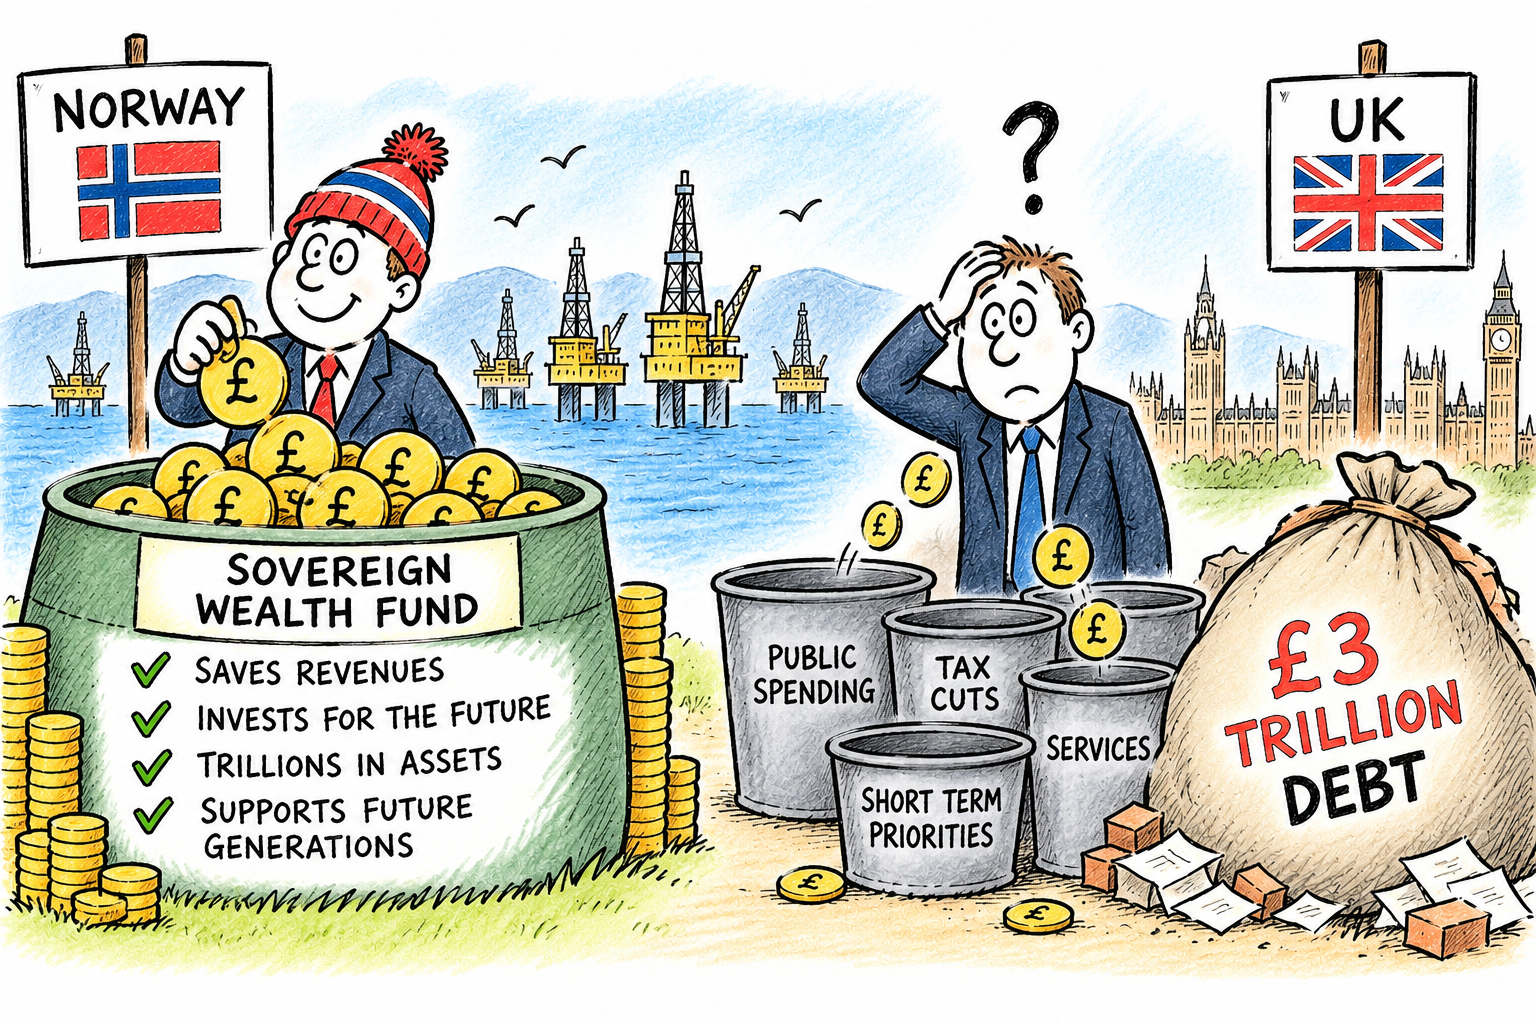
Britain sits on a mountain of public debt approaching £3 trillion, yet decades ago it discovered a resource that could have transformed the nation’s financial future.

North Sea oil generated enormous revenues, but unlike Norway, Britain failed to turn its petroleum wealth into a lasting national investment fund.

The missed opportunity remains one of the most striking examples of short-term political thinking in modern economic history.

Oil production sideline

When North Sea oil production expanded during the 1970s and 1980s, the UK government received substantial revenues from petroleum taxes and royalties.

Norway, whose North Sea oil industry developed around the same period, took a different approach. It established a sovereign wealth fund in 1990, subsequently investing much of its petroleum wealth in international financial markets for the benefit of future generations.

Norway’s Government Pension Fund Global

Today, Norway’s Government Pension Fund Global is worth trillions of pounds. Its investments span thousands of companies, bonds and other assets worldwide, generating returns that help support Norway’s public finances.

The fund has become a financial buffer against economic shocks and the eventual decline of oil and gas production.

Spend

Britain, by contrast, largely spent its oil revenues as they arrived. They helped support government finances during a period of economic restructuring, tax reductions and changing public spending priorities.

The revenues also contributed to the wider economy, while North Sea production helped improve the UK’s balance of payments.

The argument is not that every pound of British oil revenue simply disappeared. Rather, the country failed to preserve a substantial share of this finite natural resource wealth in a dedicated, long-term investment fund.

Why?

Why did Britain make such a different choice? Politics was central. Successive governments faced immediate demands to control borrowing, finance public services, manage unemployment and respond to economic difficulties.

Creating a fund would have required the political discipline to save revenues rather than use them to meet current priorities.

There was also no lasting national consensus that oil wealth should be treated as capital belonging to future generations. Norway built institutions and rules around that principle. Britain never established an equivalent framework on a comparable scale.

Consequnce

The consequences are difficult to quantify precisely. A British sovereign wealth fund would not automatically have accumulated the same returns as Norway’s, and its performance would have depended on how much was invested, when investments were made and how they were managed.

Nevertheless, even a smaller fund could have provided valuable national assets and an additional source of investment income.

With public debt now approaching £3 trillion, the contrast is uncomfortable. Britain extracted a finite resource but did not convert enough of its proceeds into lasting financial wealth.

Norway saved a significant share of its oil windfall. Britain largely consumed its own. The question is whether future generations will repeat that mistake.

Note:

The £1 trillion figure is a hypothetical Treasury estimate based on investing roughly £200 billion in historical North Sea revenues and allowing the money to grow at a rate comparable to Norway’s fund. It is not a guaranteed amount Britain would have accumulated.

The UK’s public sector net debt was provisionally estimated at £3.005 trillion at the end of September 2026, according to the Office for National Statistics.

Global debt has reportedly surged to $365 trillion, prompting economists to warn about a looming ‘vicious cycle’

Debt and the beggar

The combination of record global debt, higher borrowing costs and growing doubts about the enormous sums being committed to artificial intelligence is creating a more complicated backdrop for financial markets.

Global debt exceeded $365 trillion in the first half of 2026, according to the Institute of International Finance, with debt now around 310% of global GDP.

China and the U.S. debt mountain

The increase was driven particularly by China and the United States. At the same time, higher interest rates are making refinancing increasingly expensive, creating the possibility of a vicious cycle in which governments and companies borrow more simply to service existing obligations.

This is particularly significant for the AI boom. The OECD says governments and companies are expected to borrow around $29 trillion from markets during 2026, while corporate borrowing is also rising as businesses finance major investment programmes, including AI infrastructure.

Michael Burry

Michael Burry, famous for anticipating the U.S. housing crisis, has added another warning sign.

He has recently reportedly increased bearish positions involving Micron, Palantir, Nebius and the semiconductor sector, arguing that parts of the AI and chip boom could be vulnerable if supply increases faster than demand.

The concern is not necessarily that AI will fail. Rather, enormous investment and borrowing require enormous future revenues to justify them.

If AI spending produces lower-than-expected returns, highly valued technology shares could face pressure at the same time as heavily indebted companies face rising financing costs.

Could this affect the stock market now?

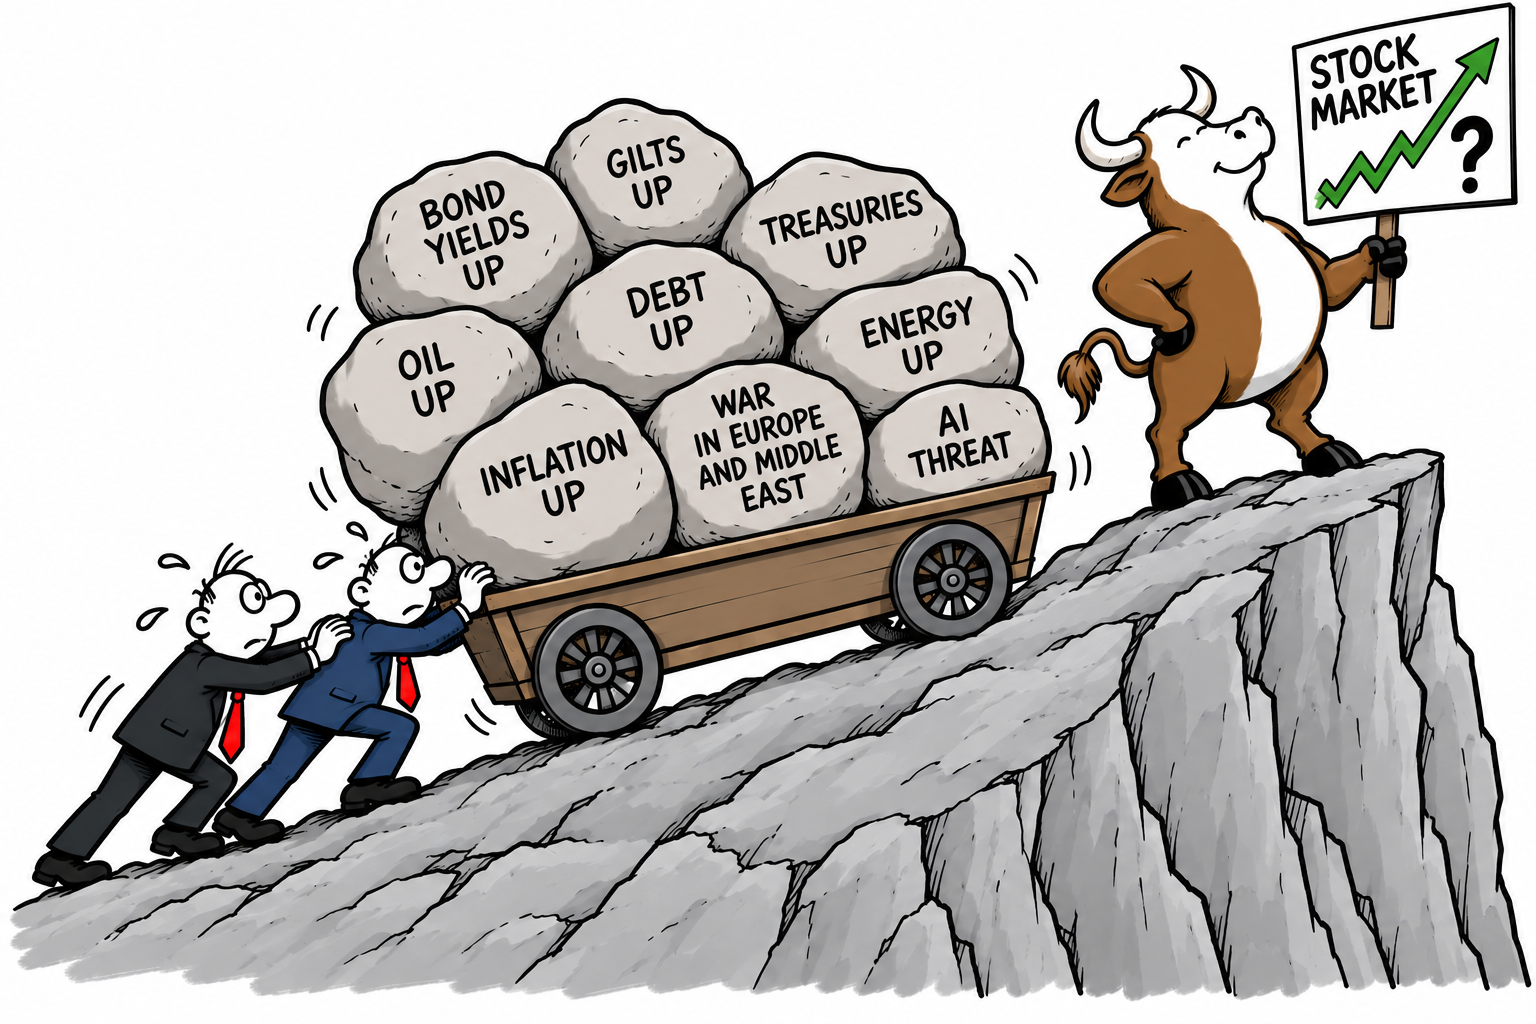
The ingredients for greater volatility are certainly present. Higher bond yields, expensive energy, inflation pressures and debt-servicing costs can compete with equities for investors’ money.

Reuters recently reported that global borrowing costs and energy prices were already creating concerns about the potential impact on equities and credit markets.

Yet markets have so far remained remarkably resilient, with U.S. shares still close to record levels.

The danger, therefore, may not be debt alone, but…

debt + high valuations + expensive AI investment + higher interest rates.

If those pressures reinforce one another, the adjustment in markets could become considerably more significant.

Why Are Markets Still Rising Despite Ongoing Bad World News?

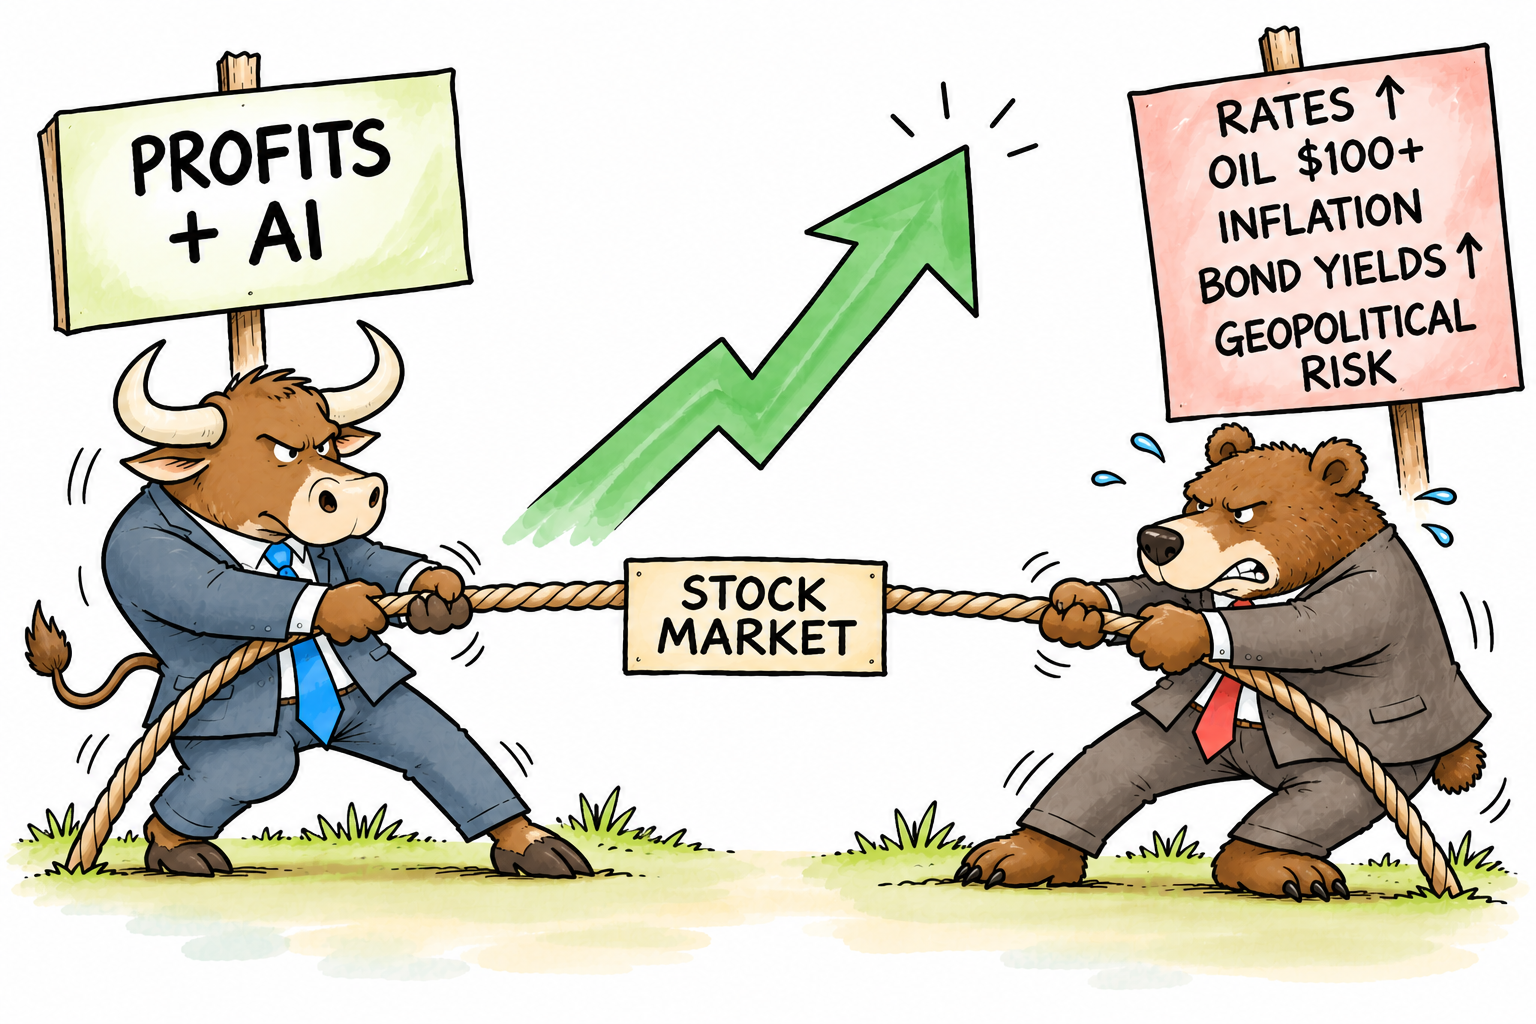
Stock market tug-o-war

Stock markets are continuing to climb despite a growing list of concerns that would normally be expected to unsettle investors.

Interest rates are higher, government bond yields have risen, oil prices are elevated and inflation remains a concern. Geopolitical tensions are also creating uncertainty. Tariffs still on the agenda. Global debt rising and rogue AI concerns.

Yet investors continue to buy shares, particularly in the United States.

So why?

One important reason is corporate earnings. Investors appear willing to tolerate higher interest rates and expensive valuations while they believe company profits will continue to grow.

Large technology companies, in particular, remain at the centre of this optimism, with huge investment in artificial intelligence fuelling expectations of strong future earnings.

Buying dips

Another factor is the willingness of investors to buy market dips. When share prices fall, investors who remain confident about the longer-term outlook see an opportunity to buy at cheaper prices.

This can create a self-reinforcing cycle: markets fall, buyers move in, confidence returns and prices rise again.

There is also a belief that the economy remains sufficiently resilient to withstand higher borrowing costs and expensive energy.

Bad news is therefore being viewed as a problem, but not necessarily one capable of seriously damaging corporate profits.

However, this resilience could eventually be tested.

Earnings faith

The market is currently placing considerable faith in continued earnings growth and the economic benefits of artificial intelligence. If either begins to disappoint, investors could reassess the high valuations attached to many shares.

Higher oil prices could also keep inflation elevated, forcing interest rates to remain higher for longer. Rising bond yields would then provide investors with an increasingly attractive alternative to shares.

Bull Bear

For now, the bulls remain in control of market prices, even though the bears have plenty of arguments on their side.

The important question is whether company profits can continue to justify today’s share prices.

If they can, markets may continue climbing despite the bad news. If they cannot, investors may suddenly start paying much closer attention to all those warning signs they have recently been ignoring.

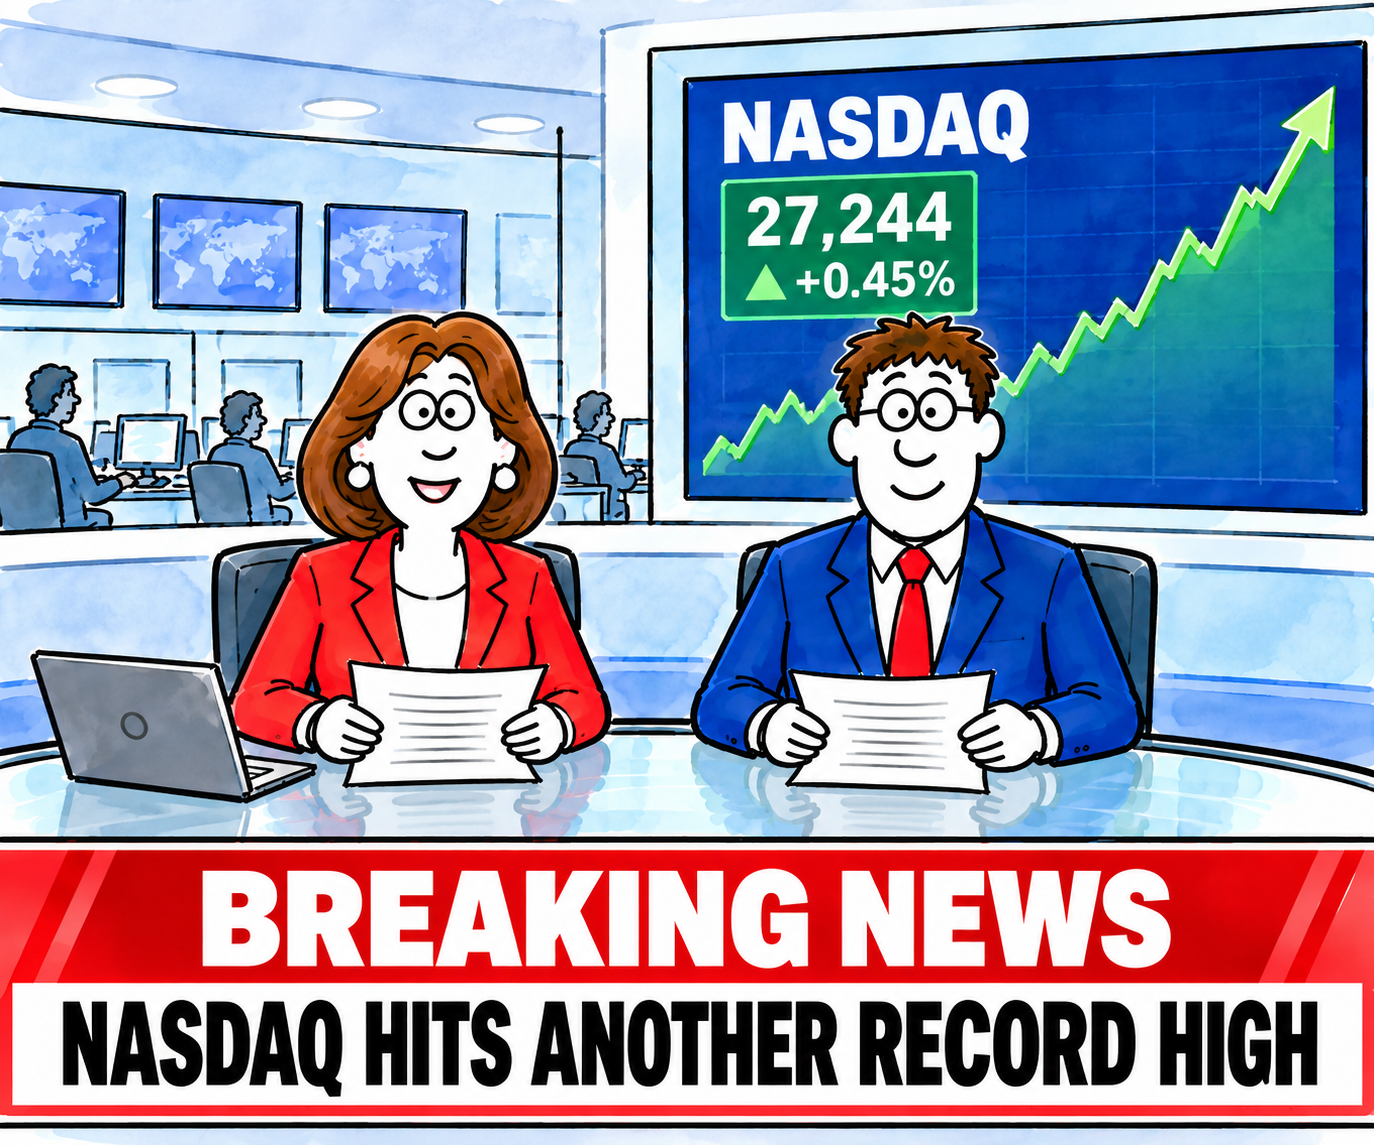
Nasdaq hits another new all-time high!

Nasdaq New High!

The Nasdaq Composite climbed to another record high on Tuesday 22nd September 2026, extending its remarkable run despite a backdrop of considerable economic and geopolitical uncertainty.

The technology-heavy index reached an intraday record of around 27,289 before closing at approximately 27,244, also a new record.

AI-related shares remained an important driver of the advance, with investors continuing to pour money into the technology sector.

However, the latest milestone comes amid concerns over stretched valuations, rising bond yields, expensive energy, tariffs and geopolitical tensions. The huge borrowing commitments being made to finance AI infrastructure are a massive issue too.

The contrast between record markets and broader uncertainty remains of concern.

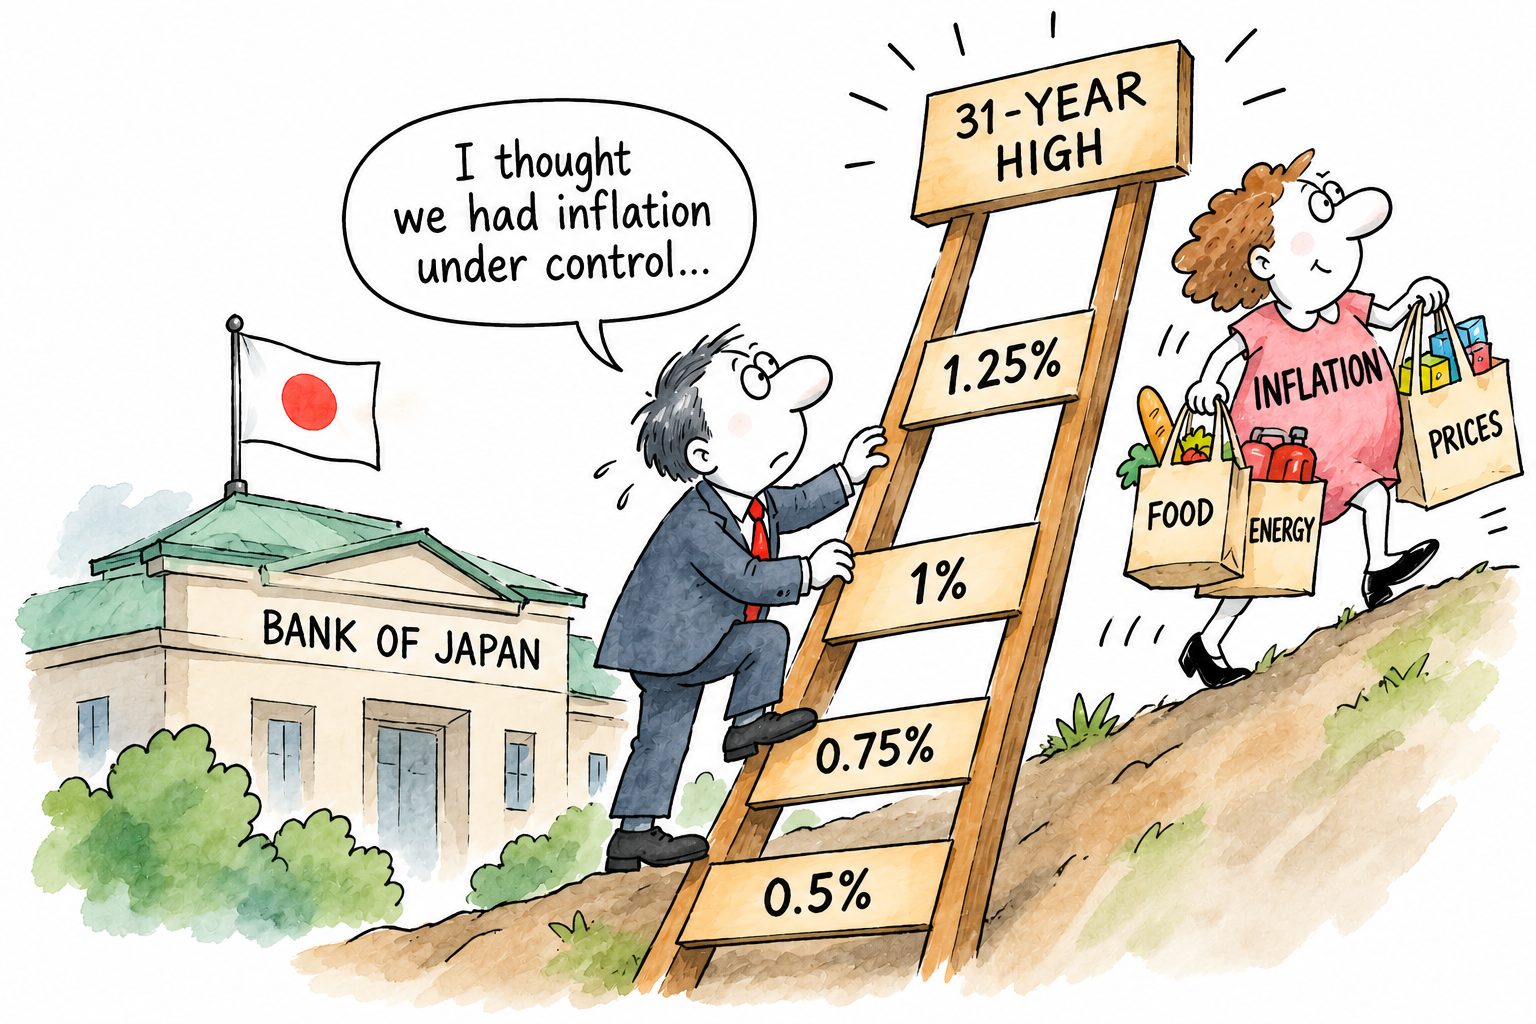
Bank of Japan hikes Interest rate by 0.25% to 1.25%

Japan raises interest rate

The Bank of Japan has raised its benchmark interest rate to 1.25%, its highest level in 31 years, as it steps up efforts to contain inflation.

The quarter-point increase from 1% was approved by a 7-2 vote and had been widely expected by financial markets.

A Familiar story of energy inflation

Governor Kazuo Ueda reportedly said the move reflected growing concerns that inflation could overshoot the Bank’s 2% target.

Higher energy costs, a weaker yen and rising prices linked to strong demand are adding to pressure on the Japanese economy.

The decision marks another step away from Japan’s decades of ultra-low and negative interest rates.

However, two policymakers opposed the increase, highlighting concerns about economic conditions and the pace of further tightening.

The yen weakened following the announcement, as investors assessed how quickly the Bank might raise rates again.

Bank of England Holds Interest Rate at 3.75%

Bank of England holds rate

The Bank of England has held interest rates at 3.75% on 17th September 2026 but warned that persistently high energy costs could force rates higher.

The Monetary Policy Committee voted 6-3 to keep Bank Rate unchanged, while three members backed an increase to 4%.

Governor Andrew Bailey reportedly said the outlook remained uncertain, with rising energy prices creating renewed inflationary pressure.

UK inflation reached 3.1% in August 2026 and the Bank expects it to rise further, potentially exceeding 4% in early 2027 if energy costs remain elevated.

Bailey reportedly said that if the Middle East conflict persists and inflationary risks increase, monetary policy may need to tighten.

Why Won’t the Stock Market Correct – Especially with all the Issues Facing it?

Stock Market Correction Soon?

There was a time when any one of these developments would have been enough to frighten investors: rising government bond yields, higher borrowing costs, stubborn inflation, soaring oil and energy prices, mounting government debt, war in Europe and the Middle East and tariff wars.

And now with the growing threat of AI safety and concerns about whether the enormous investment in artificial intelligence can continue at its current pace.

Put them all together and, logically, the stock market should be facing a serious test.

Yet it continues to demonstrate remarkable resilience.

Irony

The irony is that many of these pressures are already showing up in financial markets. U.S. Treasury yields have moved above 5%, their highest levels since 2007, while oil has climbed above $100 a barrel.

Rising energy prices are feeding inflation concerns, while higher yields are increasing the cost of borrowing. Reuters reported on Tuesday that the Dow, S&P 500 and Nasdaq all fell, but the declines remained relatively contained.

So why hasn’t this combination produced a much larger correction?

One explanation is that markets are not simply pricing today’s problems. They are pricing what investors believe the world will look like several months or years from now – or so we are told.

Corporate earnings remain a powerful counterweight. If profits continue to grow rapidly, investors can tolerate higher interest rates and higher valuations for longer.

Reuters notes that continued earnings growth and enthusiasm surrounding AI have helped keep U.S. equities relatively resilient despite the rise in Treasury yields.

There is also an extraordinary amount of money invested in equities. Pension funds, investment funds, corporations and individual investors cannot simply abandon shares every time the economic outlook deteriorates.

There are relatively few places capable of absorbing enormous amounts of capital.

Don’t sell – carry on regardless

And perhaps most importantly, investors have repeatedly learned that selling during every crisis can be expensive.

Inflation? The market survived it.

War? Markets have survived wars before – but markets did correct.

Tariffs – markets have shrugged there off!

Higher interest rates? Markets can rise during tightening cycles if the economy and corporate profits remain strong.

Oil shocks? They can damage consumers and businesses, but they can simultaneously boost the profits of energy companies.

Even the AI problem is complicated. A slowdown in AI investment could hurt some enormously valued technology companies, but it would not necessarily destroy the entire economy.

Indeed, markets have already shown that AI concerns can cause sector-specific selling without automatically triggering a broad collapse.

The real question, therefore, may not be why the market hasn’t fallen.

It is what would finally make investors collectively stop believing that the next problem can be absorbed?

Because markets rarely collapse simply because there are lots of problems.

They collapse when investors suddenly decide that those problems can no longer be ignored.

Stock market offers ‘easy money’?

It certainly sounds like easy money — if only markets worked that way. The danger is assuming that resilience means invincibility: a market can shrug off one problem, then another, and even several simultaneously, right up until investors collectively decide that earnings, valuations, interest rates or economic growth no longer justify the prices they are paying.

Until that moment arrives, bad news can simply be absorbed, explained away or declared temporary; when it does arrive, however, the same market that seemed capable of ignoring everything can suddenly discover that everything matters after all.

Difficulty


The difficult part is that there is no reliable way to say when it will happen — markets can remain expensive and resilient for considerably longer than economic logic might suggest.

The eventual correction is more likely to come when several pressures stop being viewed as temporary or manageable and begin to undermine the assumptions supporting corporate earnings and valuations: persistently high inflation, materially higher borrowing costs, weaker growth, falling profits, an AI investment slowdown, or an unexpected financial shock could each become the catalyst.

Until investors collectively change their expectations, the market can continue climbing despite an increasingly uncomfortable list of warning signs — but resilience should not be confused with immunity.

Fed Raises Rates – And Markets Now Face a New Question

U.S. inflation

The Federal Reserve raised US interest rates by 25 basis points yesterday, taking its benchmark rate to 3.75%-4% and delivering the first increase since 2023.

The move puts U.S. inflation firmly back at the centre of the market conversation. Despite months of speculation about the direction of monetary policy, the Fed has signalled that persistent price pressures remain enough of a concern to warrant tighter financial conditions.

For investors, however, yesterday’s increase may be less important than what comes next

Markets must now decide whether the move represents a relatively modest adjustment to policy or the beginning of another tightening phase.

Any suggestion that further increases are coming could push U.S. Treasury yields and the dollar higher while placing renewed pressure on highly valued equities.

That matters particularly for a U.S. stock market already trading at elevated levels, with enthusiasm surrounding artificial intelligence continuing to support many of its largest companies.

Balancing act

The Fed therefore faces a difficult balancing act. It wants to bring U.S. inflation under control without unnecessarily damaging economic growth or employment.

For Wall Street, the question has changed.

It is no longer simply when will rates fall?

It is now how high might they have to go?

U.S. 10-Year Treasury Yield Hits 5%: A New Problem for Markets

U.S. Yields Up!

The U.S. bond market is flashing an increasingly uncomfortable warning signal. The yield on the benchmark 10-year Treasury has climbed above 5%, reaching its highest level since 2007 as investors brace for potentially higher interest rates from the Federal Reserve.

The yield subsequently moved above 5.04%, highlighting the severity of the bond sell-off.

Stubborn

Several forces are pushing yields higher. Inflation remains stubborn, while oil prices have surged above $100 a barrel amid geopolitical tensions, raising fears that another energy shock could feed directly into consumer prices.

Borrowing cost

At the same time, investors are demanding greater returns to hold U.S. government debt because of enormous borrowing requirements and concerns about the country’s long-term fiscal position.

This creates a difficult problem for the Federal Reserve. Higher Treasury yields are already tightening financial conditions, yet persistent inflation could force the Fed to raise interest rates further.

Markets are increasingly pricing in the possibility of another rate increase, potentially taking short-term rates towards or above 5%.

Consequence

The consequences could be significant. The 10-year Treasury is a benchmark for mortgages, corporate borrowing and many other financial products.

As its yield rises, borrowing becomes more expensive across the economy. Businesses may postpone investment, consumers may reduce spending and highly indebted companies could come under increasing pressure.

Debt concern

There is also a problem for government finances. Higher yields mean the U.S. Treasury must pay more to refinance its enormous debt pile, potentially creating a vicious circle: more borrowing leads to greater interest costs, which can require still more borrowing.

For investors, a 5% Treasury yield also makes government bonds increasingly attractive compared with riskier assets.

That could put further pressure on highly valued shares, particularly technology and growth companies.

The danger is therefore not simply a higher interest rate. It is the possibility that 5% becomes the new normal.

ECB Raises Interest Rates as Inflation Fears Return

ECB raised interest rates

On September 10th 2026, the European Central Bank (ECB) raised interest rates in an effort to stop a new wave of inflation from taking hold across the eurozone.

The ECB increased its key deposit rate by 0.25 percentage points to 2.5%, its second rate increase this year. The move comes as inflation has risen above 3%, well above the ECB’s 2% target.

Much of the renewed pressure is being blamed on higher energy prices, linked to the continuing conflict in the Middle East.

Energy costs

More expensive oil and gas can quickly feed through into transport, food and household bills, raising fears that inflation could prove more persistent than previously expected.

The problem for the ECB is that higher interest rates can also weaken economic growth. More expensive mortgages and business loans can discourage households from spending and companies from investing.

Challenge

Although the eurozone economy has shown some resilience, the outlook remains uncertain. The ECB expects inflation to average around 3% this year, while economic growth is expected to remain relatively weak.

The ECB now faces a difficult balancing act: raise rates enough to control inflation, but not so much that it pushes the economy into a deeper slowdown.

Investors are already likely wondering whether further increases could follow in the months ahead.

UK borrowing costs hit 28-year high: is austerity about to return? Did it ever leave?

UK and World Debt

Britain’s fiscal squeeze is becoming increasingly difficult to ignore. The yield on the UK’s 30-year gilt has climbed to 5.89% — its highest level since 1998 — while the 10-year yield has risen to around 5.25%.

The immediate trigger is largely global: higher oil prices, renewed inflation fears and a worldwide bond sell-off. But Britain has an additional problem: an already stretched public finances position.

Tax, borrow or austerity – the familiar story

The timing could hardly be worse. Higher gilt yields mean higher future borrowing costs and, importantly, higher projected debt-interest payments.

Current estimates suggest that the rise in yields could roughly halve the Chancellor’s fiscal headroom, from around £26bn to about £13.8bn.

That leaves the government with an increasingly familiar choice: raise taxes, restrain spending, borrow more — or accept another round of austerity.

Burgeoning welfare

Welfare is inevitably part of the debate. UK welfare spending is enormous, projected at around £353bn in 2026-27, although more than half goes towards pensioners and the State Pension rather than working-age benefits.

The working-age and health-related components are nevertheless growing rapidly, creating a genuine long-term fiscal challenge.

But blaming welfare alone would be misleading. Debt interest itself has become a major burden. Public-sector net debt was around 95% of GDP in mid-2026, while debt-interest costs have been among their highest levels for decades.

The circle of failure

This is the vicious circle facing Britain: slow growth limits tax revenues; high spending increases borrowing; higher borrowing costs increase debt interest; and higher interest costs leave less money for public services and investment.

So is austerity coming back? Perhaps it never really left. The difference now is that governments are attempting to squeeze an increasingly expensive state while simultaneously trying to protect living standards and stimulate growth.

The October 2026 Budget may therefore be less about political ambition and more about how much pain the bond market will allow Britain to avoid.

Servicing debt

Borrowing costs in the U.S., Japan and Europe have hit similar highs in recent days, reflecting investors’ concerns about inflation, state borrowing levels and spending levels by large tech companies on AI.

World debt is a growing problem too

To be fair, rising yields and higher debt levels are not just a UK problem. France has its share of the burden, Japan, the EU and the U.S. too.

No one is immune to rising yields and debt.

U.S. strategic Oil Reserves under Pressure

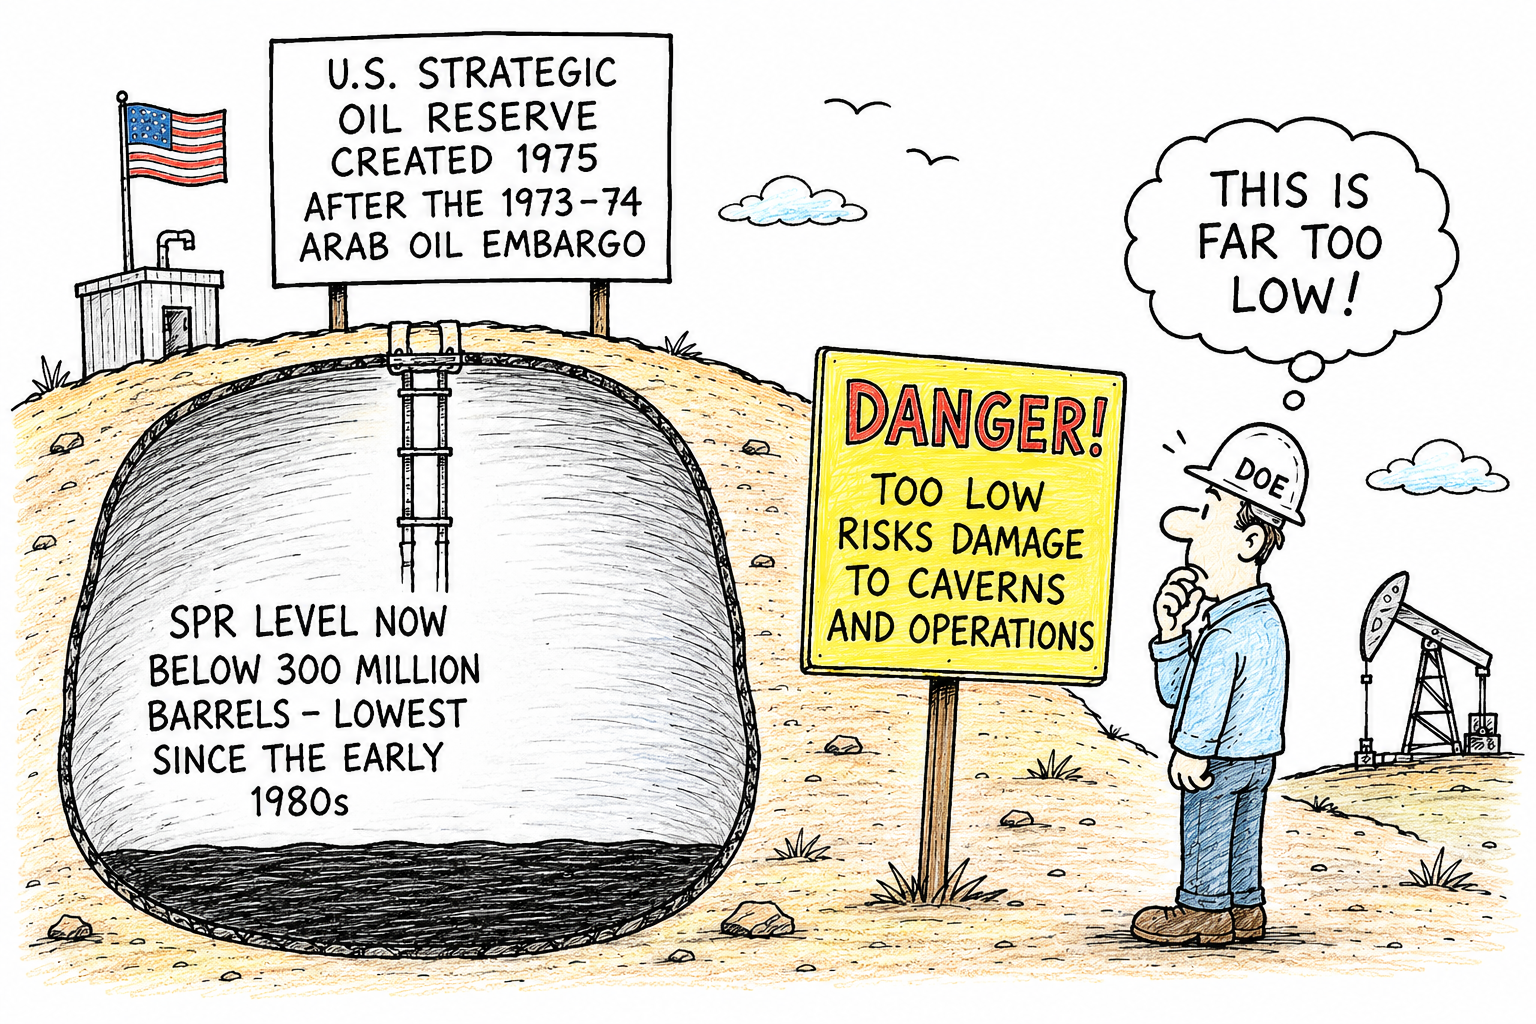
America’s Strategic Petroleum Reserve (SPR) was created in 1975, in the aftermath of the 1973–74 Arab oil embargo, when an oil supply shock exposed America’s vulnerability to disruptions in foreign energy supplies.

Its purpose was straightforward: provide the United States with an emergency stockpile of crude oil that could be released if supplies were suddenly threatened.

More than 50 years later, that safety net is looking increasingly fragile.

Depleted levels

The SPR has fallen to around, and now below, 300 million barrels — its lowest level since the early 1980s. The decline follows a succession of major releases, including the huge drawdown ordered in 2022 to help counter the surge in oil prices following Russia’s invasion of Ukraine.

The problem is not simply that America has less oil available during an emergency. The crude is stored deep underground in enormous salt caverns, and repeatedly removing and replacing large quantities of oil creates additional engineering and operational challenges.

Concerns have been raised that allowing inventories to fall too far could complicate the safe and efficient operation of some caverns.

Collapse

That does not mean the underground storage sites are on the verge of collapse. The SPR was specifically designed around the properties of salt formations, and the facilities are subject to extensive monitoring and maintenance.

But the reserve was never intended to be routinely used as a tool for managing ordinary fluctuations in oil prices.

Rebuilding it is also a slow process. Buying hundreds of millions of barrels requires money, suitable crude and sufficient time to inject it back into the caverns. The infrastructure itself must also remain operational.

That leaves Washington facing an uncomfortable dilemma. The SPR exists precisely to be used during an energy crisis.

But if it is drawn down too aggressively, America risks weakening the very emergency insurance policy created in 1975 to protect it.

The strategic question is no longer simply how much oil America has — but how much of its emergency reserve it can safely afford to use.

Deal or No Deal – The President of The United States and his Team Tease an Iran Deal, Markets Soar — Again. And Then Nothing. Why Does This Keep Happening?

Deal or no deal?

It has become an increasingly familiar pattern: Donald Trump hints that an agreement with Iran is close, investors breathe a sigh of relief, oil prices fall and stock markets jump — only for the promised breakthrough to fail to materialise. Why?

Deal or no deal

This week (early-August 2026) was another example. Trump and members of his administration suggested that progress towards an agreement involving Iran and the Strait of Hormuz could come within days.

Markets responded enthusiastically, betting that a deal would reduce the risk of prolonged conflict and ease pressure on global energy supplies.

Yet no comprehensive agreement appeared. Iran subsequently said direct talks with Washington would not take place while it considered the existing interim arrangement to be breached.

So why does it keep working?

Because financial markets trade expectations, not facts. The possibility of peace is enormously valuable when war threatens oil supplies, inflation and global growth.

Algorithms and traders react within seconds to headlines containing words such as “deal”, “ceasefire” or “agreement”.

Oil falls, equities rise and the economic relief can be priced in long before diplomats have actually agreed anything.

Loop of distrust

There is also a dangerous feedback loop. If markets repeatedly reward optimistic statements, there is little immediate financial incentive for politicians to stop making them.

Reports have previously documented dozens of occasions on which Trump suggested an Iran agreement was imminent without a final deal emerging.

Unhealthy relationship

That does not prove deliberate market manipulation. But it does expose a deeply unhealthy relationship between political rhetoric and financial markets.

Peace should be based on verified agreements, not carefully timed hints.

When a presidential statement can erase billions of dollars of perceived risk from markets before a single binding document exists, investors are effectively trading political promises.

And when those promises repeatedly fail to arrive, the credibility of both the politician and the market reaction suffers.

Shouldn’t markets price reality?

Not headlines. And certainly not hype.

Can U.S. markets ever fail… I wonder?

The Great Social Truth Manipulation

The Art of Manipulation

There is an old saying apparently that if you create a problem, you can then claim credit for solving it.

Whether that saying is fair in every circumstance is open to debate, but it raises an uncomfortable question about the way modern politics is increasingly presented to the public.

Every day we hear another announcement that “a deal is close”, “talks are progressing” or “a breakthrough is expected”. These headlines are designed to sound reassuring. They suggest that leaders are successfully navigating a difficult situation.

But what if we are asking the wrong question?

Perhaps we should not be asking whether another deal is close. Perhaps we should be asking why the deal has become necessary in the first place.

That is where the irony begins.

Take the current tensions involving the United States and Iran. The public is repeatedly encouraged to view the next agreement as a diplomatic success.

Yet before the military confrontation, there was already diplomacy. The Strait of Hormuz was open. Oil continued to flow. The world’s attention was focused on preventing escalation rather than recovering from it.

Today, after military action, regional instability and renewed fears over global shipping and energy supplies, we are told that another agreement will represent progress.

But is it progress?

Or is it simply an attempt to restore what already existed?

That distinction is rarely discussed.

Instead, public attention is directed towards the negotiations themselves.

Every meeting becomes news.

Every statement hints at a breakthrough.

Every possible agreement is presented as evidence that events are moving in the right direction.

The irony is that the benchmark has quietly changed.

Yesterday, stability was taken for granted. Today, merely returning to that same level of stability is presented as a diplomatic triumph.

This is how truth manipulation often works.

It does not necessarily rely upon telling outright lies. Instead, it changes the point from which people measure success.

Once the public stops comparing today’s position with where events began, and starts comparing today’s headlines with yesterday’s headlines, perceptions change. Recovery begins to look like achievement.

That is an extraordinarily effective political technique.

It shifts the conversation away from asking whether earlier decisions improved the situation and towards celebrating efforts to repair the consequences.

The public becomes invested in the next deal rather than reflecting upon whether the circumstances requiring that deal could have been avoided.

This is not an argument against diplomacy. Quite the opposite. Negotiation should always be preferred to conflict wherever possible.

Nor is it a claim that every crisis is avoidable. International affairs are rarely that simple.

The real issue is whether governments should be judged by the number of deals they announce or by whether their decisions leave the world in a better position than before.

That is the question often left unasked.

Perhaps the greatest social truth manipulation is persuading people to celebrate returning to yesterday’s starting point while calling it tomorrow’s success.

This pattern is hardly unique to one administration or one country. Governments throughout history have sought to frame events in ways that favour their own decisions.

However, democratic societies rely upon citizens asking a simple but essential question:

Are we genuinely better off than we were before?

U.S. jobs market cools in June

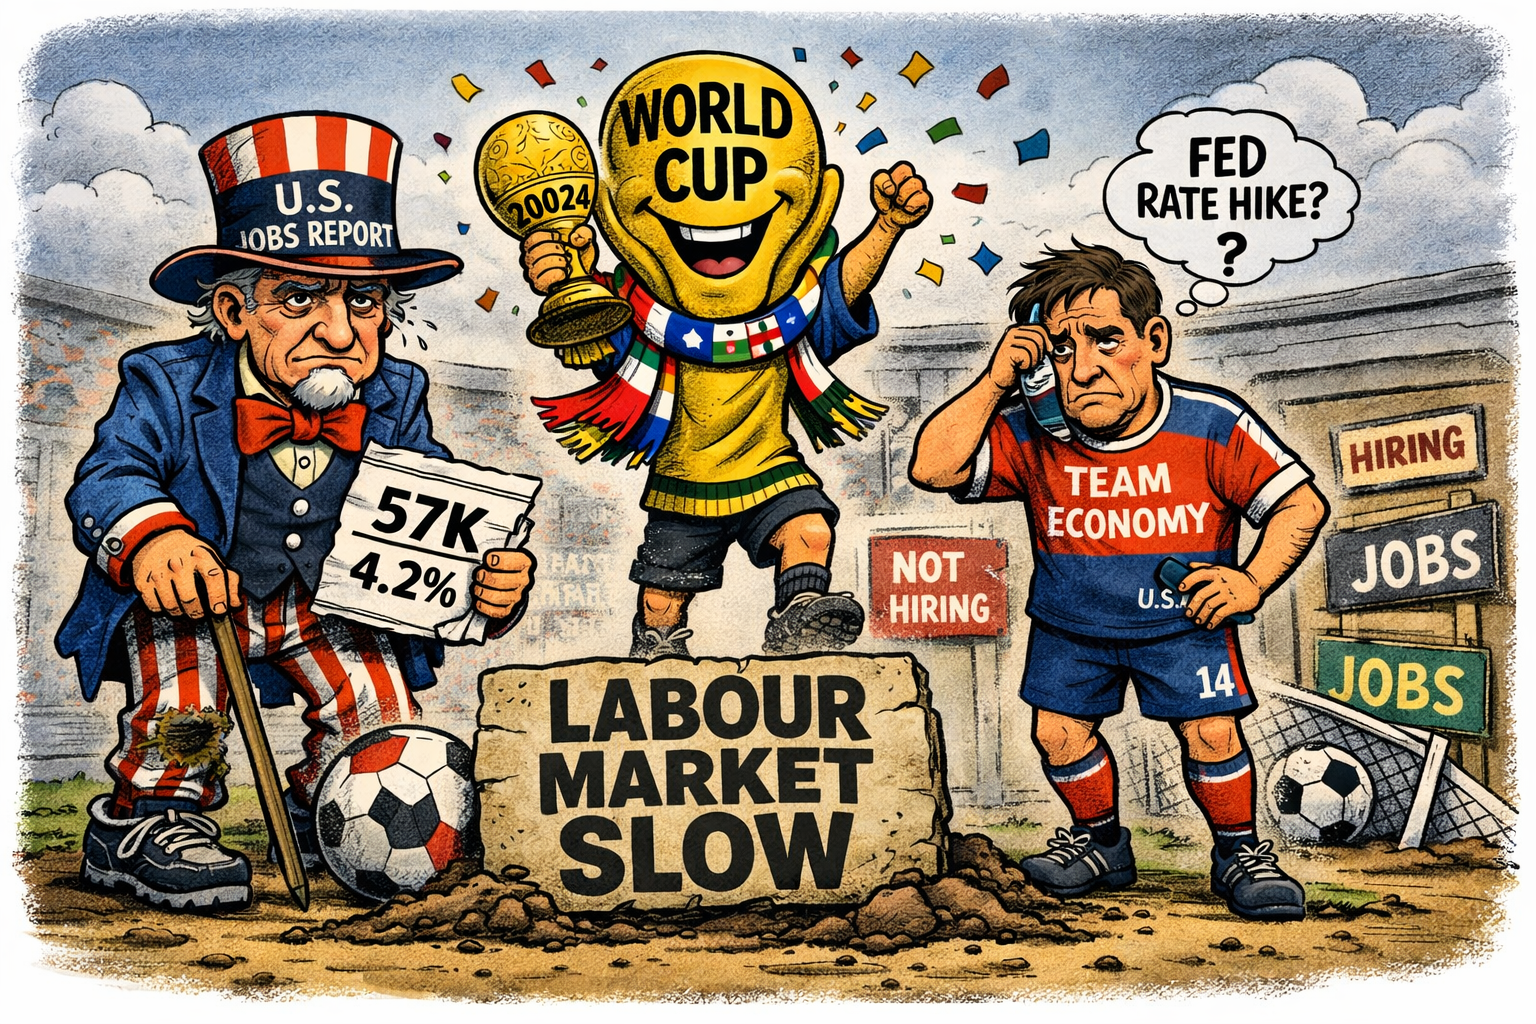
Hiring slows for the U.S. in June 2026

The latest U.S. jobs report underscored a clear cooling in labour market momentum, with June’s 2026 nonfarm payrolls rising by just 57,000, well below economists’ expectations and marking the weakest gain in four months.

And this despite an expected job boost as the U.S. hosts a highly successful record-breaking Football World Cup.

Although the headline unemployment rate dipped to 4.2%, this improvement was largely cosmetic: the labour force participation rate fell to 61.5%, its lowest level since March 2021, meaning fewer people were counted as actively seeking work.

Beneath the surface, the household survey painted a more troubling picture. Employment dropped sharply, with 507,000 fewer people reporting they were at work, and revisions to earlier months erased 74,000 previously reported jobs — undercutting the narrative of springtime strength.

Leisure and hospitality suffered a notable setback, shedding 61,000 positions, while gains were concentrated in a narrow band of sectors: professional and business services (+36,000), social assistance (+25,000), and healthcare (+22,000).

Financial markets reacted cautiously, with investors trimming expectations of a Federal Reserve rate rise in September 2026.

Overall, the data reportedly suggests a labour market losing steam, shaped more by statistical quirks and workforce exits than by genuine economic resilience.

The Ed Miliband energy paradox: how Britain ended up paying France to take its power

UK energy paradox

If you are anything like me, you’re not wrong to feel that this is insane. On the face of it, Britain has:

  • Among the highest electricity prices in the developed world, especially for industry.
  • Growing periods of negative wholesale prices, where generators pay others to take power.

That combination is not just a glitch; it’s the product of how the UK has chosen to do net zero—through a tangle of subsidies, rigid contracts and a grid that was never upgraded to match the political ambition.

This is the Ed Miliband paradox: a “cheap renewables” story that somehow delivers some of the world’s most expensive power, and then occasionally becomes so oversupplied that we literally pay France and others to take it away.

What is actually happening when prices go negative?

Negative prices are not a metaphor. For several dozen hours already this year, the wholesale price of electricity in Britain has dropped below zero.

Generators effectively pay the system to keep running, and interconnectors export that surplus to countries like France, Holland and Belgium—sometimes with a “chunky payment” attached.

This happens when:

  • Supply massively exceeds demand—typically on windy, sunny, mild days when heating and cooling demand is low.
  • Certain generators cannot or will not switch off—because of technical constraints (nuclear, some gas) or because their subsidy contracts reward them for generating regardless of price.
  • The grid cannot move or store the surplus—limited storage, constrained transmission, and slow grid reinforcement mean power piles up in the wrong place at the wrong time.

In that moment, electricity stops being a valuable commodity and becomes a waste product that must be disposed of. Interconnectors to France and others are the “sewer pipe” for that surplus.

Why the UK is uniquely bad at this

Negative prices are not just a British phenomenon—Germany, Spain, the Netherlands and others have also seen record hours of sub‑zero prices as renewables surge. But the UK has managed to combine:

  • High average prices, especially for industry;
  • Frequent negative prices at the margin;
  • Huge policy costs loaded onto bills rather than general taxation.

That cocktail is the result of several design choices.

1. Subsidy structures that pay to generate, not to be useful

A big chunk of UK renewables is supported by:

In a negative price event, the market is screaming “stop generating”. But if your contract still pays you based on output, you have every incentive to keep going. The cost of paying someone else to take the power can be less than the subsidy you’d lose by switching off.

So the system ends up doing something perverse: it pays generators to keep producing power that nobody wants, and then pays other countries to take it away.

2. A grid built for yesterday, not for a renewables surge

The UK has poured money into generation capacity—offshore wind, solar, interconnectors—but has been slow, bureaucratic and under‑invested on:

  • Transmission upgrades—moving power from windy Scotland and the North Sea to demand centres in England.
  • Storage—batteries, pumped hydro, demand‑side response at scale.
  • Flexible backup—fast‑ramping gas, smart tariffs, and industrial load‑shifting.

When you bolt a 21st‑century renewables fleet onto a 20th‑century grid, you get congestion, curtailment and waste.

The system then has to pay wind farms not to generate in some regions, while importing power elsewhere. Negative prices are just the most visible symptom of that mismatch.

3. Political obsession with “headline capacity” over system design

Net zero politics has been sold as a race to headline numbers:

  • X gigawatts of offshore wind by year Y
  • Z per cent of power from renewables
  • “Clean power by 2030”

What has not been sold—or properly designed—is the system architecture that makes that capacity economically coherent: locational pricing, flexible demand, storage, and a planning regime that can actually deliver grid reinforcement on time.

Ed Miliband’s own Electricity Market Review explicitly rejected zonal pricing in favour of a reformed national price, arguing that a single price is “fairest” and better for investment. That sounds nice politically, but it hides the real cost of congestion and mis‑location.

Instead of prices signalling “don’t build another wind farm here until the grid is upgraded”, the system socialises the pain across everyone’s bills.

Why are we paying France?

Interconnectors are not inherently stupid. In a rational system, they:

  • Smooth out volatility—import when you’re short, export when you’re long.
  • Share capacity—you don’t need to build as much domestic backup if you can lean on neighbours.

The problem is that the UK has created a structure where:

  • We over‑generate at certain times because of rigid contracts and inflexible plant.
  • We lack storage and flexible demand to soak up that surplus domestically.
  • We then use interconnectors as a dumping ground, paying others to take power that our own consumers have already funded through subsidies and levies.

France, with its large nuclear fleet and different cost structure, can happily take that cheap or even “paid‑to-take” power, displacing its own generation and lowering its average costs.

Meanwhile, UK industry is paying power prices around 60 per cent higher than in France on average.

So, we (the UK) socialise the cost of building and subsidising the capacity, then export the benefit at a discount.

How did this policy architecture even get created?

This isn’t one bad decision; it’s a stack of incentives and political choices that line up in the worst possible way.

1. Short‑term politics, long‑term contracts

Governments of all colours wanted:

  • Quick, visible progress on renewables.
  • Private capital to fund it, not the state balance sheet.
  • Minimal upfront tax rises.

The answer was long‑term, legally binding contracts (RO, CfDs, capacity market) that shifted risk onto consumers via bills. Once signed, these contracts are hard to change without spooking investors or triggering compensation claims.

So ministers get the photo‑ops—“world‑leading offshore wind”, “clean power by 2030”—while the structural costs and distortions are baked in for decades.

2. Ideological framing: net zero as a moral crusade, not an engineering project

Net zero has been framed as a moral imperative first, an engineering challenge second. That has consequences:

  • Questioning the design is painted as questioning the goal.
  • Complex system trade‑offs are reduced to slogans about “cheap renewables” and “green jobs”.
  • Uncomfortable truths—like the need for gas backup, storage, and grid reform—are pushed into the technical long grass.

The result is a policy environment where it is easier to announce another offshore wind auction than to confront the messy, expensive business of rewiring the grid and redesigning market signals.

3. Regulatory fragmentation and institutional cowardice

Ofgem, National Grid ESO, the Department for Energy Security and Net Zero, the Treasury—each has a slice of the problem, but no one owns the whole system outcome.

  • Ofgem focuses on consumer protection and network costs, often slowing investment.
  • Treasury resists big upfront public spending on grid and storage, preferring “market‑based” fixes.
  • Ministers chase announcements that look good in manifestos.

No one is politically rewarded for saying: “We need to spend billions on grid reinforcement and storage now, or we’ll be paying France to take our power in five years.” So it doesn’t happen at the necessary scale.

Is this fixable, or are we stuck paying others to take our power?

It is fixable—but not with more of the same.

An honest, grown‑up approach would mean:

  • Rewriting incentives so generators are paid for being useful to the system, not just for raw output. That means tighter rules on when subsidies are paid during negative prices, and contracts that reward flexibility.
  • Accelerating grid and storage investment as national infrastructure, not an afterthought. That likely means more state involvement and faster planning, not just hoping private investors will do it.
  • Introducing stronger locational signals—whether full zonal pricing or something close to it—so that the cost of building in the wrong place is visible, not smeared across everyone’s bills.
  • Using interconnectors intelligently, not as a dumping ground: export surplus when it’s genuinely cheap, but don’t subsidise over‑generation just to keep contracts happy.

So how stupid is this policy?

On a technical level, the engineers keeping the lights on are doing miracles with the system they’ve been given. The stupidity sits higher up:

  • Designing a net zero pathway around rigid subsidies and under‑built infrastructure.
  • Refusing to confront the trade‑offs, then acting surprised when the physics bites back.
  • Allowing a political narrative of “cheap green power” to coexist with some of the highest industrial prices in the world and growing episodes of negative pricing.

The real scandal isn’t just that we pay France to take our power. It’s that British households and firms have already paid once—through levies and high tariffs—to build that surplus, and then pay again when the system has to bribe someone else to use it.

Work that one out…!

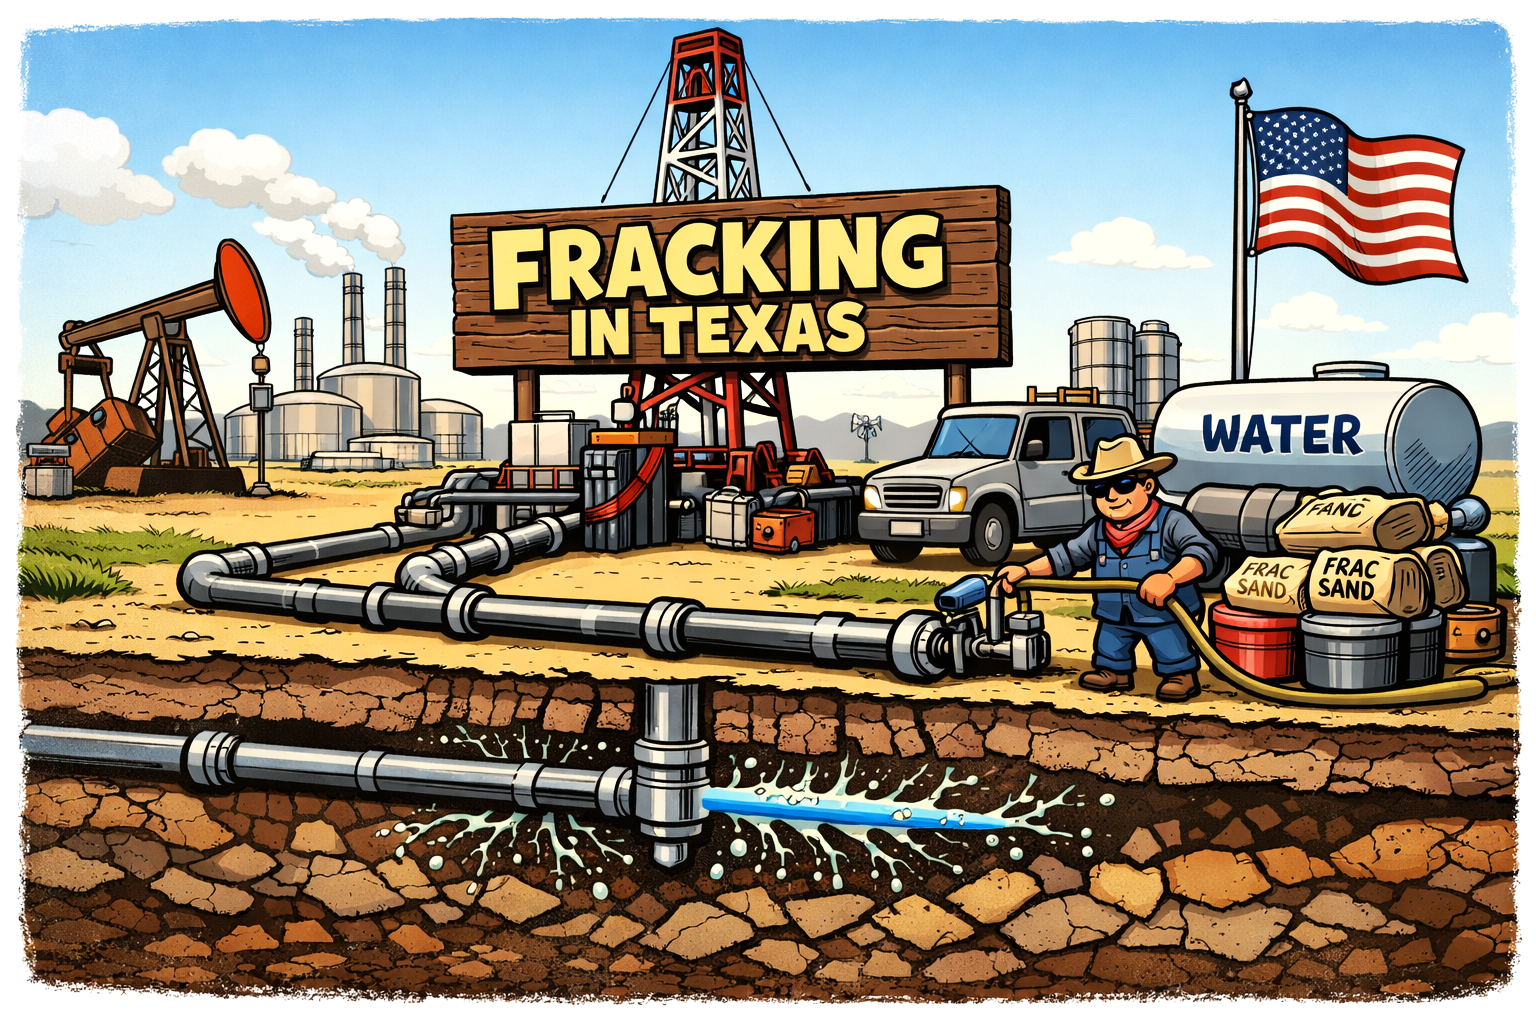
Fracking – Oil Exports – and the U.S. Oil Success

Fracking - Oil Exports - and the U.S. Oil Success

One of the least‑discussed forces helping to shape the current U.S.–Iran confrontation is the quiet revolution beneath American soil.

Over the past decade, hydraulic fracturing transformed the United States from a vulnerable energy importer into the world’s largest oil and gas producer.

Pumped up

Nowhere has this shift been more dramatic than in Texas, where the Permian Basin alone pumps more oil than many OPEC members. This surge has not only reshaped global markets — it has altered Washington’s strategic outlook.

The United States now exports record volumes of crude oil and liquefied natural gas, with outbound shipments regularly exceeding 4 million barrels per day.

The conflict with Iran isn’t impacting oil production in the U.S.—if anything, it has boosted output and increased overseas sales.

This would have been unthinkable twenty years ago, when U.S. foreign policy was constrained by dependence on Middle Eastern supply.

U.S. Shale Boom

Today, the shale boom has given Washington a buffer: even severe disruption in the Strait of Hormuz would no longer threaten the U.S. economy in the way it once did.

This energy independence has had political consequences. Analysts note that President Trump’s willingness to escalate against Iran — including strikes, sanctions, and naval deployments — is partly rooted in the belief that the U.S. can withstand an oil shock far better than its rivals.

Iran, by contrast, relies heavily on oil revenues and is already weakened by sanctions. A prolonged disruption to its exports hurts Tehran far more than Washington.

Texas fracking plays directly into this dynamic. The combination of horizontal drilling, high‑pressure fracturing, and vast shale formations has created a production engine capable of rapid growth.

When global prices rise, U.S. shale responds within months, softening the blow to consumers and limiting the geopolitical leverage of traditional producers.

Texas Asset

In effect, the Permian Basin has become a strategic asset — a domestic shock absorber that reduces the economic risks of confrontation abroad.

Critics argue that this new confidence borders on complacency. A major conflict in the Gulf would still send global prices sharply higher, with knock‑on effects for inflation, supply chains, and allied economies.

But there is no doubt that the fracking boom has changed the psychology of U.S. power. For the first time in modern history, America can contemplate a showdown in the Middle East without fearing an immediate energy crisis at home.

Texas may not be the reason the U.S. is confronting Iran — but it has certainly made the White House feel far safer doing so.

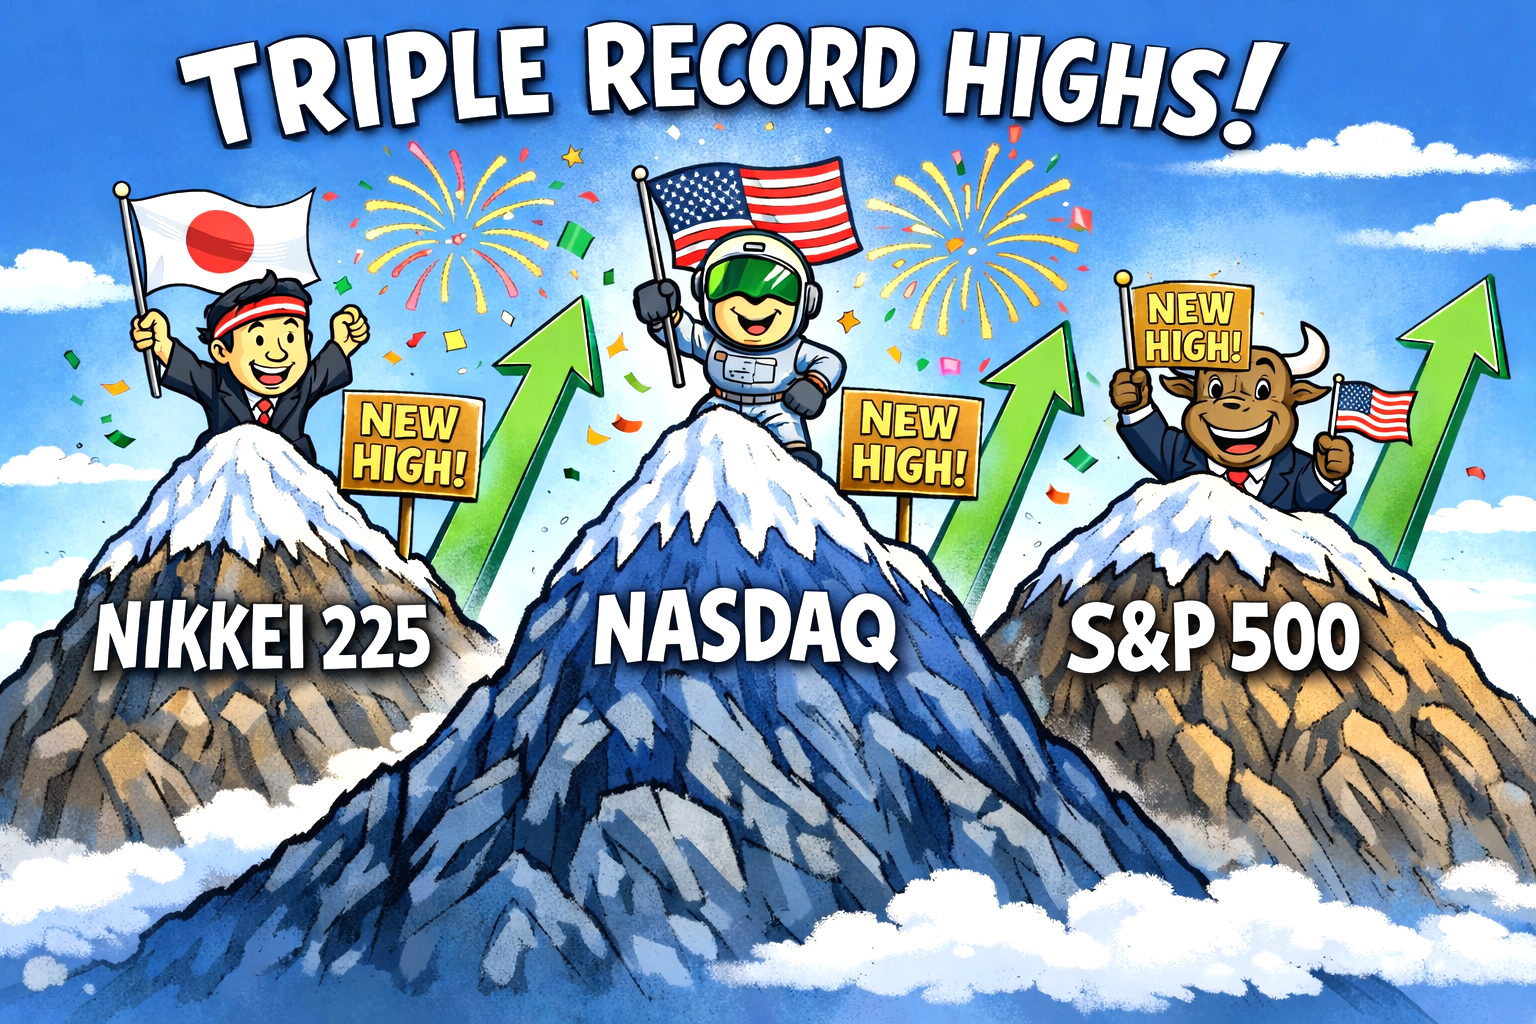
Nothing to see here… Nasdaq – S&P 500 and Nikkei 225 each break all-time record highs and set new intraday highs… again!

Indices at new record highs!

Global equity markets delivered a remarkable synchronised milestone on Friday, as the Nikkei 225, Nasdaq Composite, and S&P 500 each registered fresh all‑time highs, underscoring the strength of the ongoing technology‑led rally and a renewed wave of risk appetite.

Nikkei

In Tokyo, the Nikkei 225 briefly surged to a record intraday high of 63,385.04, propelled by powerful follow‑through from Thursday’s post‑holiday catch‑up rally. Although the index later eased into modest profit‑taking, it still finished at 62,713.65, comfortably within record territory.

AI here we go!

Semiconductor and AI‑linked names continued to dominate flows, reflecting Japan’s deep integration into the global chip supply chain.

Nasdaq

Across the Pacific, Wall Street delivered a similarly emphatic performance. The Nasdaq Composite pushed to a new intraday peak of 26,248.62 before closing at 26,247.08, its highest level on record.

Strong earnings from major technology firms, combined with renewed optimism around US–Iran de‑escalation efforts, helped extend the index’s multi‑week winning streak.

S&P 500

The S&P 500 also broke new ground, touching an intraday high of 7,401.50 and settling at a record close of 7,398.93.

Each indices continued to hit even higher intraday records after the bell on Friday 8th May 2026.

A stronger‑than‑expected US jobs report reinforced confidence in the resilience of the American economy, even as geopolitical tensions and elevated energy prices continue to shape market sentiment.

Tech cycle

Taken together, the simultaneous records across the U.S. and Japan highlight the dominance of the global technology cycle and the market’s willingness to look through near‑term macro risks.

For now, momentum remains firmly on the side of the bulls. Nothing appears to be able to knock this bull off course.

Tokyo Takes Off: Nikkei Rockets to Record Heights

Nikkei record above 62,000

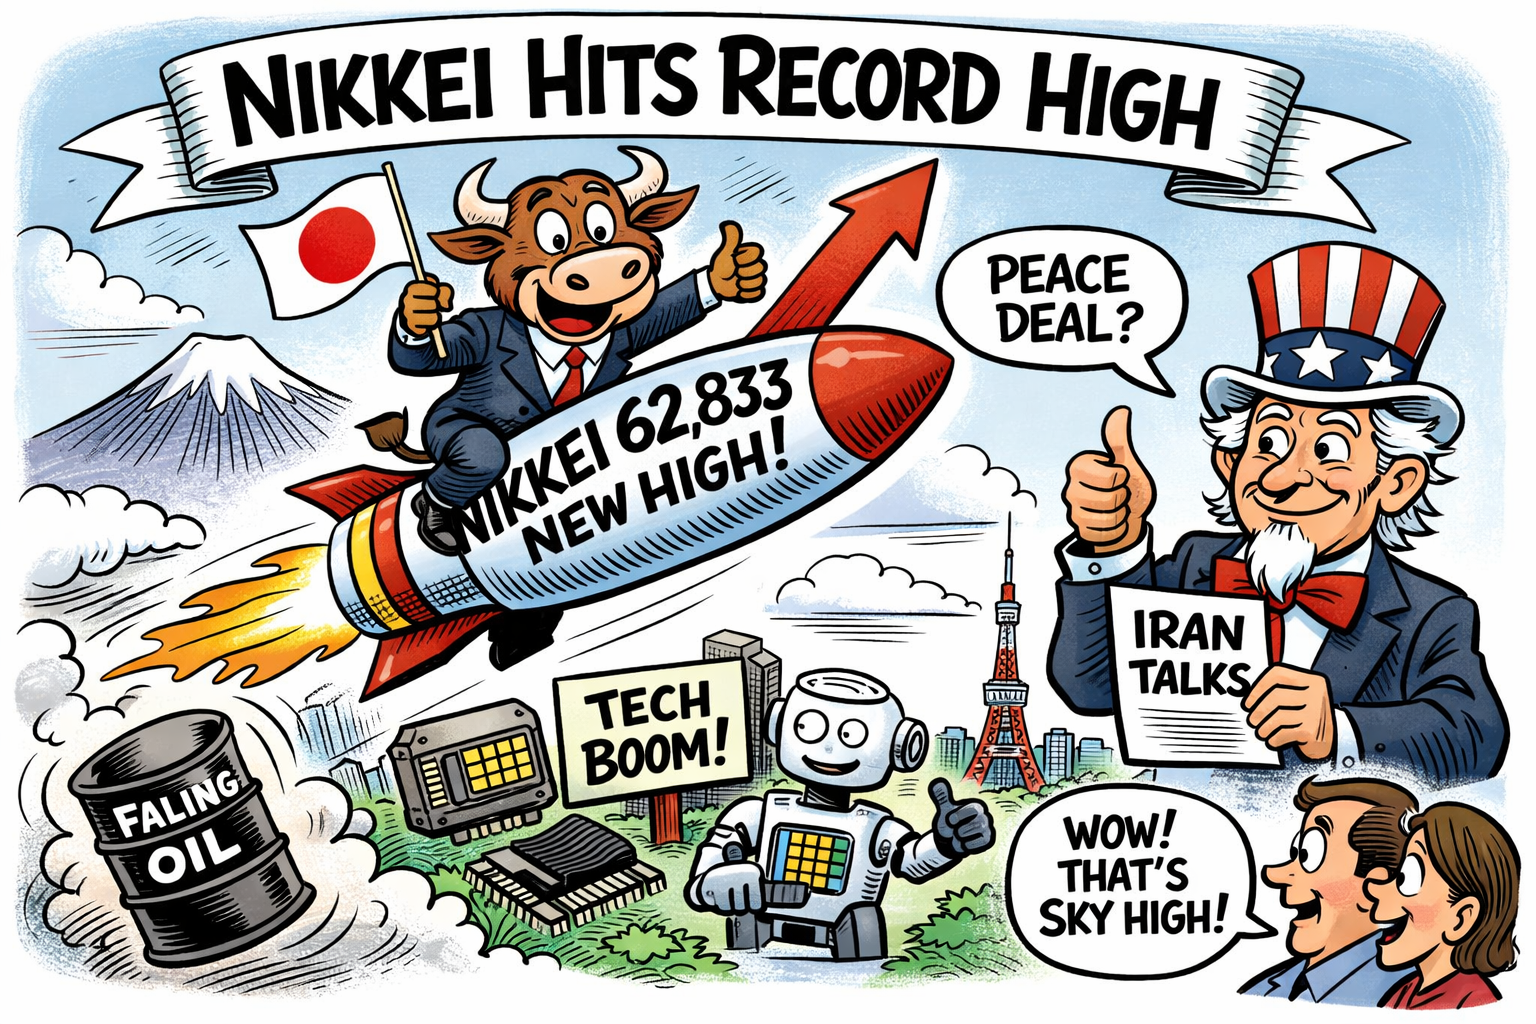
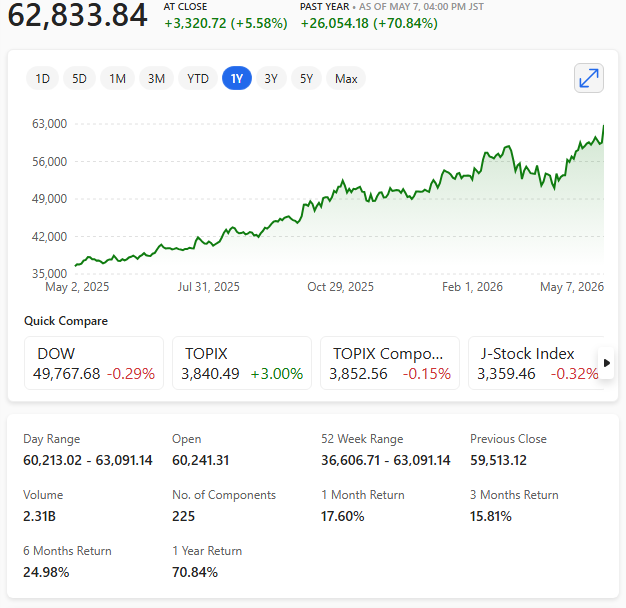
The Nikkei 225 surged to a fresh all‑time high yesterday, closing at 62,833.84, driven by a powerful combination of easing geopolitical risk, a global tech rally, and a sharp drop in oil prices.

Exceptional day

The Nikkei’s latest record marks one of the most dramatic single‑day advances in its modern history. The index jumped 3,320.72 points, a 5.58% gain, smashing its previous closing high and briefly topping 63,000 intraday.

This explosive move came as Tokyo reopened after the Golden Week holiday, allowing Japanese equities to catch up with global markets that had rallied earlier in the week.

Easing fears

A decisive catalyst was renewed optimism over a potential U.S.–Iran agreement, which eased fears of prolonged conflict and helped unwind the war‑risk premium that had weighed on markets.

Reports suggesting progress in negotiations pushed crude oil sharply lower, with U.S. WTI futures dropping more than 13% at one point.

Nikkei 225

Nikkei 225 at all-time high 7th May 2026

Lower energy prices provided immediate relief for Japan’s import‑dependent economy and boosted investor sentiment across sectors.

AI led rally

The rally was led by semiconductor and AI‑linked stocks, which have been the backbone of Japan’s market strength throughout the year. Companies such as SoftBank and major chip‑equipment makers saw outsized gains as Wall Street’s tech surge spilled over into Asia.

While analysts expect the domestic market to remain firm in the near term, they also caution that geopolitical conditions remain a major concern.

For now, however, the Nikkei’s latest milestone underscores Japan’s position as one of the strongest major equity markets of 2026.

Euro zone inflation jumps to 3% as economic growth almost stalls

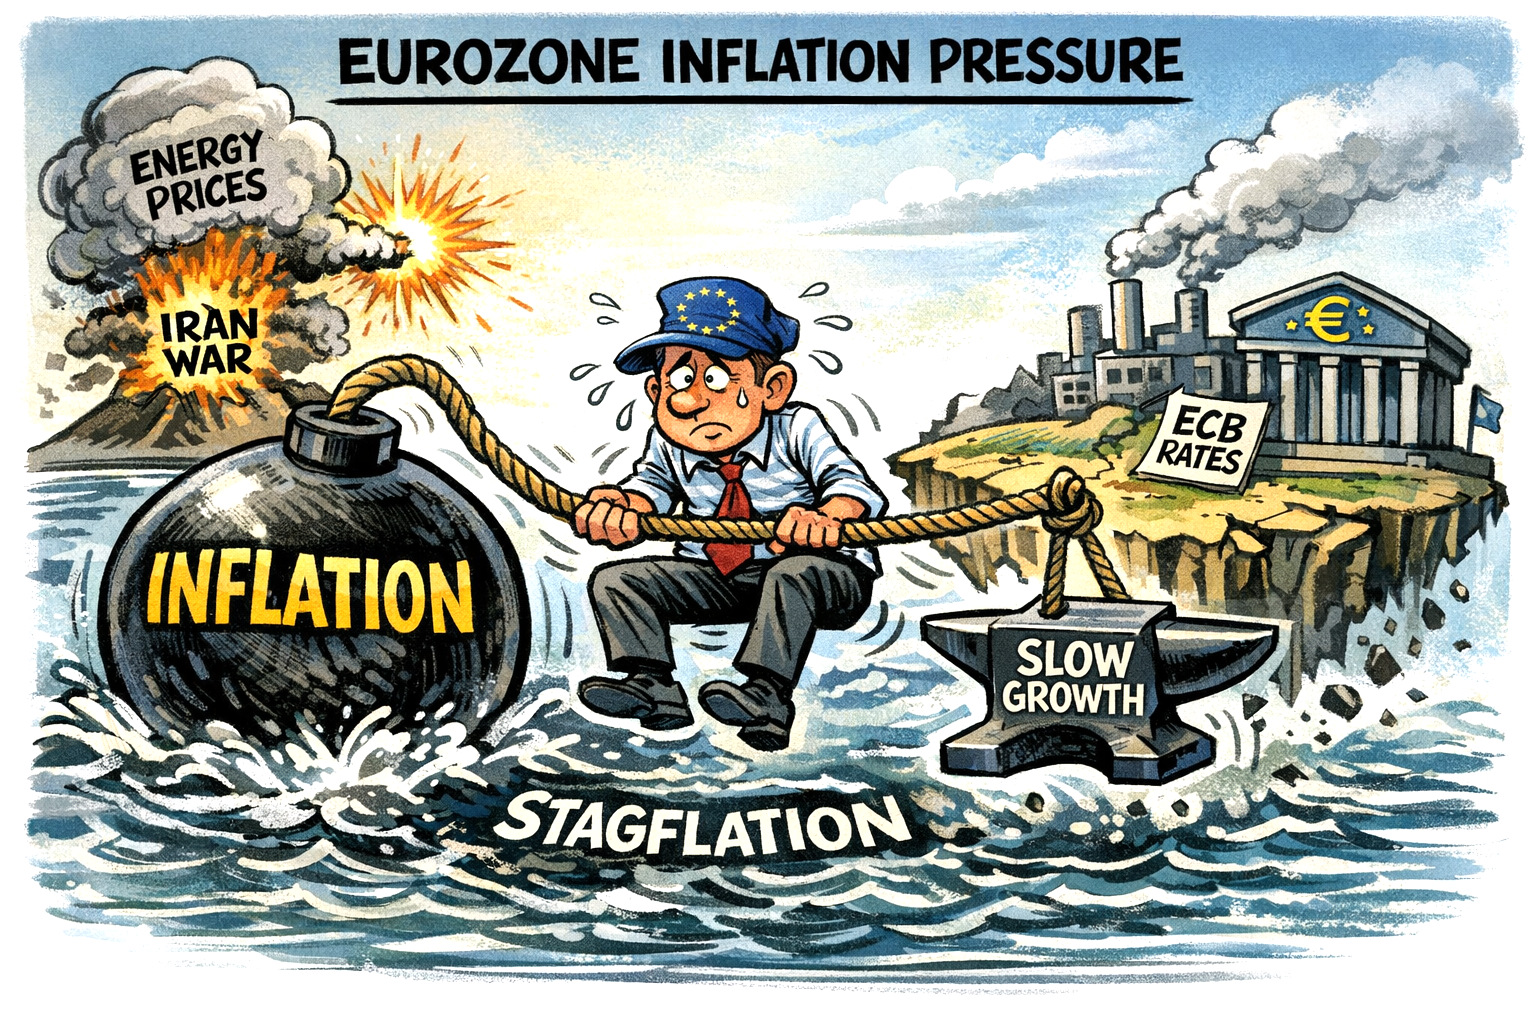
Euro Zone Inflation Pressure April 2026

Euro zone inflation accelerated sharply in April 2026, rising to 3%, as the bloc’s economy barely grew — a combination that deepens fears of a stagflationary year.

The latest flash estimate from Eurostat shows headline inflation climbing from 2.6% in March, driven overwhelmingly by surging energy costs linked to the U.S./Iran war and the ongoing disruption in the Strait of Hormuz.

Energy

Energy inflation jumped to 10.9%, more than double the previous month’s rate, underscoring how exposed the currency bloc remains to external supply shocks.

Core inflation, however, edged down to 2.2%, offering a small reassurance that second‑round effects — wage‑price spirals — have not yet taken hold.

Growth was anaemic. First‑quarter GDP expanded by just 0.1%, reflecting weak industrial output, fragile consumer confidence, and higher input costs for businesses.

Stagnation

Economists warn that the combination of rising prices and near‑stagnant activity risks pushing the region into a period of low‑growth, high‑inflation pressure.

The figures land just ahead of the European Central Bank’s policy meeting. With inflation above target but growth faltering, the ECB faces a difficult balancing act.

Policymakers are widely expected to hold rates at 2%, wary that tightening into a supply‑driven shock could deepen the slowdown.

For now, the data reinforce a picture of a euro zone squeezed by global energy turmoil and struggling to regain momentum.

Are markets becoming complacent about the U.S. Iran war?

U.S. Iran war effect underestimated?

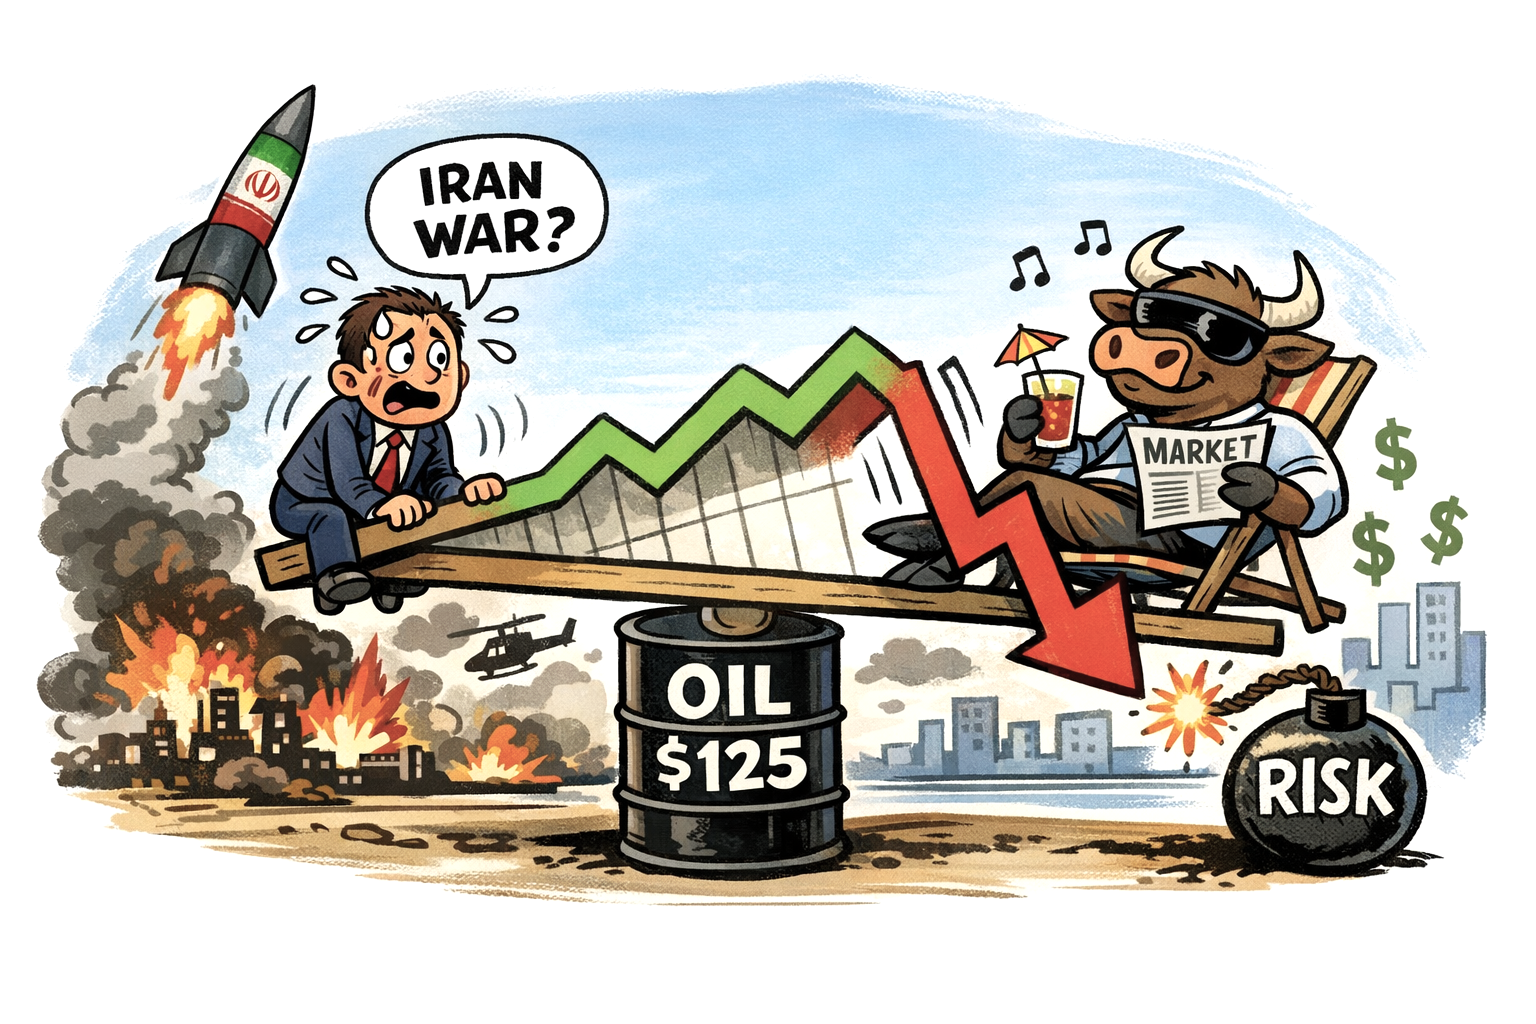
Markets are flashing warning signs that too many investors are still treating the U.S.-Iran war as a temporary disturbance rather than a structural shock.

Brent crude’s brief surge to around $125 a barrel — its highest level in four years — has reignited fears that the conflict’s economic fallout is being dangerously underpriced.

Complacency

Analysts argue that markets are behaving as though a clean resolution is imminent, even as evidence points in the opposite direction.

The core concern is complacency. Oil’s extreme pricing — where near‑term contracts trade at a steep premium to longer‑dated ones — shows traders are still assuming the Strait of Hormuz will reopen soon and that supply chains will normalise.

Yet millions of barrels per day remain blocked, inventories of refined products like diesel and jet fuel are sliding toward crisis levels, and the White House is reportedly weighing further military action.

None of that aligns with the market’s pricing of a quick return to stability.

The disconnect

This disconnect matters because the real economic damage has not yet fully surfaced. As one investment chief notes, the macro impact will “come back into stark focus” if oil stays elevated.

Higher energy costs feed directly into inflation, squeeze corporate margins, and erode consumer spending power. Equity markets have so far shown resilience, but that resilience is built on the assumption that the shock is temporary.

If the conflict drags into far into May 2026 — as several analysts expect — the stagflationary risk becomes harder to ignore.

Stress

The refined products market is already behaving like a stress test. Diesel prices have nearly doubled, and traders warn that refineries will soon be able to “charge whatever they want”.

Even a peace deal would not deliver instant relief: shipping logistics, sanctions decisions, and depleted reserves would take weeks to unwind.

The fear among seasoned investors is simple: markets are pricing for peace while the fundamentals are still pricing for war. Before long, that gap may close — abruptly and painfully.

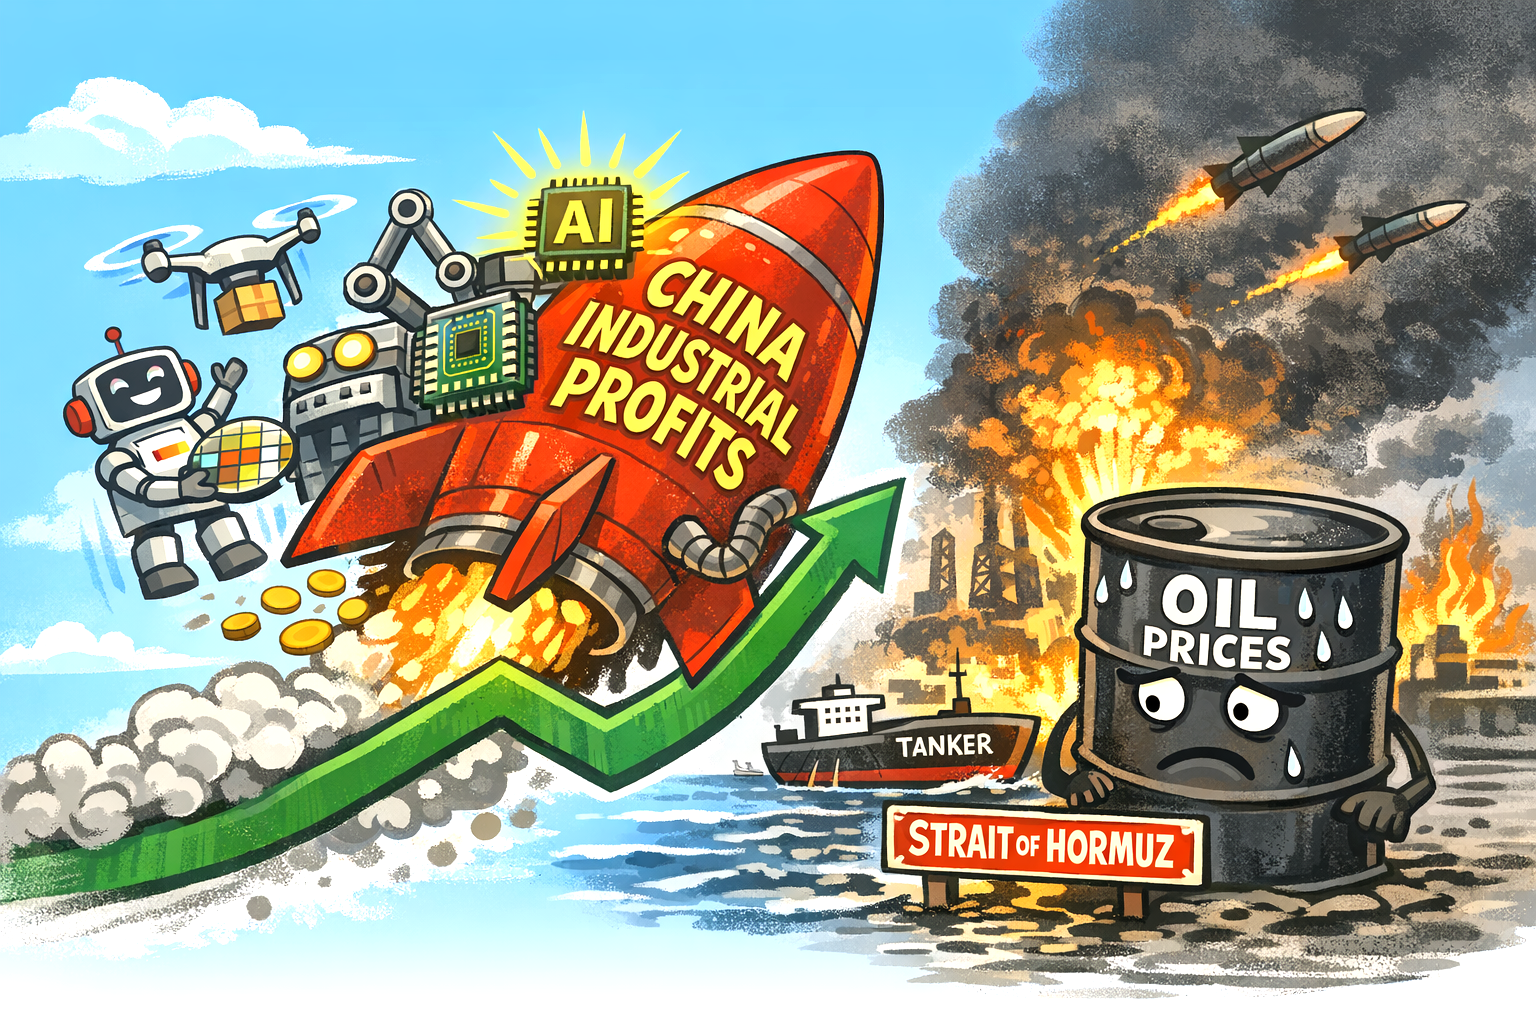
China’s Industrial Profits Surge as AI and Chipmakers Power a High‑Tech Rebound

China manufacturers excel

China’s industrial sector delivered its strongest performance in more than half a decade in March 2026, with profits jumping 15.8% year‑on‑year, signalling a decisive shift in the country’s growth engine towards advanced manufacturing and AI‑related hardware.

The latest figures from the National Bureau of Statistics show first‑quarter profits rising 15.5%, marking the best opening to a year since 2017 outside the pandemic distortions.

The surge is highly concentrated. Traditional heavy industry remains subdued, but China’s high‑tech and equipment manufacturers are now carrying the industrial economy.

Tech manufacturing

Profits in high‑tech manufacturing soared 47.4%, while equipment makers posted a 21% rise. Beneath those aggregates lie extraordinary gains: optical fibre producers saw profits climb more than 300%, with optoelectronics and display‑device manufacturers also recording double‑digit increases.

These sectors sit at the heart of China’s AI infrastructure build‑out, from data‑centre components to semiconductor‑adjacent hardware.

Demand for “intelligent products” is also reshaping the landscape. Drone manufacturers reported profit growth above 50%, reflecting both civilian and dual‑use demand as China accelerates its push into autonomous systems and robotics.

This momentum comes despite a sharp rise in global oil prices following renewed tensions in the Middle East. Brent crude briefly topped $108 a barrel, raising concerns about margin pressure.

Partially insulated

Yet China appears partially insulated: a coal‑heavy energy mix, access to discounted Iranian crude and sizeable onshore inventories have softened the immediate impact.

Even so, analysts warn that a prolonged oil shock, tighter sanctions enforcement or disruption around the Strait of Hormuz could still weigh on costs later in the year.

China’s industrial profits are no longer being driven by property‑linked sectors or commodity cycles, but by the country’s accelerating investment in chips, AI hardware and advanced manufacturing — a structural shift that is beginning to reshape the contours of its economic recovery.