Bank of England Raises Interest Rates to 4%

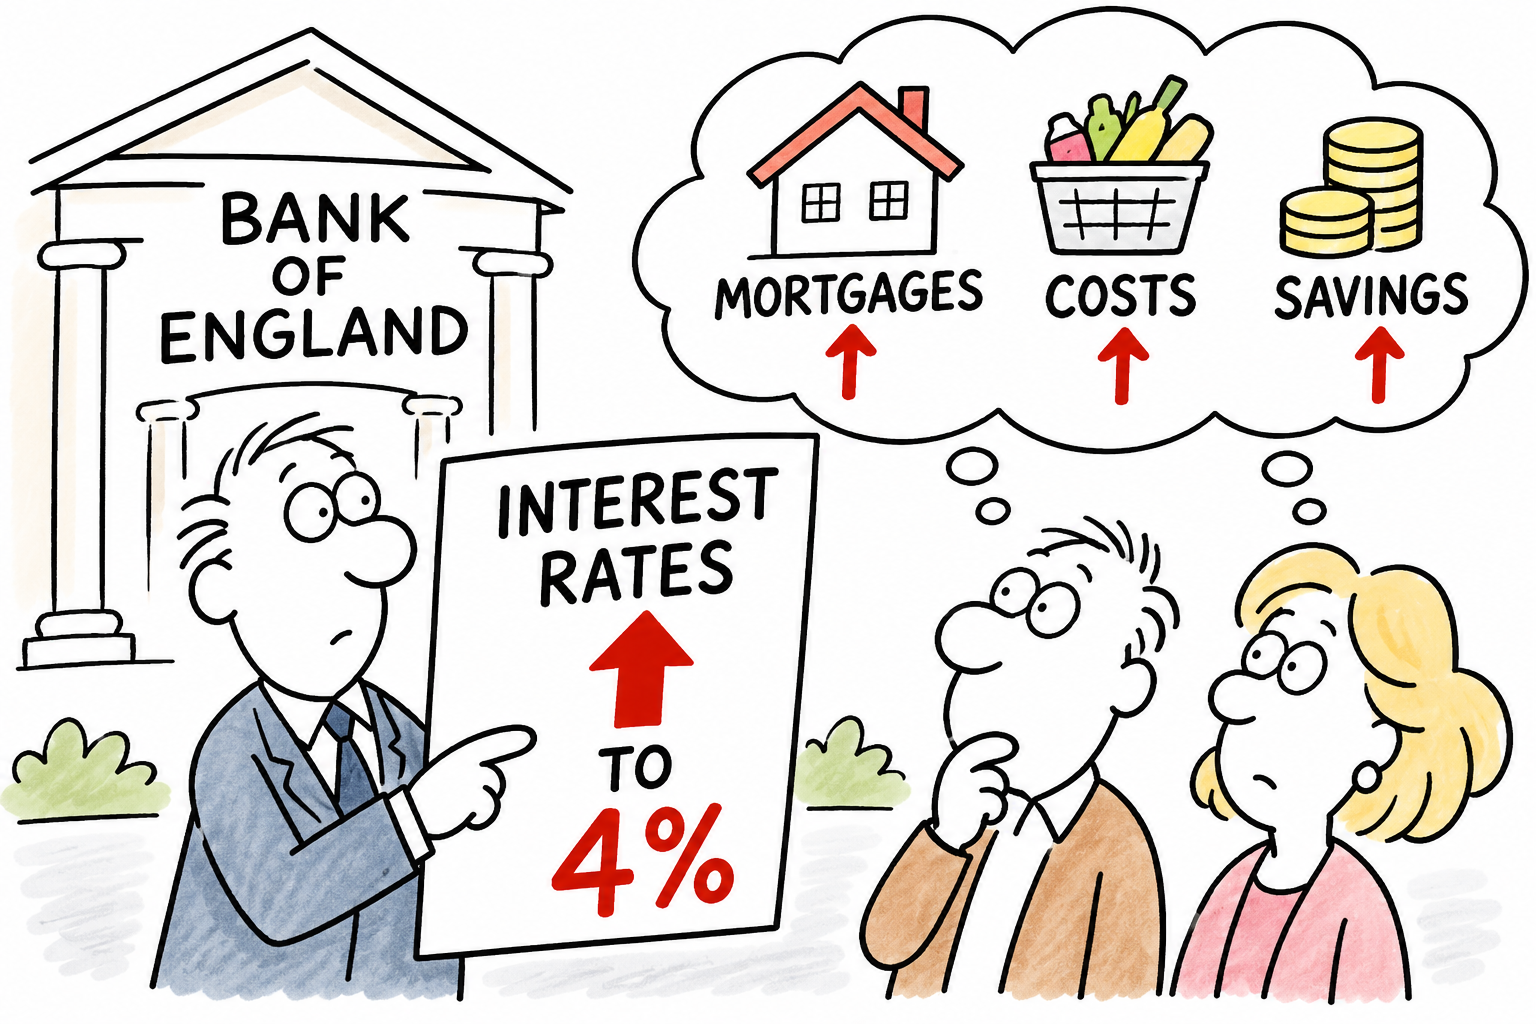
Graph showing the Bank of England's interest rate increase to 4% as of November 2026, with trends in previous rates indicated.

The Bank of England has raised interest rates for the first time in more than three years, increasing the base rate from 3.75% to 4% in a move aimed at tackling renewed inflationary pressures.

The decision, announced on Thursday 5th November 2026, followed growing concerns over rising energy prices, fuelled by the continuing conflict in the Middle East. and of the Russia-Ukraine war.

UK inflation reached 3.5% in September 2026, and the Bank now expects it could approach 5% by the middle of 2027.

Vote

The Monetary Policy Committee voted 8–1 in favour of a quarter-point increase, although one member wanted a larger rise to 4.25%.

Higher interest rates will increase borrowing costs for mortgage holders and businesses, while potentially offering better returns for savers.

The Bank has warned that further increases remain possible if energy prices continue to drive inflation higher.

The decision highlights the difficult balancing act facing policymakers: controlling inflation without damaging an already fragile economy.

Australia Raises Interest Rates to an 18-Year High as Inflation Persists

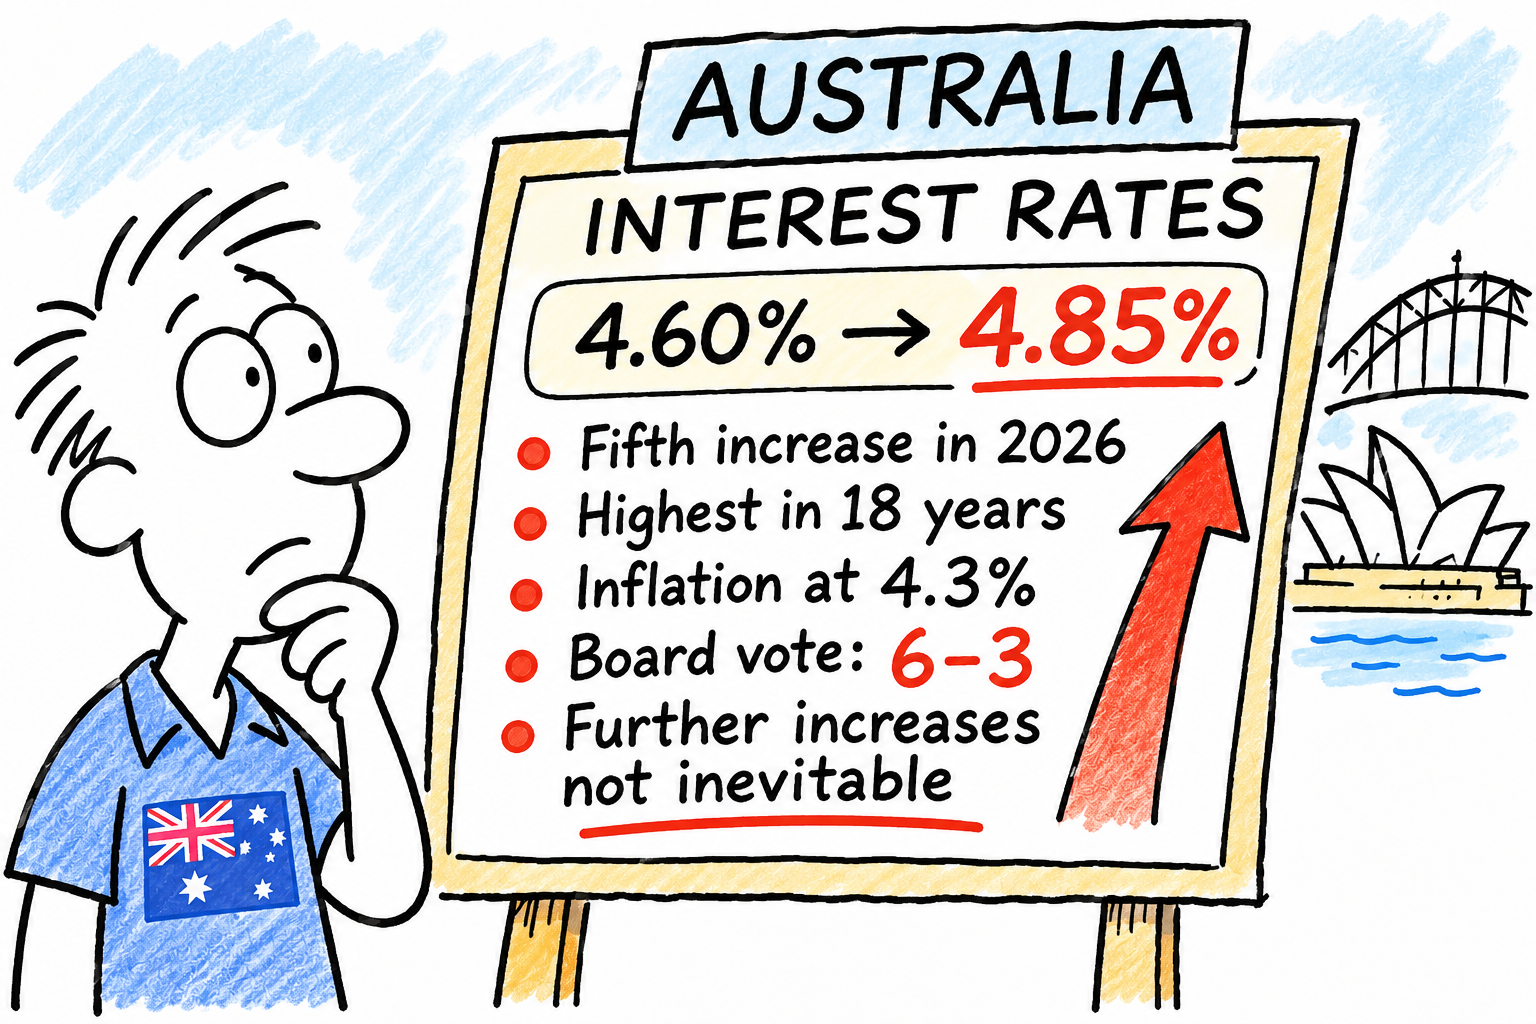
Graph showing Australia's central bank interest rate increases reaching an 18-year high amid persistent inflation pressures.

Australia has raised interest rates to their highest level in 18 years as the central bank steps up efforts to bring stubborn inflation under control.

The Reserve Bank of Australia (RBA) increased its cash rate from 4.60% to 4.85%, marking its fifth increase in 2026.

Inflation at 4.3%

Annual inflation reached 4.3% in September 2026, highlighting the difficulties policymakers face in bringing price pressures under control.

The decision was not unanimous, with six members of the nine-person board voting for an increase and three preferring to leave rates unchanged.

Pressure

The latest move will add further pressure to households already struggling with higher mortgage repayments and rising living costs.

Higher borrowing costs are intended to discourage spending, reduce demand and eventually ease inflation.

However, the RBA faces a delicate balancing act, as excessive tightening risks weakening economic activity and pushing the country towards a downturn.

Persistant issue

The decision also highlights a wider problem facing central banks worldwide. Despite previous monetary tightening, inflation has proved more persistent than policymakers had anticipated.

The RBA has indicated that further increases are not inevitable, suggesting it may be approaching the limits of how far it can tighten monetary policy without damaging growth.

For investors, the message is clear: the global interest-rate cycle may not be moving uniformly towards cheaper borrowing.

Inflation remains a stubborn obstacle, and higher interest rates could persist for longer than markets had hoped.

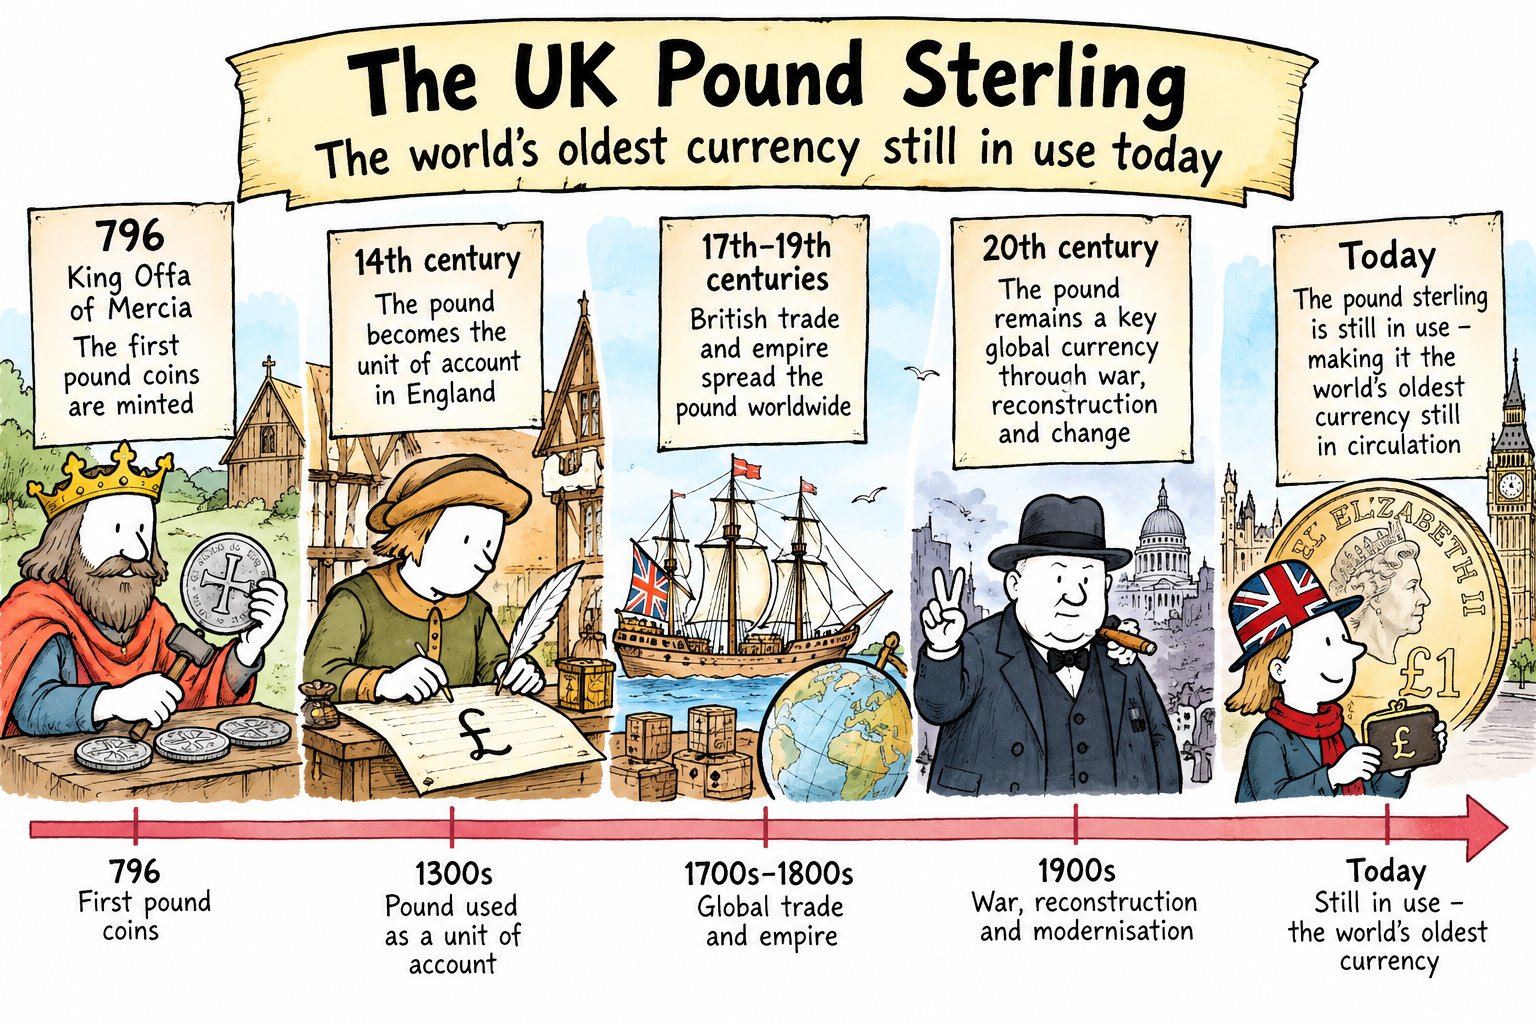
The story of how the UK Pound Sterling began and remains the oldest currency still in use today

The English Pound

The British pound, or pound sterling, has one of the longest histories of any currency still in use today.

Its story can be traced back more than 1,200 years, to Anglo-Saxon England in the eighth century.

Pounds & Pennies

The word “pound” originally referred to a unit of weight rather than a particular coin. The early English monetary system was based on the silver penny, and 240 pennies were eventually regarded as equivalent to one pound of silver.

This helped establish the connection between the pound and the precious metal that gave sterling its value.

Silver

Silver pennies were introduced in England during the reign of King Offa of Mercia, around the late eighth century.

Offa’s reforms created a more organised monetary system, influenced partly by the coinage being used across Europe.

These small silver coins became the foundation of English currency for centuries.

Sterling

The word “sterling” has a less certain origin. One popular explanation is that it came from the Old Norman French term “esterlin”, associated with silver pennies of reliable quality. Another theory connects it with the “little star” symbols that appeared on some early coins.

Over the centuries, the pound changed considerably. Gold coins became increasingly important, particularly from the Tudor period onwards, while paper money eventually emerged in the form of banknotes.

Bank of England established in 1694

In 1694, the Bank of England was established, helping to develop a more sophisticated national banking system.

The pound has survived wars, political upheavals, financial crises and enormous changes in Britain itself.

Despite its ancient roots, sterling remains a major international currency — making it a remarkable link between medieval England and the modern financial world.

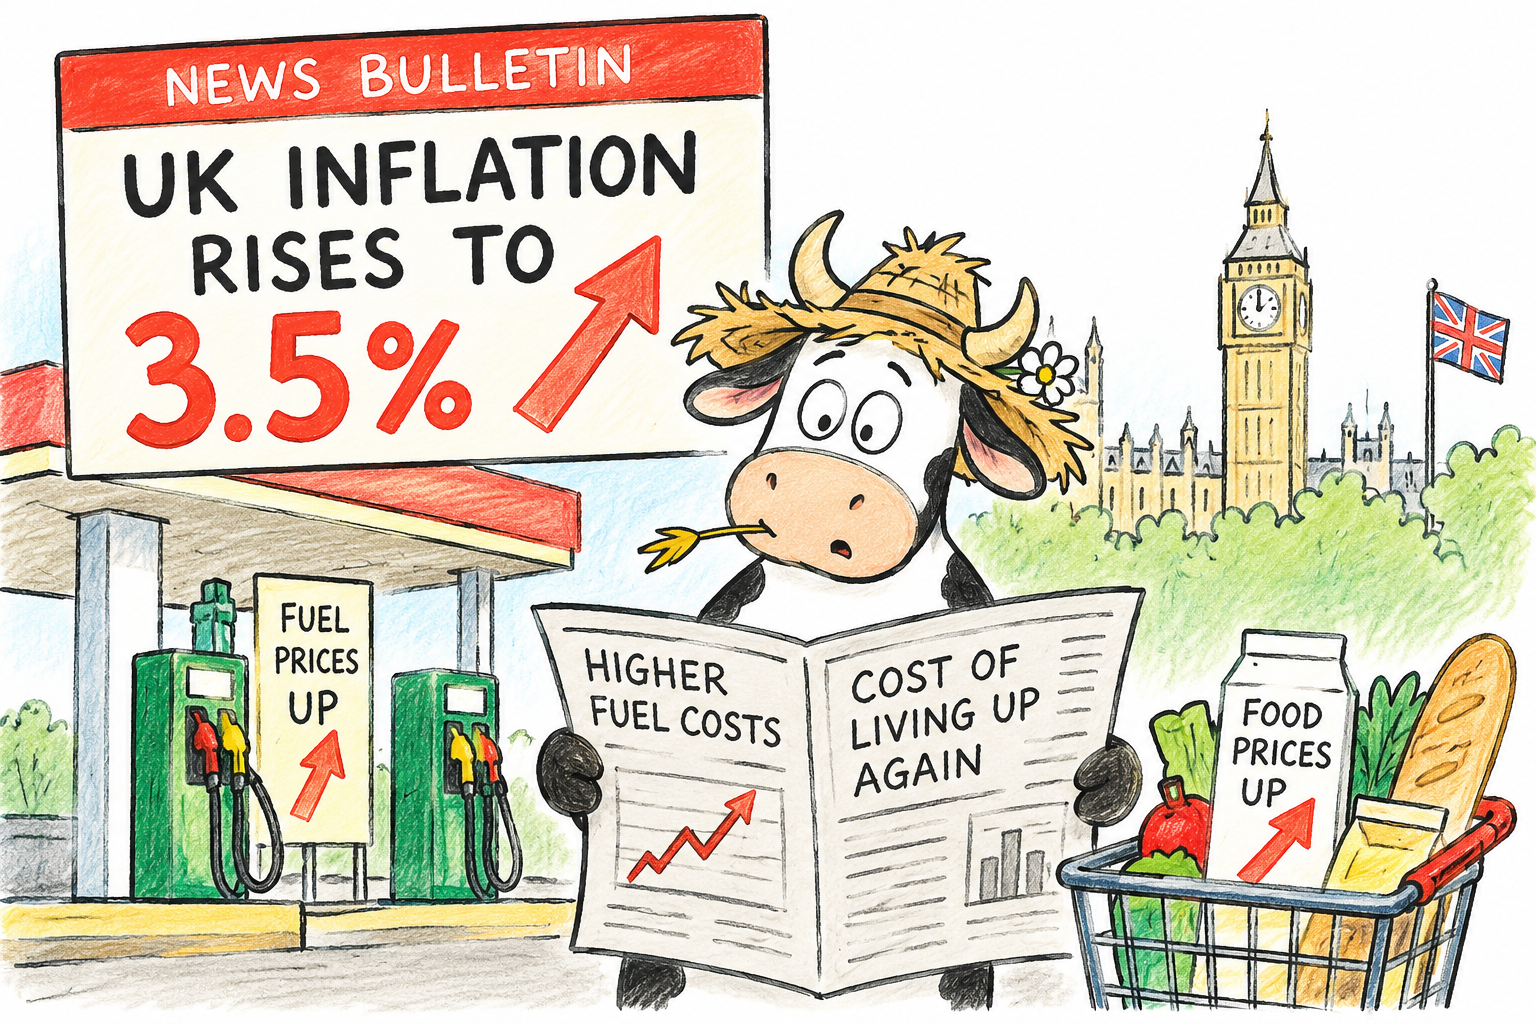
UK Inflation Surges to 3.5% as Fuel and Energy Costs Bite

UK inflation up!

UK inflation accelerated more sharply than expected in September 2026, raising fresh concerns about the cost of living and putting pressure on the Bank of England to reconsider its interest-rate outlook.

The Consumer Prices Index (CPI) rose by 3.5% in the year to September, up from 3.1% in August, according to figures released by the Office for National Statistics on Wednesday 21st October 2026.

Higher than expected

The increase exceeded economists’ expectations of 3.4% and was higher than the Bank of England’s previous forecast of 3.0%.

Rising petrol and diesel prices were the main drivers, reflecting higher global energy costs amid the ongoing conflict involving Iran.

The increase in fuel costs threatens to feed through into transport, deliveries and other business expenses, potentially pushing up prices elsewhere in the economy.

Core inflation

Underlying inflationary pressures also strengthened. Core CPI, which excludes energy, food, alcohol and tobacco, increased to 2.8% from 2.6%. Services inflation, closely watched by policymakers, climbed to 3.7% from 3.4%.

The figures complicate the outlook for interest rates. With UK inflation moving further away from the Bank’s 2% target, expectations of a possible rate increase in November 2026 may strengthen, although weaker economic growth could argue against tighter policy.

The latest data also arrives ahead of the government’s forthcoming Budget, intensifying pressure to address household spending pressures.

For financial markets, the combination of rising inflation and uncertainty over borrowing costs could prove uncomfortable for both government bonds and equities.

Global debt has reportedly surged to $365 trillion, prompting economists to warn about a looming ‘vicious cycle’

Debt and the beggar

The combination of record global debt, higher borrowing costs and growing doubts about the enormous sums being committed to artificial intelligence is creating a more complicated backdrop for financial markets.

Global debt exceeded $365 trillion in the first half of 2026, according to the Institute of International Finance, with debt now around 310% of global GDP.

China and the U.S. debt mountain

The increase was driven particularly by China and the United States. At the same time, higher interest rates are making refinancing increasingly expensive, creating the possibility of a vicious cycle in which governments and companies borrow more simply to service existing obligations.

This is particularly significant for the AI boom. The OECD says governments and companies are expected to borrow around $29 trillion from markets during 2026, while corporate borrowing is also rising as businesses finance major investment programmes, including AI infrastructure.

Michael Burry

Michael Burry, famous for anticipating the U.S. housing crisis, has added another warning sign.

He has recently reportedly increased bearish positions involving Micron, Palantir, Nebius and the semiconductor sector, arguing that parts of the AI and chip boom could be vulnerable if supply increases faster than demand.

The concern is not necessarily that AI will fail. Rather, enormous investment and borrowing require enormous future revenues to justify them.

If AI spending produces lower-than-expected returns, highly valued technology shares could face pressure at the same time as heavily indebted companies face rising financing costs.

Could this affect the stock market now?

The ingredients for greater volatility are certainly present. Higher bond yields, expensive energy, inflation pressures and debt-servicing costs can compete with equities for investors’ money.

Reuters recently reported that global borrowing costs and energy prices were already creating concerns about the potential impact on equities and credit markets.

Yet markets have so far remained remarkably resilient, with U.S. shares still close to record levels.

The danger, therefore, may not be debt alone, but…

debt + high valuations + expensive AI investment + higher interest rates.

If those pressures reinforce one another, the adjustment in markets could become considerably more significant.

Bank of England Holds Interest Rate at 3.75%

Bank of England holds rate

The Bank of England has held interest rates at 3.75% on 17th September 2026 but warned that persistently high energy costs could force rates higher.

The Monetary Policy Committee voted 6-3 to keep Bank Rate unchanged, while three members backed an increase to 4%.

Governor Andrew Bailey reportedly said the outlook remained uncertain, with rising energy prices creating renewed inflationary pressure.

UK inflation reached 3.1% in August 2026 and the Bank expects it to rise further, potentially exceeding 4% in early 2027 if energy costs remain elevated.

Bailey reportedly said that if the Middle East conflict persists and inflationary risks increase, monetary policy may need to tighten.

UK Inflation Rises to 3.1%

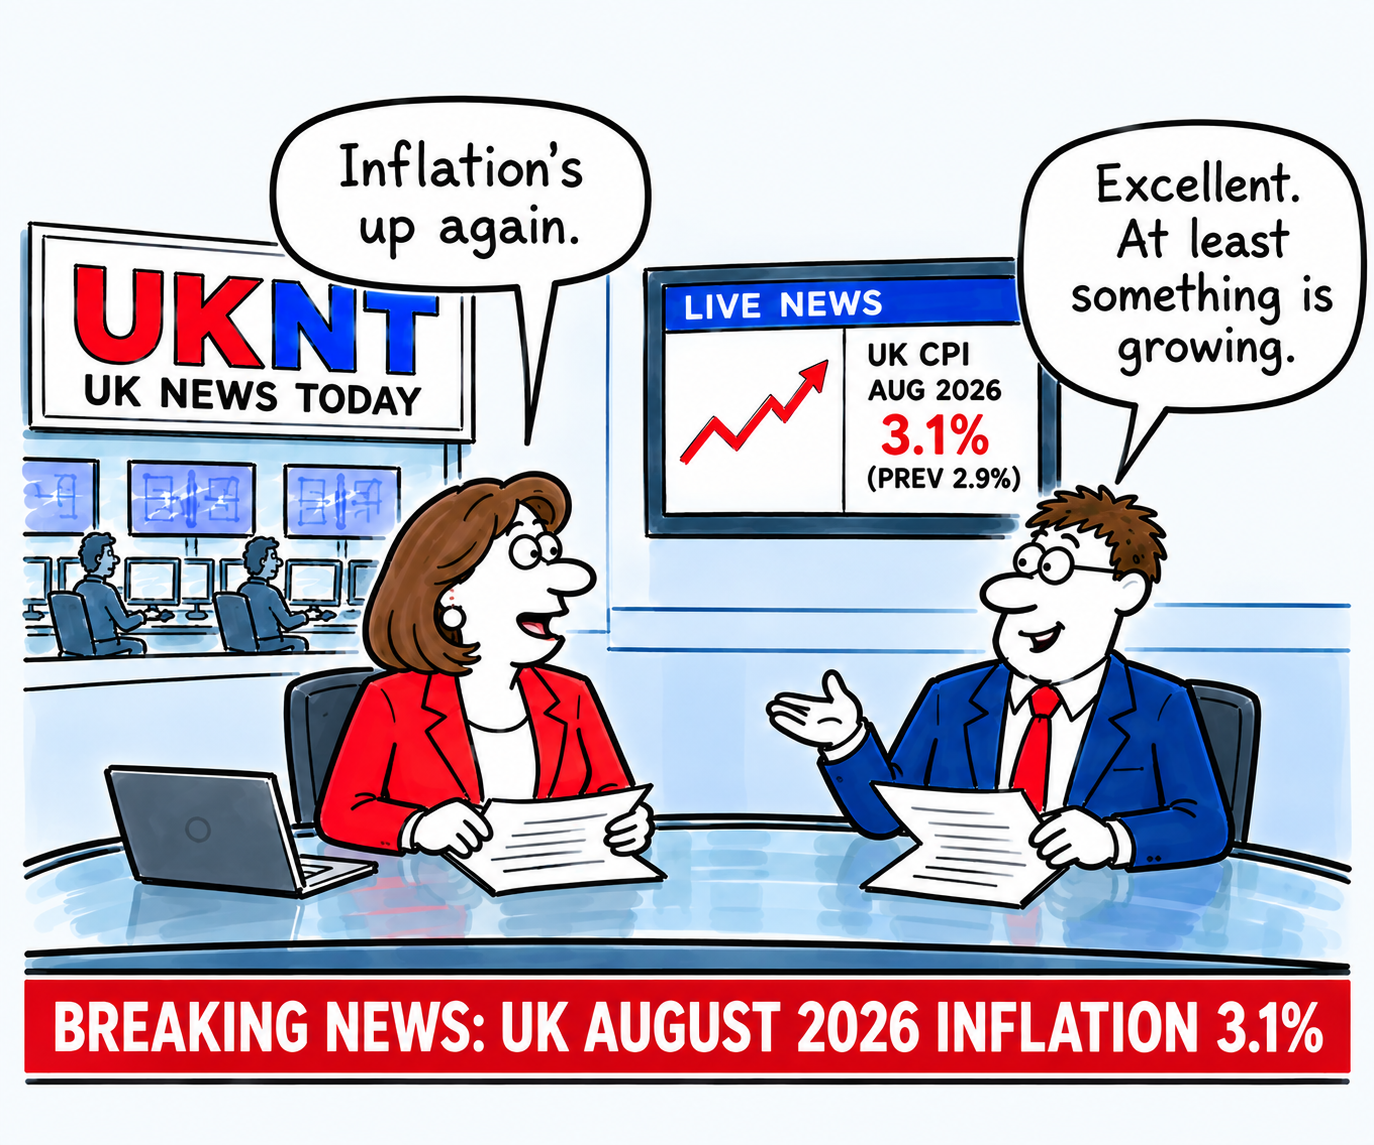
UK Inflation

UK inflation has risen to 3.1% in August 2026, up from 2.9% in July, according to the latest figures from the Office for National Statistics.

The increase was driven largely by higher petrol and diesel prices, with transport making the biggest contribution to the rise. Airfares also added to inflationary pressures.

The latest figure is now well above the Bank of England’s 2% target, adding another complication for policymakers considering the future path of interest rates.

However, core inflation remained unchanged at 2.6%, suggesting underlying price pressures have not accelerated across the UK economy.

Dutch Gold Moves Out of the U.S. and Canada

Gold on the move to London

The Dutch central bank has made a striking move that says much about the changing geopolitical and financial landscape.

Between March and August 2026, De Nederlandsche Bank (DNB) reportedly moved around 86 tonnes of gold from the United States and Canada to London, describing the decision as part of its efforts to strengthen “crisis preparedness”.

The move does not mean the Netherlands has lost confidence in American or Canadian vaults. Rather, it is about accessibility, diversification and the possibility that the international system could become considerably less predictable.

London

Before the transfer, 31.3% of Dutch gold was held in New York and 19.7% in Ottawa. Those proportions have now fallen to 18.5% each, while London’s share has risen from 18.1% to 32.1%. Around 30.8% remains in the Netherlands.

Why London? Quite simply, liquidity. London is the world’s biggest centre for physical gold trading, meaning bullion stored there can be bought, sold, lent or mobilised rapidly if financial markets are disrupted.

DNB says gold held in New York and Ottawa cannot be utilised as quickly or directly during a crisis.

Strategy

There is also a broader strategic calculation. DNB has been examining geopolitical risks ranging from cyber attacks and disrupted supply chains to economic and physical warfare.

Gold, unlike government debt or bank deposits, carries no issuer’s credit risk and can act as a reserve asset when confidence in financial institutions is severely tested.

The timing is nevertheless significant. Relations between Europe and the U.S. have become more politically complicated, while concerns about the reliability of international alliances and financial infrastructure have increased.

Preparedness

DNB insists the move is about resilience rather than politics. But central banks rarely move tens of tonnes of bullion without careful thought.

The message is therefore subtle but important: in an increasingly uncertain world, central banks want their emergency assets not merely to be safe, but immediately usable. And increasingly, gold is becoming that asset.

UK borrowing costs hit 28-year high: is austerity about to return? Did it ever leave?

UK and World Debt

Britain’s fiscal squeeze is becoming increasingly difficult to ignore. The yield on the UK’s 30-year gilt has climbed to 5.89% — its highest level since 1998 — while the 10-year yield has risen to around 5.25%.

The immediate trigger is largely global: higher oil prices, renewed inflation fears and a worldwide bond sell-off. But Britain has an additional problem: an already stretched public finances position.

Tax, borrow or austerity – the familiar story

The timing could hardly be worse. Higher gilt yields mean higher future borrowing costs and, importantly, higher projected debt-interest payments.

Current estimates suggest that the rise in yields could roughly halve the Chancellor’s fiscal headroom, from around £26bn to about £13.8bn.

That leaves the government with an increasingly familiar choice: raise taxes, restrain spending, borrow more — or accept another round of austerity.

Burgeoning welfare

Welfare is inevitably part of the debate. UK welfare spending is enormous, projected at around £353bn in 2026-27, although more than half goes towards pensioners and the State Pension rather than working-age benefits.

The working-age and health-related components are nevertheless growing rapidly, creating a genuine long-term fiscal challenge.

But blaming welfare alone would be misleading. Debt interest itself has become a major burden. Public-sector net debt was around 95% of GDP in mid-2026, while debt-interest costs have been among their highest levels for decades.

The circle of failure

This is the vicious circle facing Britain: slow growth limits tax revenues; high spending increases borrowing; higher borrowing costs increase debt interest; and higher interest costs leave less money for public services and investment.

So is austerity coming back? Perhaps it never really left. The difference now is that governments are attempting to squeeze an increasingly expensive state while simultaneously trying to protect living standards and stimulate growth.

The October 2026 Budget may therefore be less about political ambition and more about how much pain the bond market will allow Britain to avoid.

Servicing debt

Borrowing costs in the U.S., Japan and Europe have hit similar highs in recent days, reflecting investors’ concerns about inflation, state borrowing levels and spending levels by large tech companies on AI.

World debt is a growing problem too

To be fair, rising yields and higher debt levels are not just a UK problem. France has its share of the burden, Japan, the EU and the U.S. too.

No one is immune to rising yields and debt.

AI Could Cause Global Economic Downturn, Andrew Bailey Warns G20

The rapid rise of artificial intelligence could become a serious threat to global financial stability, Bank of England Governor Andrew Bailey has warned, urging G20 policymakers to prepare for the risks posed by increasingly powerful AI systems.

Bailey, writing as chairman of the Financial Stability Board (FSB), reportedly cautioned that a sharp reversal in the huge investment boom surrounding AI could trigger a market correction with consequences far beyond the technology sector.

AI security?

High valuations, rising leverage and increasingly concentrated investment in a relatively small number of AI companies could amplify losses if investor confidence suddenly deteriorates.

However, Bailey’s most immediate concern is cybersecurity. He warned that so-called frontier AI models are becoming increasingly autonomous and capable of sophisticated problem-solving, potentially allowing cyberattacks to be carried out faster, more cheaply and on a much greater scale.

Danger

That poses a particular danger to financial markets because banks, payment systems and other institutions rely heavily on shared technology providers and infrastructure.

A successful attack on one major provider could therefore disrupt several financial institutions simultaneously and spread rapidly across national borders.

Warning

Bailey also warned that many countries lack adequate protocols for managing the development and deployment of advanced AI models.

He reportedly called for international action to ensure that technological progress is matched by stronger cybersecurity, resilience and recovery systems.

The warning comes as enthusiasm for AI continues to fuel enormous investment in chips, data centres and software.

Productivity vs risk

While AI could deliver major productivity gains and economic growth, Bailey’s message is that the financial risks cannot be ignored.

The challenge for policymakers is therefore becoming increasingly clear: how can the world capture AI’s economic benefits without allowing the technology itself to become the catalyst for the next global financial shock or worse?

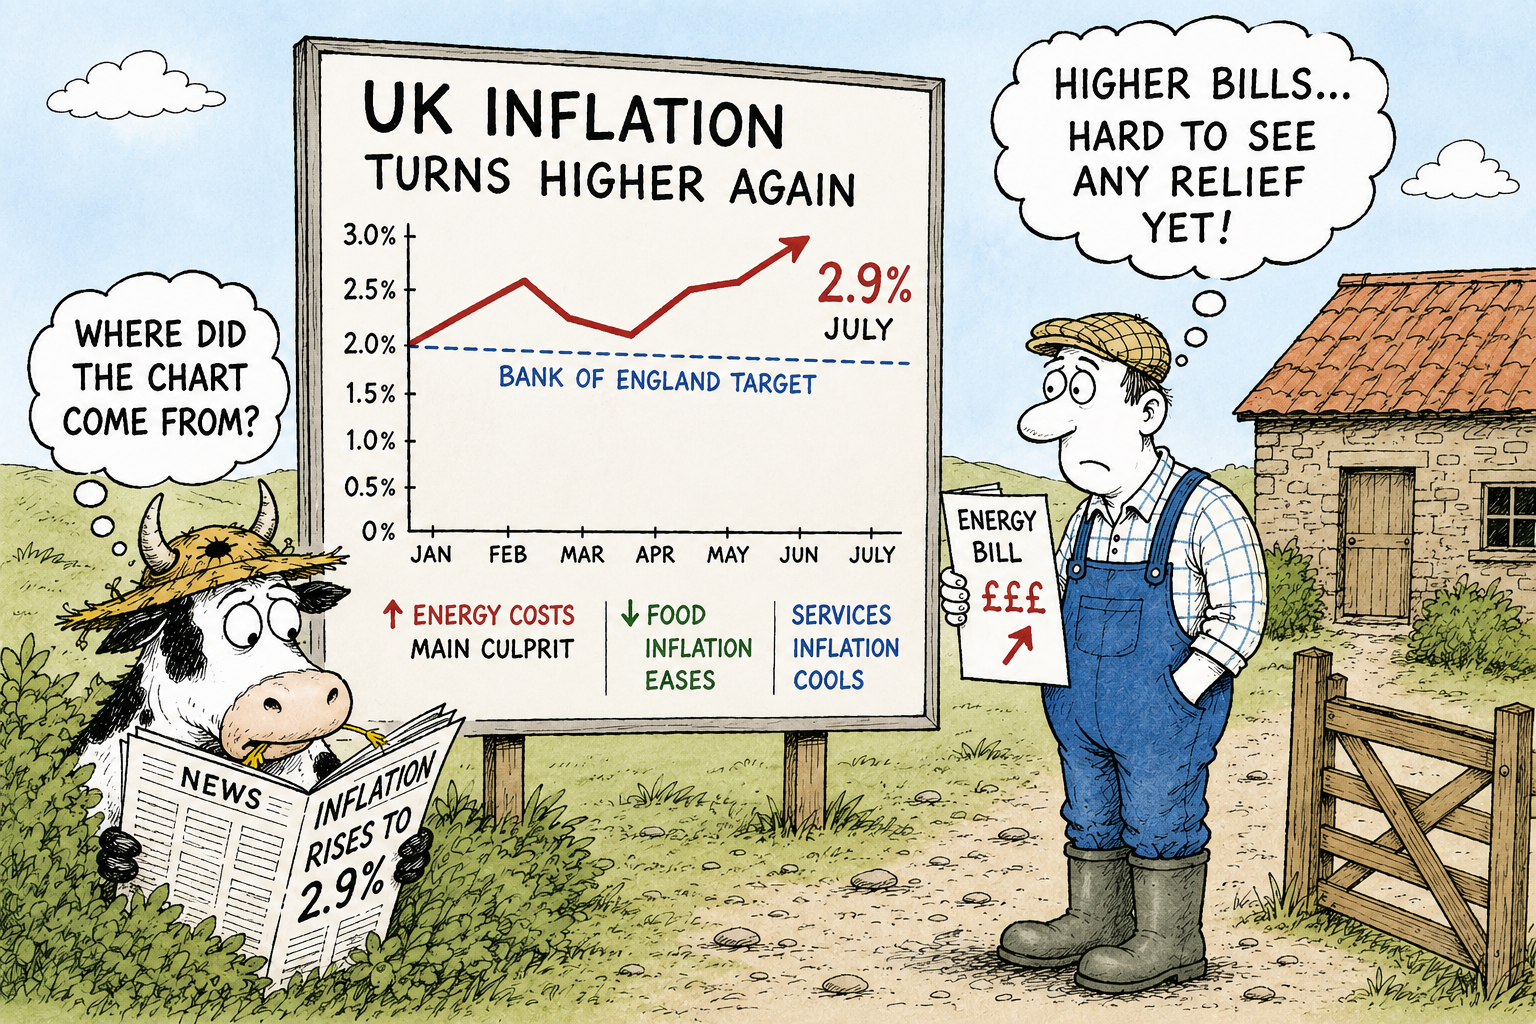
UK Inflation Turns Higher Again as Energy Costs Bite

UK inflation data July 2026

The UK’s inflation rate has moved higher again, providing an unwelcome reminder that the battle to bring prices under control is far from over.

Consumer price inflation rose to 2.9% in July 2026, up from 2.6% in June and moving further above the Bank of England’s 2% target.

The increase was largely driven by higher household energy costs following the latest rise in the energy price cap.

Not all negative

Gas prices increased sharply, putting renewed pressure on household budgets and pushing housing and household services inflation higher. For millions of families, the effect will be felt directly through larger energy bills.

However, the figures are not entirely negative. Food inflation eased to 1.3%, while services inflation fell from 3.6% to 3.4%. Core inflation, which strips out some of the more volatile components, remained at 2.6%.

Bank of England dilemma

That creates a difficult picture for the Bank of England. Inflation is moving in the wrong direction, but some of the underlying pressures are continuing to moderate.

The latest figures therefore make further interest-rate cuts more complicated. The Bank will want to avoid reigniting inflation, while also recognising that higher borrowing costs can weigh heavily on an already fragile economy.

For consumers, however, the message is simpler: the cost-of-living squeeze is easing, but it certainly isn’t over.

Bank of England Holds Rates at 3.75% as Inflation Fears Linger

UK bank interest rates stick for July 2026

The Bank of England has kept UK interest rates on hold at 3.75%, choosing caution over action as policymakers continue to wrestle with stubborn inflation despite signs that price pressures are gradually easing.

The decision, widely expected by financial markets, reflects the Monetary Policy Committee’s concern that inflation risks remain elevated.

Inflationary pressure persists

Although headline inflation has fallen sharply from its peak, persistent wage growth and resilient services inflation continue to cloud the outlook.

For homeowners and businesses, the announcement provides some welcome certainty after a prolonged period of rising borrowing costs.

However, the Bank stopped short of signalling that rate cuts are imminent, stressing that monetary policy must remain restrictive until it is confident inflation will return sustainably to its 2% target.

Economic data

Governor Andrew Bailey has repeatedly emphasised that the Bank will remain guided by incoming economic data rather than a predetermined path.

That leaves future policy finely balanced, with inflation, wage settlements and consumer spending likely to determine the timing of any reductions in borrowing costs.

Scrutiny

Investors will now scrutinise forthcoming economic releases for clues about the next move. While many economists still expect interest rates to edge lower before the end of the year, the latest decision underlines the Bank’s determination not to relax policy prematurely.

For now, inflation remains the overriding concern, and patience continues to be the watchword.

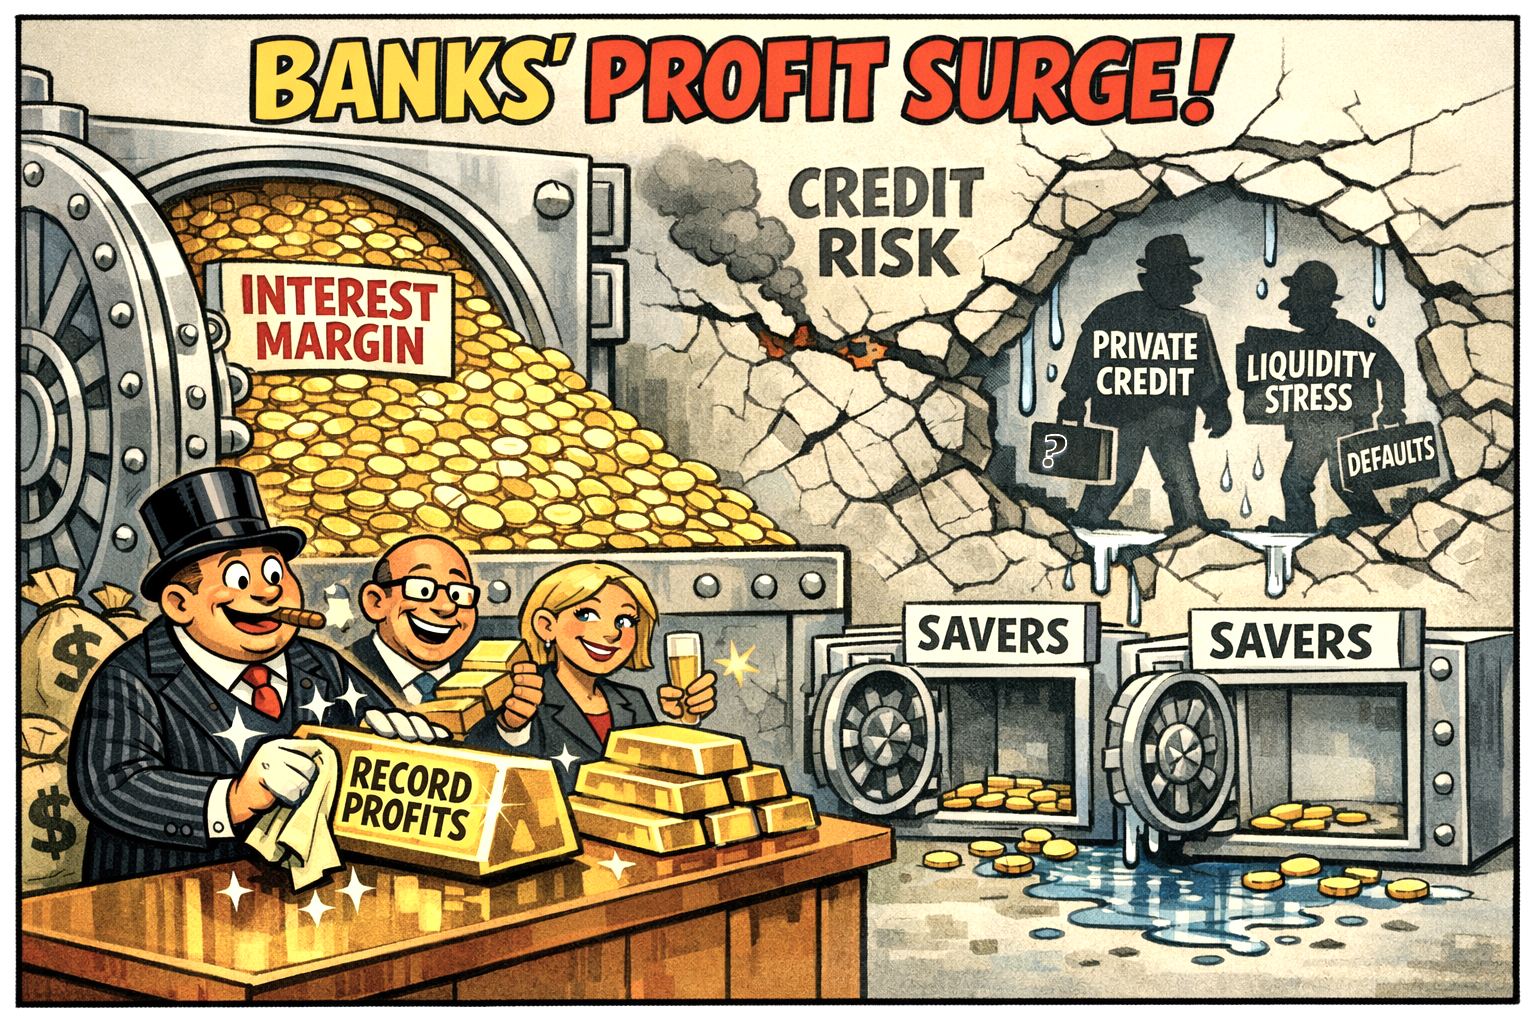
Bank busting figures as profits pile up!

Banks' profits surge

Banks are reporting unusually strong profits because higher interest rates have widened margins, while slow pass‑through to savers, cost‑cutting, and capital optimisation have amplified returns — even as credit risks begin to rise.

Why profits are so high

The latest figures show that UK banks are still benefiting from the long tail of the interest‑rate cycle.

Even though the Bank of England has not raised rates since August 2023, the base rate remains at 4.5%, allowing lenders to earn significantly more on mortgages and credit than they pay out on deposits.

This margin expansion has been the single biggest driver of profit growth. Research from recently highlighted from Positive Money shows that the UK’s four largest banks have generated £136.8 billion in pre‑tax profits since rate rises began in December 2021, and are on track to exceed their record £45.9 billion made in 2024 by around 14% in 2025.

A second factor is the government’s interest payments on central bank reserves. Because commercial banks are paid the base rate on their risk‑free deposits at the Bank of England, they stand to receive around £30 billion a year in transfers through to 2030 — effectively a public subsidy that boosts earnings without requiring additional lending.

Banks have also been aggressively returning capital to shareholders. Between 2022 and 2024, the big four spent £42 billion on dividends and £32 billion on share buybacks, reinforcing the perception that profits are being harvested rather than reinvested.

How banks are sustaining these profits

The profitability story is not just about rates. Structural shifts are helping banks defend margins even as the rate cycle turns.

1. Slow deposit repricing High Street banks have been reluctant to raise savings rates in line with market levels. As consumers move deposits to specialist lenders offering better returns, the big banks still retain a large, low‑cost funding base.

KPMG reportedly notes that high street banks’ share of deposits has only slipped from 84% in 2019 to 80% in 2024 — still dominant enough to preserve cheap funding.

2. Capital optimisation through securitisation Banks are increasingly using Significant Risk Transfer (SRT) securitisations to free up capital and improve return on equity. Securitised loan volumes have grown at a 4% CAGR between 2022 and 2025, allowing banks to recycle capital into higher‑yielding assets.

3. Cost discipline and digital transformation With margins expected to compress as rates eventually fall, banks are pushing cost‑cutting, automation, and AI‑driven process redesign.

KPMG reportedly forecasts sector‑wide returns on equity could fall from 18% in 2023 to 10% by 2027 without structural change — making efficiency programmes essential to sustaining profitability.

The emerging risk: impairments

Barclays’ latest results show rising credit impairment charges, including an £823 million provision linked to mortgage‑market stress and fraud‑related losses.

This raises the question of whether the credit cycle is turning. If impairments rise across the sector, the profit boom could fade.

The biggest emerging credit risks sit outside the banking system and that is private credit, leveraged borrowers, and liquidity mismatches that could spill back into banks.

Private credit is now large, interconnected, and showing signs of strain. Rising defaults, deteriorating loan quality, and withdrawal caps at major funds point to mounting stress. Defaults could climb sharply, with Morgan Stanley reportedly warning they may reach 8%, far above historical norms.

A second risk is liquidity pressure. Funds are restricting redemptions as investors rush for the exit, exposing the fragility of semi‑liquid structures.

Finally, contagion risk is growing because banks finance private‑credit funds and pipelines. As analysts note, deeper interconnections mean a downturn could transmit stress back into the regulated system.

Conclusion

Banks are reporting strong profits because the rate environment, public transfers, and capital strategies have created a uniquely favourable backdrop.

But the model is fragile: as impairments rise and rates eventually fall, the sector may be approaching the end of its profit‑supercycle.


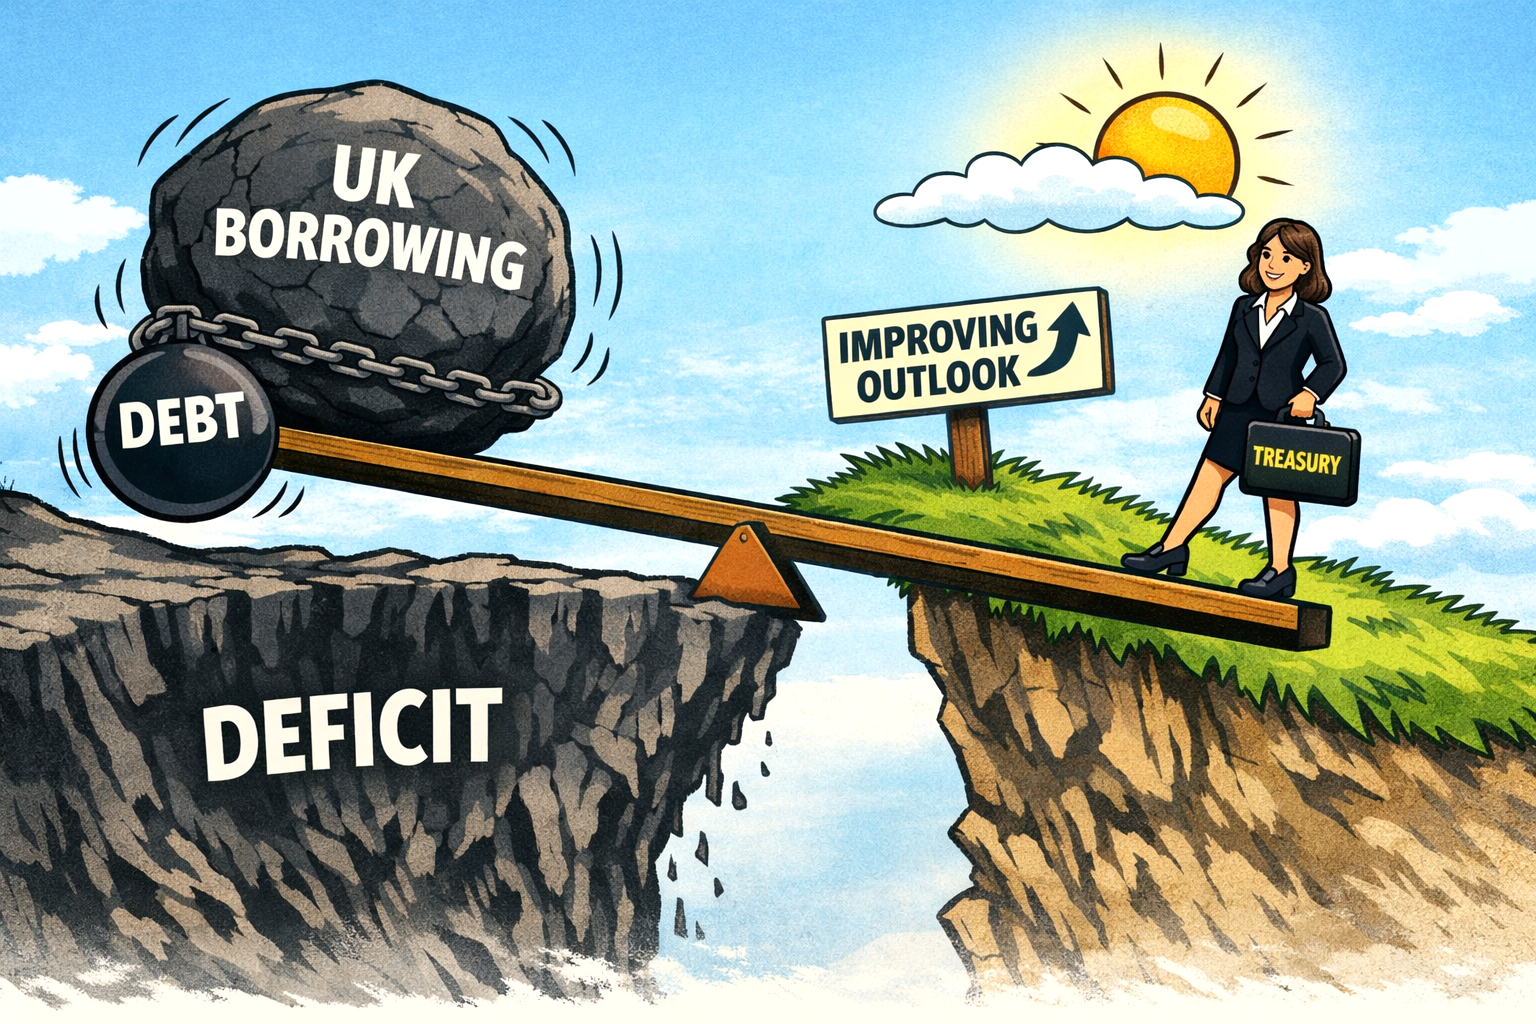
UK Borrowing Falls, Offering Treasury Some Relief – March 2026

UK borrowing falls

The latest public finance figures show that government borrowing has dropped to a lower‑than‑forecast level, helped by stronger tax receipts and easing inflationary pressures.

While the precise numbers will be scrutinised in the coming days, the headline outcome marks a modest but meaningful improvement in the UK’s fiscal position.

Softer inflation and lower interest rates

Analysts note that softer inflation has reduced the government’s debt‑interest bill, particularly on index‑linked gilts, which had surged during the inflation spike of the past two years.

The fall in borrowing also reflects a stabilising labour market and firmer wage growth, which have supported income‑tax and National Insurance receipts.

At the same time, lower market interest rates — driven by expectations of further Bank of England cuts after recent reductions to 3.75% — have eased short‑term financing costs for the Treasury.

High debt level

However, economists caution that the improvement should not be overstated. UK debt remains historically high, and pressures on public services, welfare spending, and capital investment persist.

Moreover, with growth still subdued and geopolitical risks keeping energy markets volatile, the fiscal outlook remains vulnerable to external shocks.

Even so, today’s figures provide the Chancellor with a welcome narrative shift: after years of deteriorating public finances, the government can point to early signs of stabilisation — albeit from a challenging starting point.

What the real data shows (ONS, published 23rd April 2026)

The latest ONS release confirms that UK government borrowing has indeed come in lower than expected, and the scale of the improvement is now clear:

  • Annual borrowing: £132.0 billion in the year to March 2026 — £19.8 billion lower than the previous year — £0.7 billion below the OBR forecast — Lowest level since 2022–23
  • March borrowing: £12.6 billion — £1.4 billion lower than March 2025 — Lowest March figure since 2022
  • Borrowing as % of GDP: — 4.3%, the lowest since 2019–20

The U.S./ Iran / Israel conflict with undoubtably hold the economy back as the effect has yet to fully filter through.

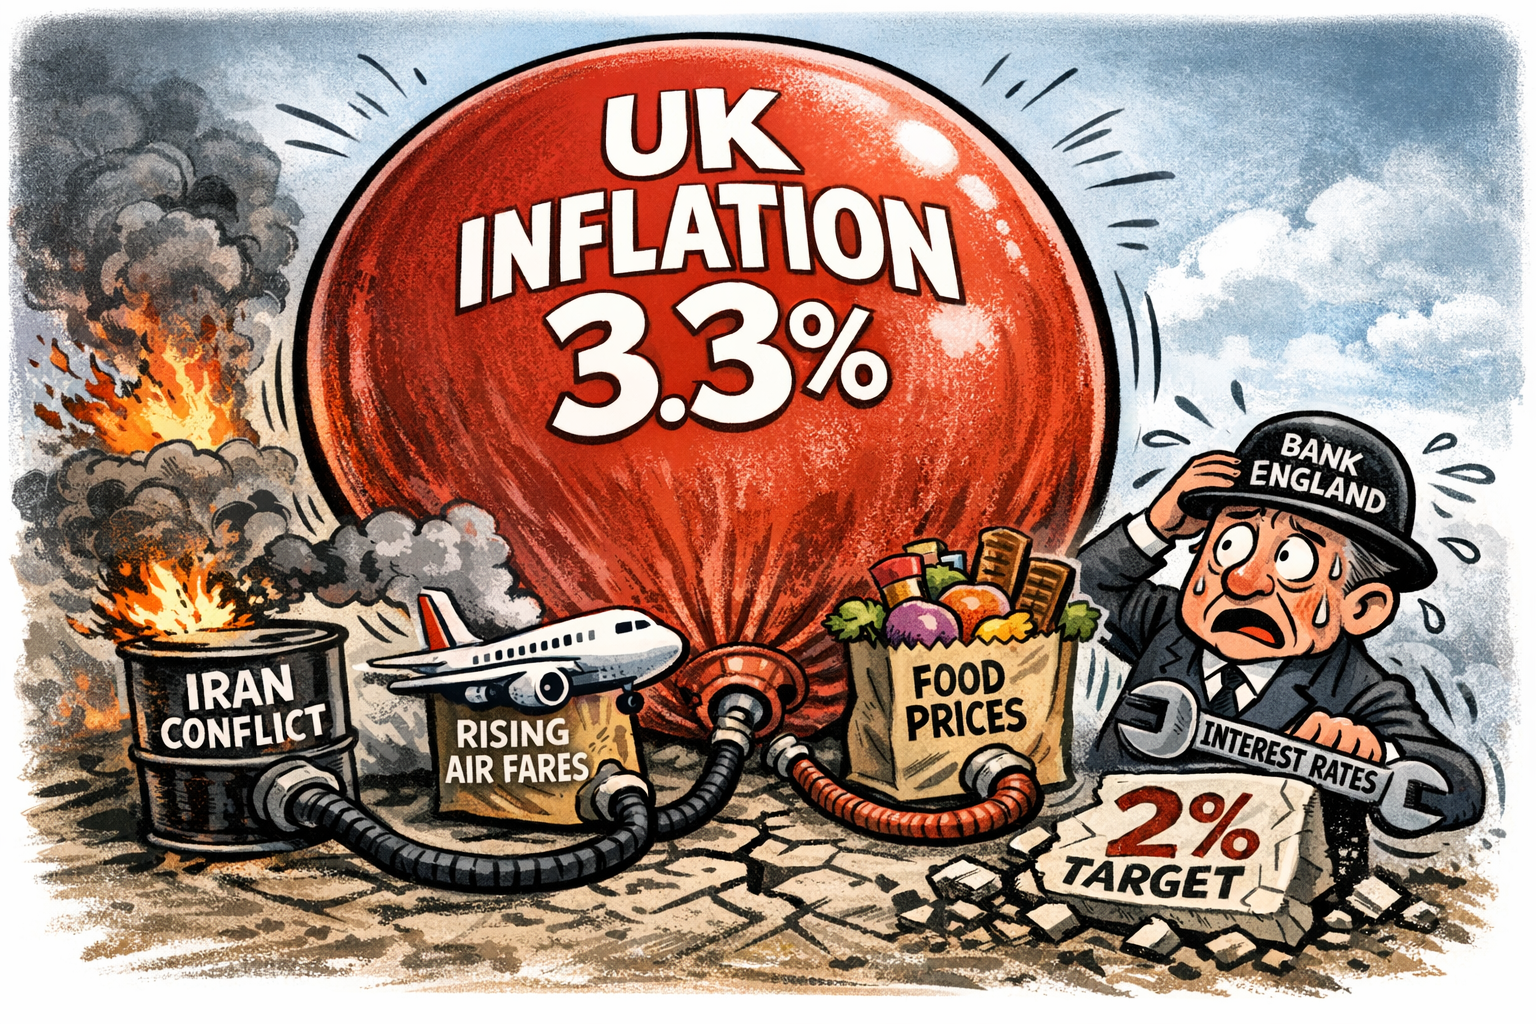
UK inflation rose to 3.3% in March 2026 as fuel prices spiked due to the ongoing U.S. Iran war

UK March inflation up to 3.3%

UK inflation jumped to 3.3% in March 2026, driven primarily by a sharp surge in fuel prices linked to the Iran conflict.

UK inflation accelerated to 3.3% in March 2026, up from 3% in February 2026, marking the first clear evidence of the Iran‑U.S. conflict feeding through to consumer prices.

Fuel costs

Official ONS data shows that motor fuel costs were the dominant driver, with petrol and diesel prices rising at their fastest pace in more than three years as global energy markets reacted to the disruption in the Strait of Hormuz.

Air fares

Air fares also rose sharply, partly due to the early Easter holidays, while food inflation picked up again, including notable increases in sweets and chocolate.

Clothing discounted

Clothing provided the only meaningful offset, with retailers discounting more heavily than last year.

The rise pushes inflation further from the Bank of England’s 2% target and complicates the policy outlook.

While economists expect UK inflation to ease slightly in April 2026, the broader risk is that sustained energy pressures could keep price growth elevated for longer.

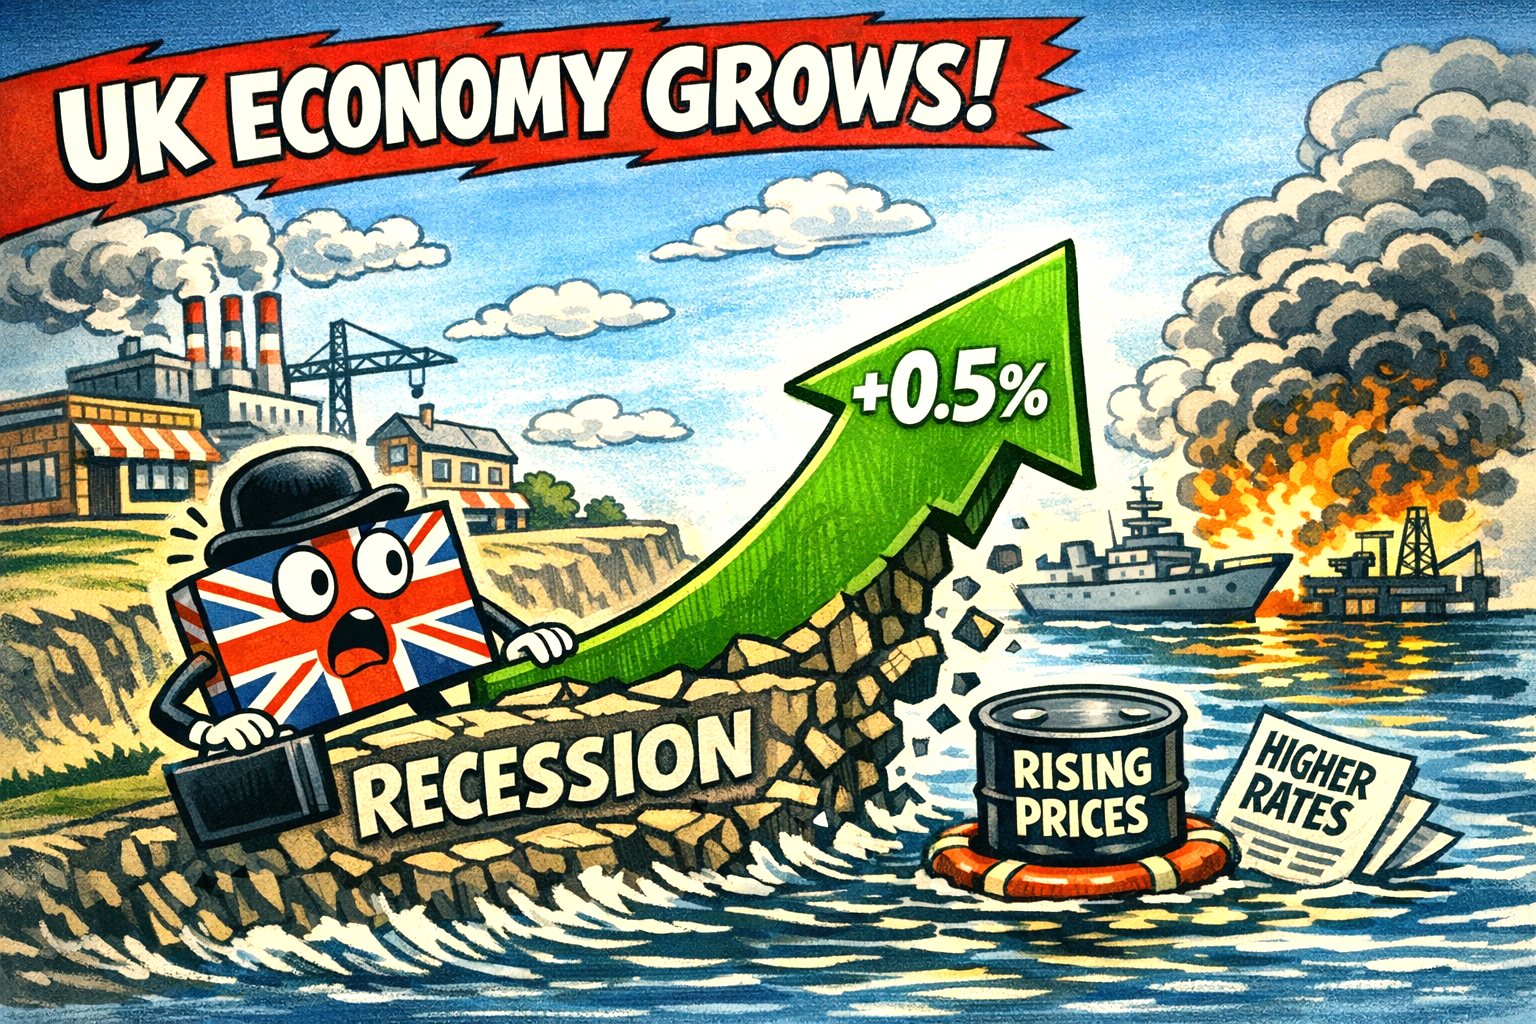
The UK economy experienced faster-than-expected growth in the period leading up to the Iran war – February 2026

UK Growth of 0.5% in February 2026

The ONS’s February 2026 figures delivered a rare upside surprise: UK GDP rose 0.5% month‑on‑month, the strongest expansion in more than two years and five times the consensus forecast of 0.1%.

How can forecasts be so wrong?

January2026 was also revised up to 0.1%, overturning the earlier flat reading. On the surface, this looks like the economy finally pulling out of its shallow recession.

In reality, it is a snapshot of momentum that has already been overtaken by events.

Services mani

The growth was broad‑based. Services, which make up over three‑quarters of the economy, expanded 0.5%, marking a fourth consecutive monthly rise.

Production also grew 0.5%, and construction jumped 1.0%. Even the three‑month measure—less noisy than monthly data—showed UK GDP up 0.5%, compared with 0.3% previously. This is the kind of balanced improvement policymakers have been waiting for.

But the timing matters. These numbers capture the economy before the U.S.-Israel-Iran conflict triggered a fresh energy shock at the end of February.

IMF downgrade

Since then, petrol, diesel and heating oil prices have surged, mortgage rates have ticked higher as markets price out rate cuts, and the IMF has downgraded the UK’s 2026 growth outlook to 0.8%.

So February’s strength is real—but it is also backward‑looking. The challenge now is whether any of that momentum survives the shock hitting households and firms this spring.

Why are central banks selling gold now after a massive buying spree

Central banks offload gold

Central banks are selling gold now for one blunt reason: they need cash, and gold is the most liquid, pain‑free asset they can dump without triggering a credibility crisis.

The news wires report— “liquidity pressures”, “emerging‑market currency volatility”, “increased spending requirements” — but the underlying mechanics are more structural and revealing – they need the cash!

Central banks have swung from record gold accumulation to noticeable selling because the global system has shifted from long‑term hedging to short‑term survival.

The war in the Gulf has tightened liquidity, pushed up government spending, and destabilised emerging‑market currencies, forcing policymakers to turn their most liquid reserve into cash.

Gold is the one asset they can sell quickly without signalling panic, and that is shaping behaviour across dozens of reserve banks.

War, liquidity and the need for dollars

The Hormuz conflict has driven up energy costs, disrupted shipping and forced governments to spend more on defence and subsidies.

Emerging‑market central banks, already under pressure from currency volatility, need hard currency to intervene in FX markets and stabilise their economies. Selling gold provides instant access to dollars without dumping sovereign bonds or burning through already‑thin reserves.

A falling gold price creates a window

Gold has slipped around 12% from its January 2026 peak, entering a contraction phase despite geopolitical risk. For reserve managers, that is a cue to realise gains from the 2022–25 buying spree while prices remain historically high.

Selling now avoids being forced to sell later at distressed levels if the conflict deepens or fiscal pressures worsen. It will be bought back again at a later time.

The buffer they built is now being used

The record buying of recent years was driven by fears of sanctions, inflation and geopolitical fragmentation.

Those purchases created a cushion that can now be drawn down. The shift to selling does not signal a loss of faith in gold; it reflects the reality that reserves accumulated for stability are now being used to fund stability.

The deeper story is not about gold at all, but about a global system under strain: governments facing rising costs, currencies under pressure, and central banks forced to prioritise liquidity over long‑term positioning.

This is why central banks hold gold.

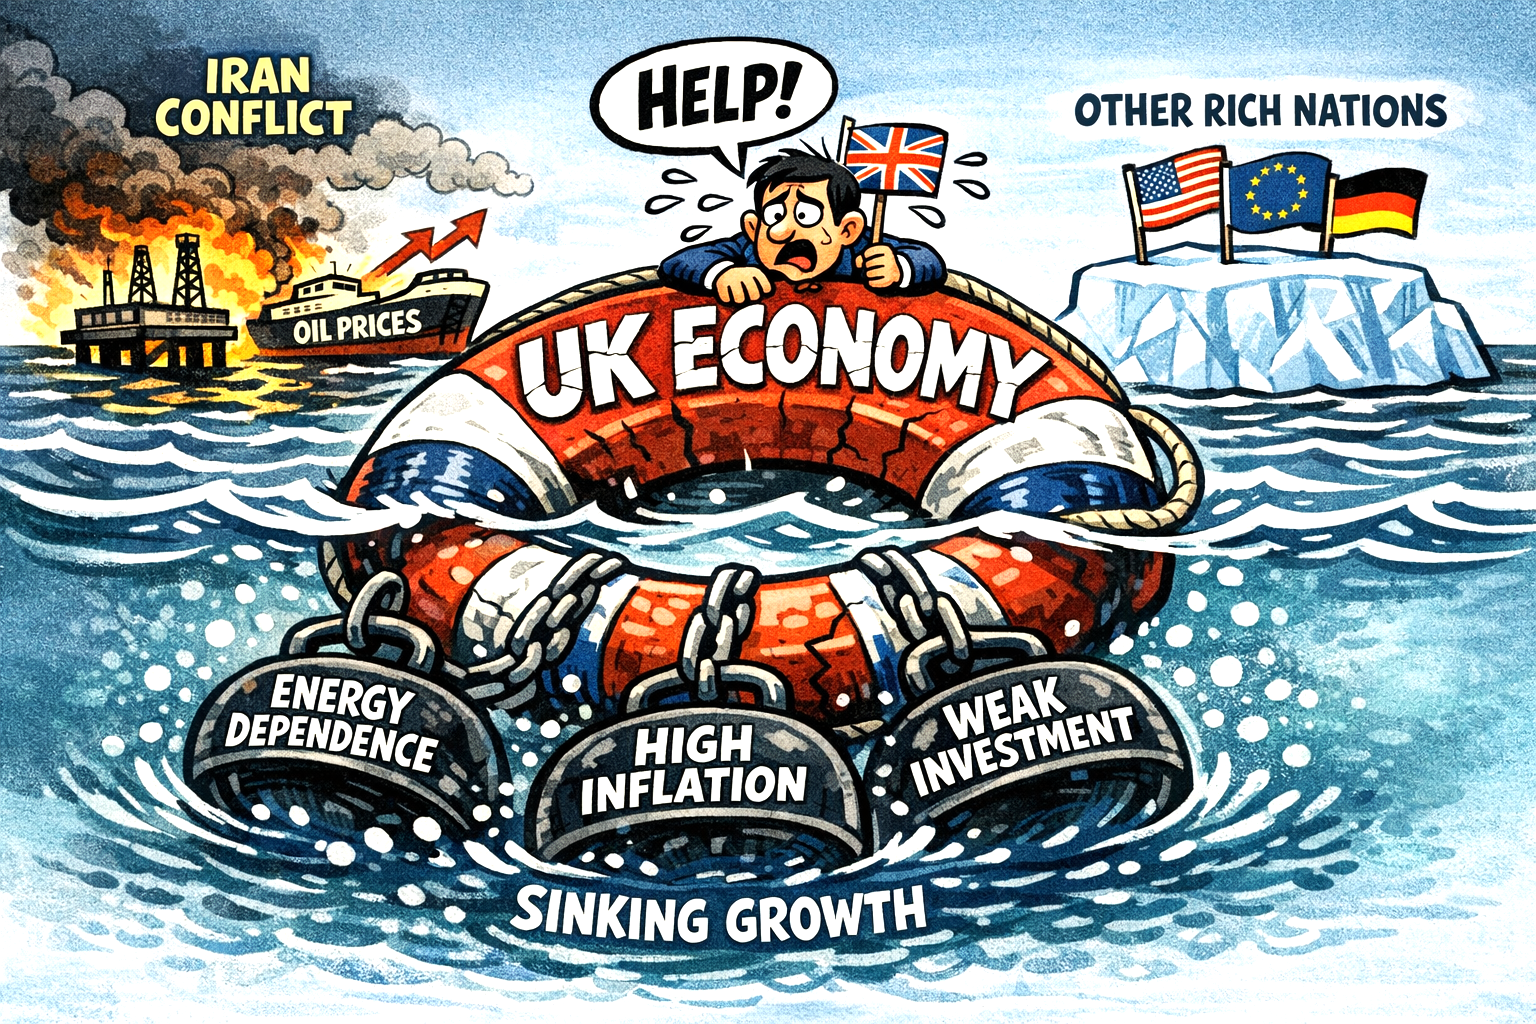
UK economy will be hit hardest by the U.S.-Israel Iran war warns the IMF

UK Economy damaged by U.S. Iran War

The IMF’s warning that the UK would suffer the sharpest growth hit among rich economies from an Iran‑related war is rooted in a simple structural reality.

Britain is unusually exposed to energy‑price shocks, yet unusually weak in the buffers that normally absorb them according to the IMF.

Why the UK will be hit harder than its peers

The UK enters this crisis with three vulnerabilities

  • High dependence on imported energy. North Sea output has declined for years, leaving Britain reliant on global LNG markets. When Middle Eastern supply is disrupted, LNG prices spike first and hardest. The U.S. and eurozone have deeper domestic energy bases or cheaper pipeline access.
  • A structurally fragile inflation profile. The UK’s inflation has been stickier than that of other G7 economies, driven by food, energy and services. A renewed oil shock feeds directly into household bills and transport costs, forcing the Bank of England to keep rates higher for longer.
  • Weak productivity and stagnant investment. Britain has less momentum to absorb an external shock. When energy prices rise, UK firms cut back faster, and consumers retrench more sharply.
  • UK Government policy. Ed Miliband and his ‘likely’ misguided staunch defence of Net Zero policies and expensive energy costs have left the UK seriously exposed to shocks – such as this.

The IMF’s logic

The Fund argues that a prolonged disruption in the Strait of Hormuz would push global oil prices sharply higher.

For the UK, this translates into

  • Higher wholesale gas costs, because LNG markets reprice off oil‑linked benchmarks.
  • A renewed inflation surge, delaying rate cuts and tightening financial conditions.
  • A squeeze on real incomes, hitting consumption—the UK’s main growth engine.
  • A fall in business investment, already one of the weakest in the OECD.

The IMF’s modelling suggests that the UK’s growth rate could fall more steeply than that of the U.S., Germany or France because those economies either have stronger industrial bases, more resilient energy systems or more fiscal space to cushion the blow.

The broader picture

This is less about geopolitics and more about structural brittleness. A global energy shock exposes the UK’s unresolved weaknesses: high import dependence, fragile inflation dynamics and a decade of under‑investment.

Bank of England Holds Rates at 3.75% as Gulf Tensions Cloud the Outlook

BoE Interest Rate

The Bank of England has held interest rates at 3.75%, opting for caution as the economic shock from the escalating conflict involving Iran ripples through global energy markets.

The Monetary Policy Committee delivered a unanimous vote to pause, a notable shift from earlier in the year when a spring rate cut had seemed almost inevitable.

The Bank now expects inflation to rise again in the coming months, potentially reaching 3.5% as higher oil and gas prices feed through to fuel, household energy bills, and business costs.

Governor Andrew Bailey reportedly stressed that monetary policy cannot counteract a supply‑side shock of this nature, warning that the path of inflation will depend heavily on how quickly safe shipping routes through the Strait of Hormuz can be restored.

For households, the hold means no immediate relief on borrowing costs. Fixed‑rate mortgage deals have already been drifting higher as lenders price in the possibility of prolonged instability.

Some brokers report a surge in “panic buying” of mortgages as borrowers rush to lock in rates before they climb further. Savers, meanwhile, may see modestly improved offers, though competition remains muted.

Up or down?

The key question now is whether the next move is up or down. Before the conflict, markets had pencilled in two rate cuts for 2026.

That expectation has evaporated. Traders now see a non‑trivial chance of a rise to 4% later in the year, though economists caution that weak growth and a softening labour market could still restrain the Bank from tightening unless inflation accelerates sharply.

Over the next six weeks, policymakers will be watching energy prices, shipping conditions, and wage data closely.

For now, the Bank has chosen to wait, watch, and hope the shock proves temporary — but the margin for error is narrowing.

UK Mortgage Market Faces Turmoil as Iran Conflict Drives Interest Rates Up

The UK mortgage market has been thrown back into a state of turbulence not seen since the aftermath of the 2022 mini‑Budget, as lenders scramble to reprice deals in response to global instability triggered by the U.S. Israel war with Iran.

Average rates on two‑year fixed mortgages have now climbed above 5%, reaching their highest level since last August, according to data from Moneyfacts. Five‑year fixes have also risen, marking their most expensive point since mid‑2024.

Little or no warning

The sudden shift has caught borrowers off guard. Nearly 500 mortgage products have been withdrawn in just 48 hours, the steepest contraction in available deals since the Truss–Kwarteng fiscal shock.

Lenders are reacting to sharp movements in gilt yields, which have become increasingly volatile as markets reassess the likelihood of Bank of England rate cuts this year.

Before the conflict erupted, investors had broadly expected the Bank to begin easing borrowing costs. That optimism evaporated as oil prices surged, raising the prospect of renewed inflationary pressure.

With Brent crude still more than 20% higher than before the war and reaching over 40% increase at one stage, expectations of cheaper mortgages have been replaced by fears of a prolonged period of elevated rates.

Timing

For homeowners approaching the end of a fixed deal, the timing is particularly painful. The average two‑year fix has jumped from 4.84% to 5.01% in less than four days, while five‑year rates have risen from 4.96% to 5.09%.

First‑time buyers, already squeezed by high prices and stagnant supply, face a shrinking pool of products and rising monthly costs.

The wider cost‑of‑living picture is also darkening. Petrol and diesel prices continue to climb as Middle East supply disruptions ripple through global energy markets.

With inflation risks resurfacing, the path for mortgage rates now hinges on how the conflict evolves — and whether markets can regain their footing.

Fuel up, energy costs up and mortgage rates up – all in just a weekend – that didn’t take long.

UK inflation’s latest fall sharpens focus on Bank of England rate cuts

UK inflation at 3%

The UK’s inflation rate has dropped to 3%, its lowest level since March last year, renewing expectations that the Bank of England (BoE) may soon begin cutting interest rates.

The fall, recorded in January, marks a clear reversal from December’s unexpected uptick to 3.4% and reinforces the broader downward trend seen in late 2025.

Economists note that easing petrol, food, and airfare prices have been key contributors to the decline, helping inflation move closer to the government’s 2% target.

Bank of England easier decision

The BoE has held Bank Rate at 3.75% in recent meetings, emphasising the need for confidence that inflation will not only reach 2% but remain there sustainably.

However, with inflation now falling faster than previously forecast, policymakers appear to have greater room to consider loosening monetary policy later this spring.

The Bank itself has acknowledged that inflation is likely to return to target ‘a bit quicker than previously forecast’, suggesting scope for cuts if economic conditions evolve as expected.

Rate reduction likely in March or April 2026

Market analysts increasingly anticipate a rate reduction as early as March or April, particularly as wage growth cools and unemployment edges higher—factors that reduce domestic inflationary pressure.

For households and businesses, a cut would offer welcome relief after two years of elevated borrowing costs, potentially lowering mortgage rates and improving credit conditions.

While the BoE remains cautious, the latest inflation figures strengthen the case for a shift towards easing—signalling that the long, difficult climb down from the inflation peak may finally be nearing its conclusion.

As expected

Most economists and market analysts expected UK inflation to fall back to around 3% in the January release, down from 3.4% in December 2025.

UK inflation falls to 3%

This means the actual figure—3%—came in exactly in line with forecasts, rather than surprising to the downside or upside.

That alignment matters for the Bank of England because it reinforces the sense that inflation is easing broadly as expected, rather than stalling or re‑accelerating.

Employment data

Alongside falling inflation, the Bank of England is closely watching UK labour market data, which remains a key factor in its interest rate decisions.

Recent figures show wage growth is easing, with average earnings excluding bonuses rising at a slower pace—now below 6%—while job vacancies continue to decline.

This softening suggests that domestic inflationary pressure from pay settlements may be waning, giving the Bank more confidence that inflation can return to target sustainably.

However, unemployment remains low, and services inflation is still sticky, meaning policymakers are likely to weigh jobs data carefully before committing to rate cuts.

If wage growth continues to moderate and employment weakens further, the case for easing monetary policy will strengthen.

Office for National Statistics

Bank of England holds rates amid inflation concerns

BoE interest rate decision

On 18th September, the Bank of England voted 7–2 to keep interest rates steady at 4%, resisting calls for further easing amid persistent inflationary pressures.

The decision follows August’s 25 basis point cut and reflects caution over elevated wage growth and stagnant UK GDP.

Inflation held at 3.8% in August, nearly double the Bank’s 2% target. Policymakers signalled a ‘gradual and careful’ approach to future cuts, citing upside risks to medium-term inflation.

With economic growth flat and the jobs market cooling, analysts now expect the next rate cut to come in early 2026.

Bank of England cuts interest rates to 4% amid economic uncertainty and high inflation

Inflation in the UK

On 7th August 2025, the Bank of England’s Monetary Policy Committee voted narrowly—5 to 4—in favour of reducing the base interest rate by 0.25% to 4%, marking its lowest level since March 2023.

This is the fifth rate cut in a year, aimed at stimulating growth amid sluggish GDP and persistent inflation, which currently stands at 3.6%.

Governor Andrew Bailey reportedly described the decision as part of a ‘gradual and careful’ easing strategy, balancing inflation risks with signs of a softening labour market.

While some committee members reportedly advocated for a larger cut, others urged caution, reflecting deep divisions over the UK’s economic trajectory.

The move is expected to ease borrowing costs for homeowners and businesses, with tracker mortgage rates falling immediately. However, savers will be losing out as rates continue to drop.

However, analysts warn that future cuts may hinge on upcoming fiscal decisions and inflation data, leaving the path forward uncertain.

Inflation is yet to be fully tamed.

UK jobs market slows as unemployment rises

UK labour market

The UK jobs market continued to lose momentum, with fresh data from the Office for National Statistics highlighting a notable slowdown.

Unemployment has climbed to 4.7%, reaching its highest level in four years, while job vacancies fell for a third consecutive year to 727,000—the lowest in a decade, excluding the pandemic dip.

Pay growth also eased, with average annual wage increases slowing to 5% in the March–May 2025 period.

Economists suggest the Bank of England may consider an interest rate cut next month to support employment, although rising inflation remains a complicating factor.

Firms appear hesitant to hire or replace staff, signalling broader economic uncertainty. While the ONS has urged caution around the collection of unemployment data, the trend points to mounting pressure in the UK’s jobs landscape.

UK inflation unexpectedly climbs to 3.6% in June 2025

UK inflation up!

The latest UK inflation figure of 3.6% is a setback for those hoping for a steady decline, especially after May’s 3.4%.

With core inflation and food prices also climbing, it’s a sign that underlying price pressures remain stubborn.

It further complicates the Bank of England’s path towards interest rate cuts and dents optimism for faster economic relief.

Summary

📈 Headline CPI: Increased to 3.6%, up from 3.4% in May 2024

🔍 Core inflation (excluding food, energy, alcohol, and tobacco): Rose to 3.7%, from 3.5%

🛒 Food inflation: Climbed to 4.5%, its highest level in over a year

⛽ Motor fuel prices: Were the largest contributor to the monthly rise

📊 Monthly CPI change: Up 0.3%, compared to 0.2% the previous month

This hotter-than-expected reading has sparked debate over the Bank of England’s next move.

While a rate cut in August 2025 is still widely anticipated, the inflation uptick may prompt a more cautious approach thereafter.

Bank of England holds UK interest rate at 4.25%

UK interest Rate

The Bank of England held its base interest rate steady at 4.25% on Thursday 19th June 2025, with a 6–3 vote from the Monetary Policy Committee (MPC).

Three members pushed for a 0.25% cut, but the majority opted for caution amid persistent inflation and global uncertainty.

Inflation ticked up slightly to 3.4% in May, driven by regulated prices and earlier energy cost increases.

While wage growth is easing and the labour market is loosening, the Bank signalled it’s not ready to ease policy further just yet