$1 TRILLION WIPED OFF MAGNIFICENT SEVEN IN ONE DAY

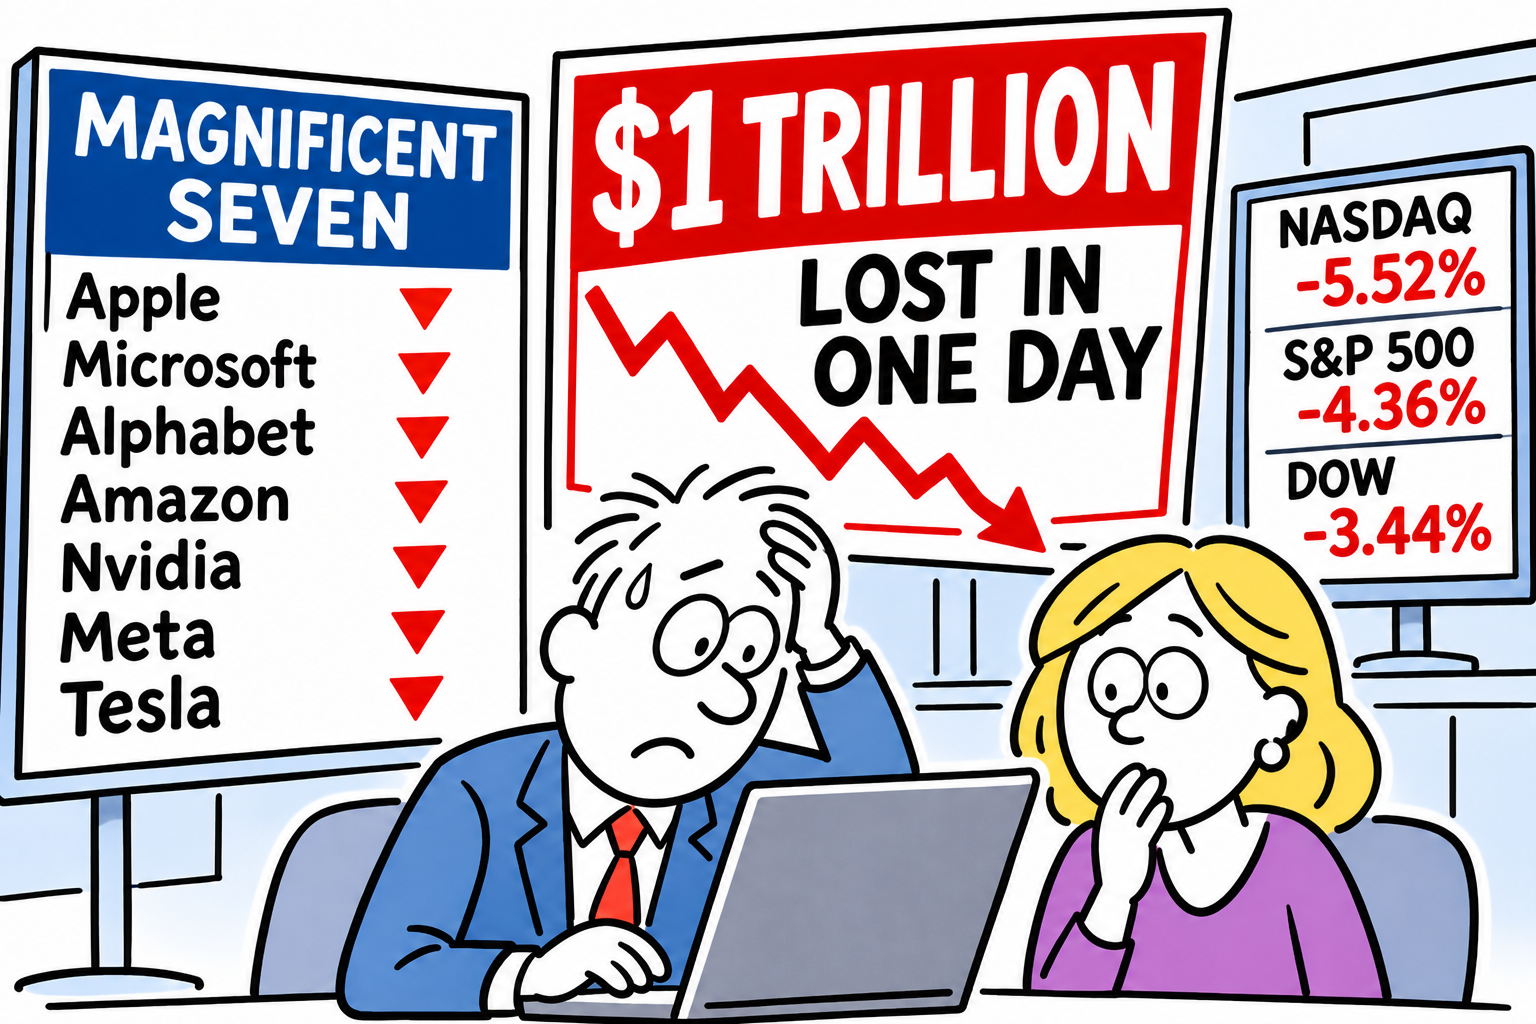
Graph showing the Magnificent Seven tech companies’ combined market value dropping by approximately $1 trillion during the Wall Street sell-off on 6th November 2026.

The Magnificent Seven, America’s seven technology companies, lost around $1 trillion in market value during Thursday’s Wall Street sell-off on 5th November 2026.

The figure is broadly correct: estimates put the decline at approximately $1.0 trillion to $1.04 trillion, although calculations vary between sources and market snapshots.

Magnificent Seven

The group comprises Apple, Microsoft, Alphabet, Amazon, Nvidia, Meta Platforms and Tesla. All seven fell as investors reduced exposure to technology and artificial-intelligence shares. Nvidia was among the hardest hit.

One estimate put its lost market value at $431 billion, while Tesla suffered the group’s steepest decline, falling almost 12 per cent. Microsoft reportedly lost about $123 billion in market capitalisation.

Retreat

The rout formed part of a wider market retreat. The Nasdaq Composite fell 5.5 per cent, its sharpest one-day decline in 19 months, and entered correction territory, meaning it had fallen at least 10 per cent from its record closing high.

The S&P 500 dropped 4.4 per cent and the Dow Jones Industrial Average fell 3.4 per cent.

Several concerns converged. Investors questioned whether sums committed to AI data centres, chips and infrastructure would generate sufficient returns.

U.S. Midterm Elections

Midterm election victories for candidates critical of data centre expansion raised the prospect of tighter regulation and planning restrictions.

Disappointing chip-sector results added to anxiety, while high valuations left technology shares vulnerable when sentiment turned.

It is important to understand what the trillion-dollar figure means. It is not cash withdrawn from company bank accounts, nor money physically disappearing.

It represents the fall in the stock-market value investors assign to the seven businesses.

More to come?

The immediate question is whether this is a sharp correction or the beginning of a deeper reassessment of the AI boom. Much will depend on company results, investment plans and evidence that AI spending can deliver lasting profits.

For now, confidence has suffered a shock.

Note: A particularly important distinction: The $1 trillion represents lost stock-market valuation, not $1 trillion of cash disappearing from these companies.

I think the underlying story is bigger than a dramatic one-day fall. It raises serious questions about whether the enormous valuations attached to AI companies and their supporting infrastructure can be justified by future earnings.

Global stock market rout: Nasdaq enters correction as Japan’s Nikkei slides into bear market territory

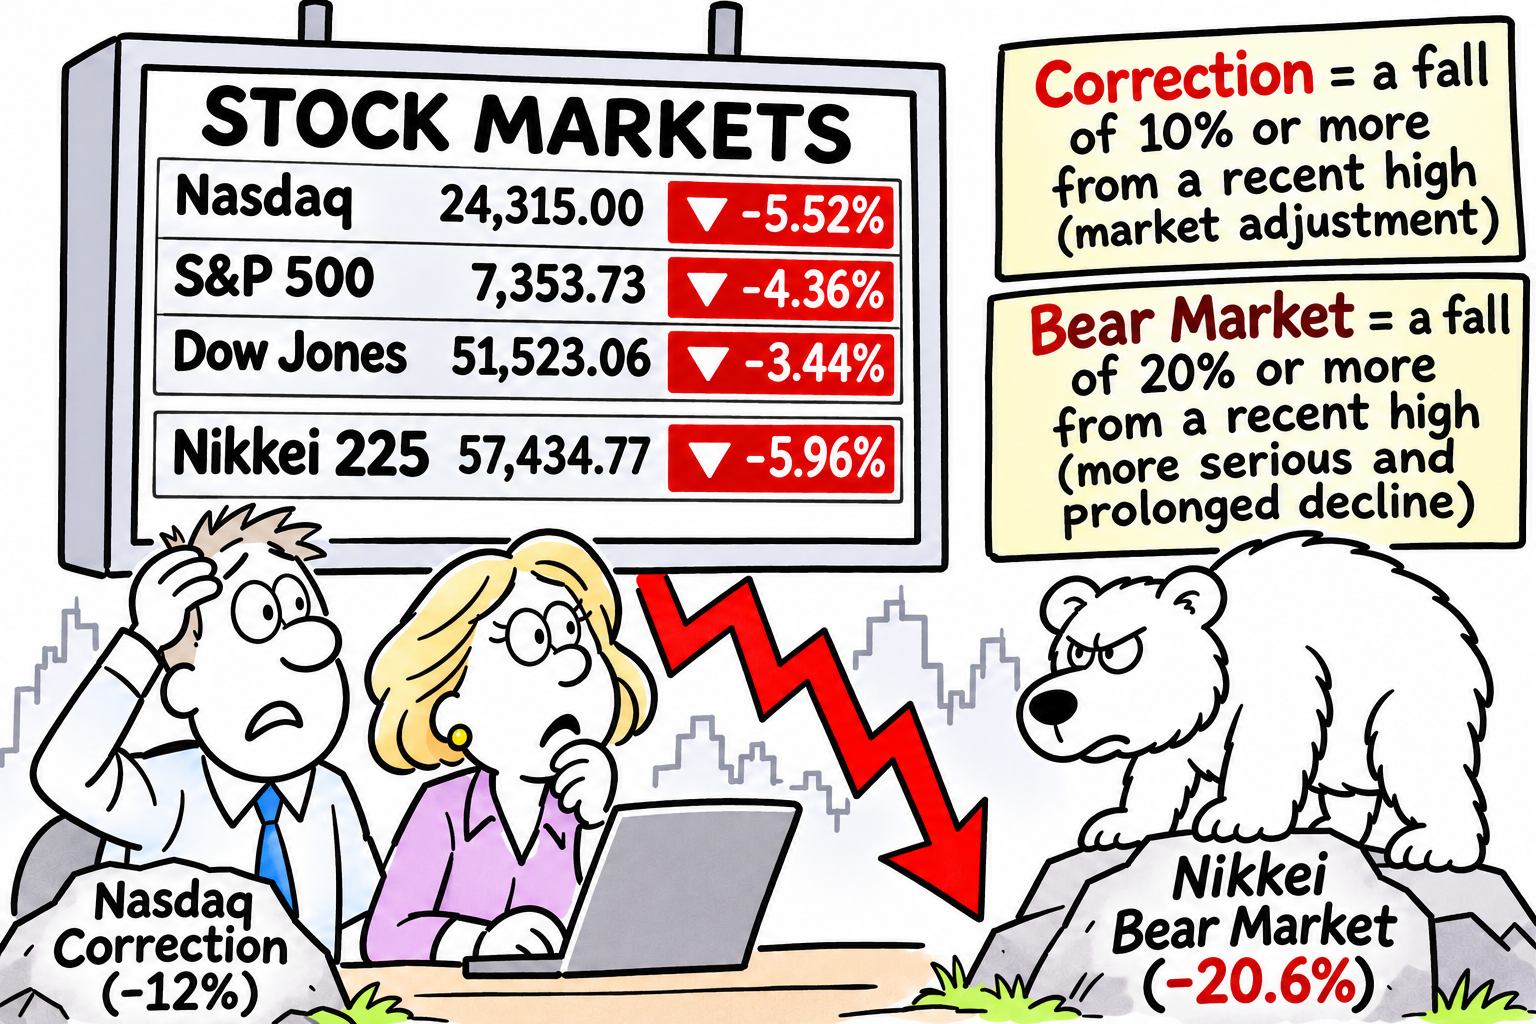
Chart showing global stock market declines, with the Nasdaq in correction and Japan's Nikkei entering bear market territory.

Wall Street has suffered one of its sharpest selloffs in recent months, sending the technology-heavy Nasdaq Composite into correction territory and triggering a fresh wave of selling across global markets.

Market turmoil spreads

The turmoil has subsequently spread to Asia, where Japan’s Nikkei 225 has fallen into bear market territory, raising concerns about the possibility of a much deeper global stock market decline.

Thursday’s trading session, 5th November 2026, was particularly brutal for American investors. The Nasdaq Composite plunged around 5.50% to close at 24,315 points, its worst single-day percentage decline since April 2025.

The index has now fallen approximately 12% from its record high reached on 6 October.

Indices

The wider American market was also heavily affected. The S&P 500 dropped 4.36% to 7,353.73, while the Dow Jones Industrial Average shed 1,833 points, or 3.44%, to finish at 51,523.06. The Russell 2000, representing smaller American companies, fell 4.45% to 2,729.89.

The technology sector was at the centre of the rout. Nvidia lost approximately 9.3%, while SanDisk plunged 22%. Semiconductor shares suffered particularly heavy losses as investors questioned whether the enormous sums being invested in artificial intelligence infrastructure would ultimately deliver sufficient returns.

Correction or bear market: what is the difference?

A stock market correction is generally defined as a decline of at least 10% from a recent peak. It is often considered a relatively normal market adjustment, particularly following a prolonged period of rising share prices.

A bear market is more serious, conventionally defined as a fall of 20% or more from a recent high. It can indicate a prolonged deterioration in investor confidence, economic conditions and corporate earnings expectations.

Japan is now experiencing the latter. The Nikkei 225, which reached a record 72,831.73 points on 22nd June 2026, fell to approximately 57,320 points during Friday’s trading. That represents a decline of more than 21% from its peak, taking the index into bear market territory.

What has triggered the sell-off?

Artificial intelligence is increasingly becoming a source of investor anxiety rather than unqualified optimism.

The enormous expenditure required to construct data centres, purchase semiconductors and secure electricity supplies has raised questions about the profitability of the AI revolution.

The recent American midterm elections have added another dimension. Democratic victories have increased concerns about potential regulatory scrutiny of technology companies and restrictions on future data-centre development.

Investors are also reassessing highly valued technology shares, taking profits and reducing exposure to companies whose valuations have become increasingly dependent on future AI growth.

Where do markets go from here?

The immediate question is whether this is a sharp but temporary correction or the beginning of something considerably more damaging.

A recovery is possible if investors regain confidence in technology earnings, AI investment and the wider economic outlook. However, continued selling could push the Nasdaq further down, particularly if major technology companies fail to justify their enormous valuations.

The danger is that weakness spreads beyond technology. Pension funds, institutional investors and other market participants exposed to falling equities could reduce their positions further, creating additional selling pressure.

Investors will also be watching interest rates, bond yields, inflation and economic growth for signs of whether financial conditions are becoming more restrictive.

For now, the warning signs are difficult to ignore. The Nasdaq is in correction territory, Japan’s Nikkei has crossed into a bear market, and confidence in the once unstoppable AI investment boom is being seriously tested.

The next few weeks could prove crucial in determining whether global markets find a floor or whether this sell-off develops into a much broader market downturn.

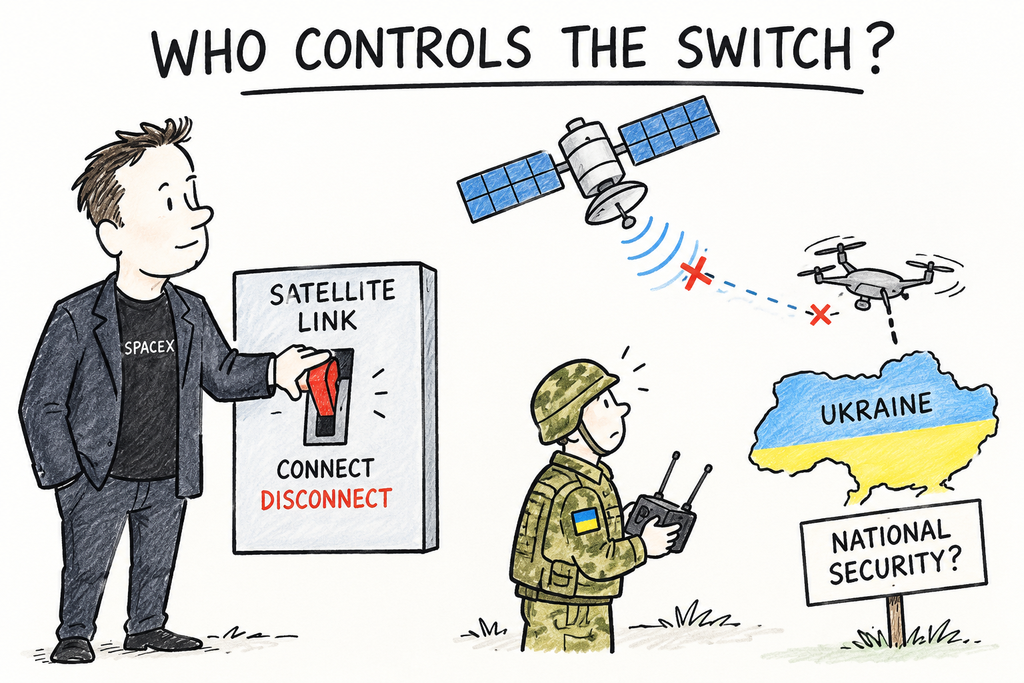
Starlink – Starshield and Ukraine: The Power to Switch Off a Nation’s Defences

Systems at war

Have Elon Musk, Donald Trump and the control of critical technology exposed a dangerous weakness in modern warfare.

Remote control decision

Imagine fighting a war for your country’s survival, only to discover that some of your most important military capabilities can be weakened by a decision taken thousands of miles away, in a boardroom or a government or by the White House for instance.

That is the unsettling question raised by the latest controversy surrounding Elon Musk’s SpaceX satellite technology, Donald Trump and Ukraine.

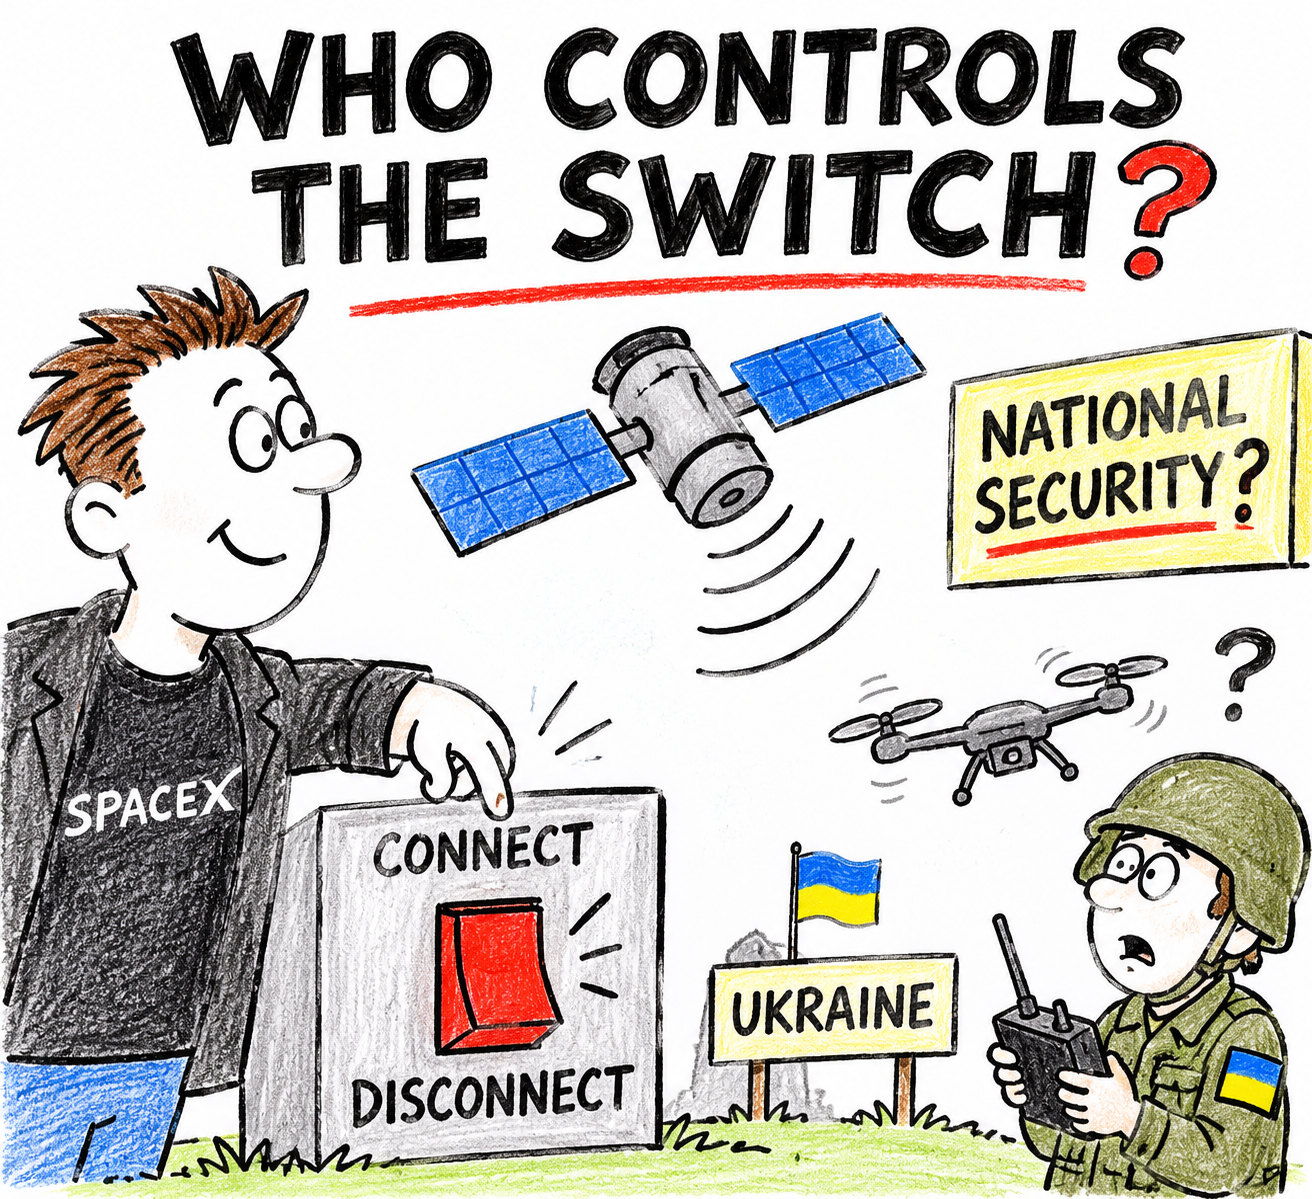
In October 2026, Ukrainian forces widely reported restrictions on their access to Starshield, the military-focused satellite communications service developed by SpaceX for the U.S. government and national-security customers.

The restrictions reportedly affected fast-moving drones, complicating Ukrainian operations against Russian forces and the interception of incoming attack drones.

Ukrainian officials reported that connectivity problems were partly resolved, but a speed restriction remained an issue.

The episode has exposed a fundamental vulnerability in modern warfare: what happens when a nation depends on technology that it does not ultimately control?

How did this happen?

Since Russia’s full-scale invasion in 2022, Starlink has become an important part of Ukraine’s communications infrastructure.

Its satellites have helped military units communicate across a battlefield where conventional infrastructure has been destroyed or disrupted.

Starshield is a separate, security-focused service, developed for government and military purposes. Although distinct from ordinary Starlink, it uses the same underlying satellite network technology.

This distinction matters because the latest controversy concerns restrictions on military-grade connectivity, not simply an ordinary household internet service being switched off.

Reports in October 2026 reportedly said that restrictions affecting terminals on fast-moving platforms disrupted Ukrainian drone operations.

A speed limit of approximately 160 kilometres per hour was reported, a significant problem for drones designed to travel faster. Ukraine said the limitations affected operations, including efforts to intercept Russian attack drones.

The question of responsibility remains contested

Reuters reported on 15th October 2026 that U.S. officials and a Western official had traced the order to limit Starshield to within the White House – this however is conjecture and unproven.

Ukrainian officials were reportedly told that the decision came from there. However, a senior U.S. official reportedly said President Trump had not requested the restriction.

Musk reportedly argued that Starshield was owned and controlled by the U.S. government, with decisions about its use resting with the American military and ultimately the president. On 16th October, Trump reportedly may have denied that he or Musk was responsible for Ukraine losing access.

Subsequent reporting, including a Wall Street Journal account cited by a U.S. Senator reportedly pointed towards Musk’s involvement and discussions with Trump and administration officials.

The precise chain of decision-making, however, has not been established publicly beyond dispute.

The important point is not to assume that one individual has been conclusively shown to have pressed a particular button. It is that the system can be restricted, and that the ability to make or authorise such a decision is concentrated in very few hands.

Why does one company have so much power?

The answer is infrastructure

SpaceX has built a vast satellite network that is difficult and expensive to replicate. Its low-Earth-orbit satellites provide connectivity in places where conventional communications networks are unavailable, damaged or vulnerable to attack.

For Ukraine, this has meant access to a capability that would otherwise have been extremely difficult to establish during wartime.

But dependence creates leverage.

A country can possess tanks, aircraft, missiles and trained soldiers while remaining dependent on an outside provider for the communications that make those assets effective.

If that connection is interrupted, the equipment may still exist, but its usefulness can diminish.

This is the distinction between owning the weapons and controlling part of the system that enables them to operate.

Musk does not personally need to command Ukrainian troops or decide which targets they attack. The ability to influence a critical communications service can itself confer considerable strategic power.

Nor does the system necessarily require a dramatic, total shutdown. A restriction on speed, coverage, access or functionality may be sufficient to undermine a particular military operation.

A technical adjustment can have consequences far beyond the software setting that produced it.

Where does Donald Trump fit into this?

The controversy also illustrates the power of the American presidency.

The United States is a major customer of SpaceX’s national-security services, and Starshield operates within a government defence framework.

Washington therefore has an important role in determining how those capabilities are supplied and used.

Trump’s administration also has substantial influence over American military assistance, intelligence sharing and the wider relationship with Ukraine.

At a time of deteriorating relations between Washington and Kyiv, the reported restrictions raised questions about whether technology access could become part of the political leverage exerted over Ukraine.

The timing is notable, but timing alone does not prove the motive behind the decision.

There are two distinct forms of power here.

Musk and SpaceX possess technical expertise, infrastructure and the ability to implement changes to services they operate.

The U.S. government possesses contractual, military and political authority over the government-controlled elements of the arrangement.

Where these powers intersect, the practical consequences for Ukraine can be immediate, even if the formal decision-making process remains opaque.

That is the real concern: a nation’s battlefield capabilities may be affected by a handful of decisions made outside its borders, without the nation itself having an effective veto.

Is this democratic accountability?

In a democracy, decisions about war and peace are supposed to be subject to public scrutiny, institutional checks and political accountability.

Yet critical digital infrastructure increasingly sits between governments and the people they serve.

A private company may be accountable to its shareholders, its contractual obligations and the laws of the country in which it operates. A president is accountable through political and constitutional institutions.

But neither arrangement automatically ensures that an allied nation dependent on the technology will receive adequate warning, consultation or protection against sudden disruption.

The problem is not simply whether Musk or Trump has acted appropriately. It is whether the safeguards are sufficient when the consequences extend to another country’s soldiers and civilians.

If an allied military depends on a commercial or government-controlled system, who decides when access can be restricted? What emergency procedures apply?

Must the affected country be notified? Can a single executive decision override established military planning? And who is accountable if the consequences are disastrous?

These are questions of governance, not merely technology.

People die!

What happens if the switch is turned off?

Ukraine cannot instantly build a replacement for a sophisticated satellite network. Alternative providers, including Europe’s OneWeb and developing satellite services from other companies, may offer options, but integrating them into military operations requires time, equipment, money and testing.

A robust defence therefore requires more than finding another supplier after a crisis begins.

Governments must consider redundancy, alternative communications systems, interoperable equipment and contingency plans. They must also examine the terms under which private companies provide services essential to national security.

The United States faces a related problem of its own. If American forces become heavily dependent on one provider, the same concentration of control could create vulnerabilities for U.S. operations in a future conflict.

This is why the episode has prompted scrutiny in Washington, including a congressional inquiry into SpaceX’s role and the government’s dependence on its technology.

The lesson extends far beyond Ukraine

Satellite communications are only one example. Similar questions arise wherever essential services depend on concentrated technological control: cloud computing, artificial intelligence, digital payment systems, communications networks and critical software.

The more indispensable a system becomes, the greater the potential influence of whoever controls access to it.

That influence need not be exercised maliciously. A legitimate security decision, a contractual dispute, a technical failure or a change in political priorities could all have serious consequences.

The danger lies in building national capabilities around a system that can be altered without sufficient safeguards. Any country could be affected.

Ukraine’s experience raises a difficult question for every government: can a nation genuinely be sovereign if essential elements of its defence depend on decisions made by a small number of people outside its control?

The answer cannot simply be to abandon private technology. Such systems can provide extraordinary capabilities that governments would struggle to develop independently.

But convenience and efficiency must be balanced against resilience and accountability.

The Power is ALL in one hand

In modern warfare, power no longer rests solely with those who possess the weapons. It can also rest with those who control the networks, software and infrastructure that make those weapons effective.

These too could be deemed part of the weapons network.

And sometimes, the most consequential weapon is not a missile or a tank.

It is the ability to decide who remains connected — and who does not.

Bank of England Holds Interest Rate at 3.75%

Bank of England holds rate

The Bank of England has held interest rates at 3.75% on 17th September 2026 but warned that persistently high energy costs could force rates higher.

The Monetary Policy Committee voted 6-3 to keep Bank Rate unchanged, while three members backed an increase to 4%.

Governor Andrew Bailey reportedly said the outlook remained uncertain, with rising energy prices creating renewed inflationary pressure.

UK inflation reached 3.1% in August 2026 and the Bank expects it to rise further, potentially exceeding 4% in early 2027 if energy costs remain elevated.

Bailey reportedly said that if the Middle East conflict persists and inflationary risks increase, monetary policy may need to tighten.

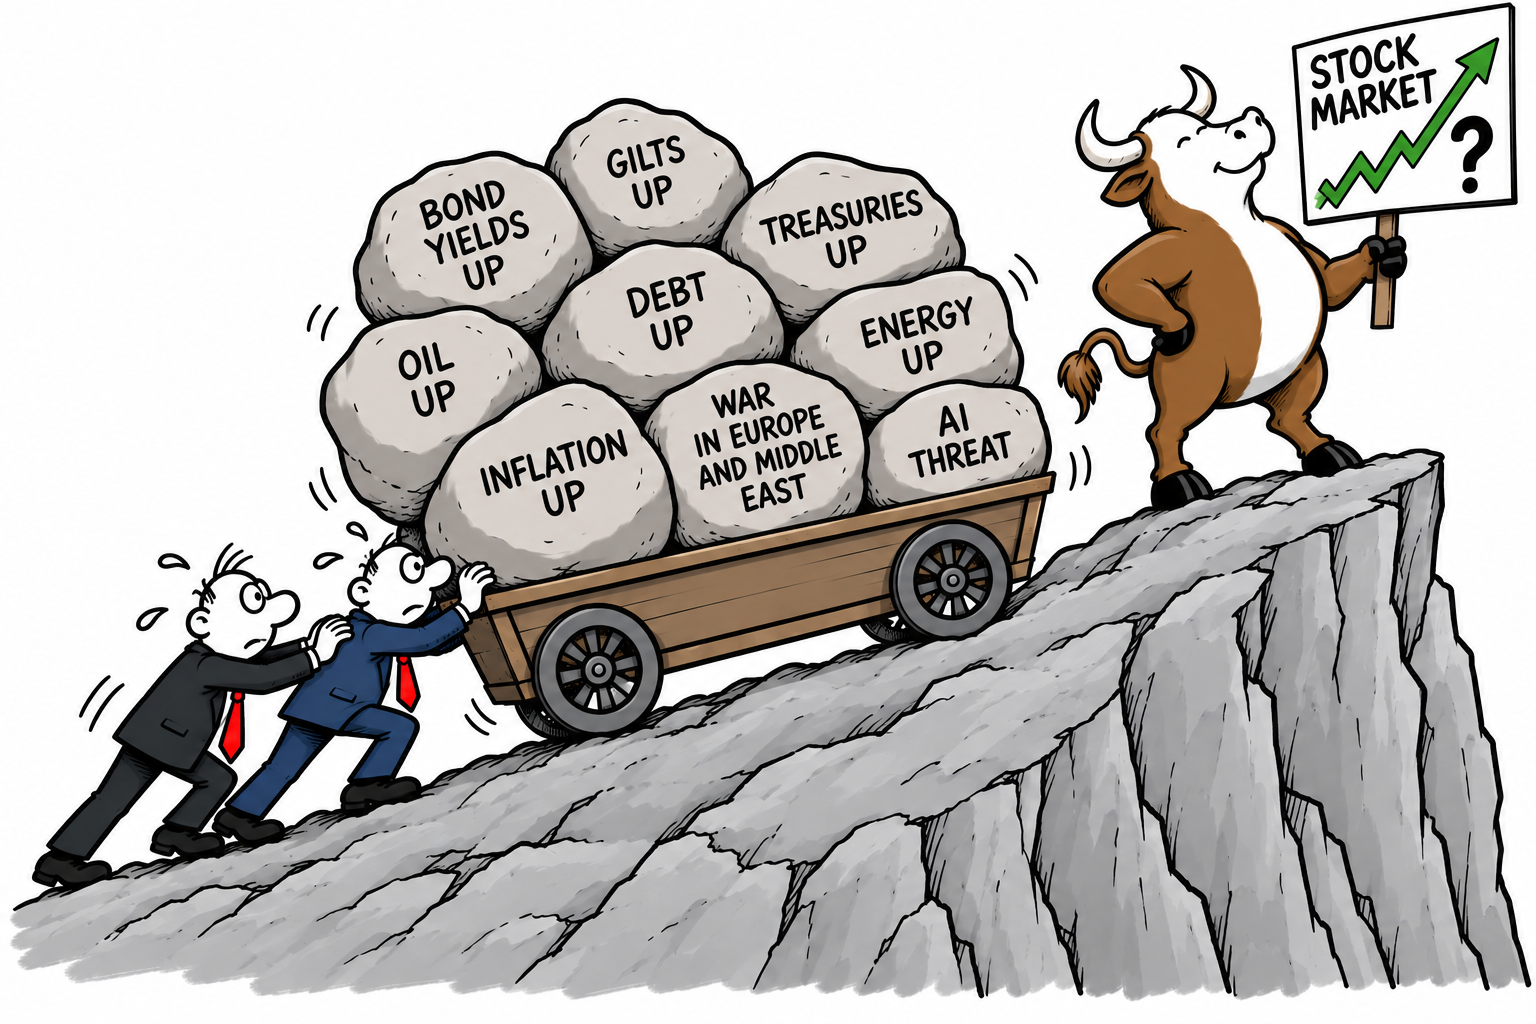
Why Won’t the Stock Market Correct – Especially with all the Issues Facing it?

Stock Market Correction Soon?

There was a time when any one of these developments would have been enough to frighten investors: rising government bond yields, higher borrowing costs, stubborn inflation, soaring oil and energy prices, mounting government debt, war in Europe and the Middle East and tariff wars.

And now with the growing threat of AI safety and concerns about whether the enormous investment in artificial intelligence can continue at its current pace.

Put them all together and, logically, the stock market should be facing a serious test.

Yet it continues to demonstrate remarkable resilience.

Irony

The irony is that many of these pressures are already showing up in financial markets. U.S. Treasury yields have moved above 5%, their highest levels since 2007, while oil has climbed above $100 a barrel.

Rising energy prices are feeding inflation concerns, while higher yields are increasing the cost of borrowing. Reuters reported on Tuesday that the Dow, S&P 500 and Nasdaq all fell, but the declines remained relatively contained.

So why hasn’t this combination produced a much larger correction?

One explanation is that markets are not simply pricing today’s problems. They are pricing what investors believe the world will look like several months or years from now – or so we are told.

Corporate earnings remain a powerful counterweight. If profits continue to grow rapidly, investors can tolerate higher interest rates and higher valuations for longer.

Reuters notes that continued earnings growth and enthusiasm surrounding AI have helped keep U.S. equities relatively resilient despite the rise in Treasury yields.

There is also an extraordinary amount of money invested in equities. Pension funds, investment funds, corporations and individual investors cannot simply abandon shares every time the economic outlook deteriorates.

There are relatively few places capable of absorbing enormous amounts of capital.

Don’t sell – carry on regardless

And perhaps most importantly, investors have repeatedly learned that selling during every crisis can be expensive.

Inflation? The market survived it.

War? Markets have survived wars before – but markets did correct.

Tariffs – markets have shrugged there off!

Higher interest rates? Markets can rise during tightening cycles if the economy and corporate profits remain strong.

Oil shocks? They can damage consumers and businesses, but they can simultaneously boost the profits of energy companies.

Even the AI problem is complicated. A slowdown in AI investment could hurt some enormously valued technology companies, but it would not necessarily destroy the entire economy.

Indeed, markets have already shown that AI concerns can cause sector-specific selling without automatically triggering a broad collapse.

The real question, therefore, may not be why the market hasn’t fallen.

It is what would finally make investors collectively stop believing that the next problem can be absorbed?

Because markets rarely collapse simply because there are lots of problems.

They collapse when investors suddenly decide that those problems can no longer be ignored.

Stock market offers ‘easy money’?

It certainly sounds like easy money — if only markets worked that way. The danger is assuming that resilience means invincibility: a market can shrug off one problem, then another, and even several simultaneously, right up until investors collectively decide that earnings, valuations, interest rates or economic growth no longer justify the prices they are paying.

Until that moment arrives, bad news can simply be absorbed, explained away or declared temporary; when it does arrive, however, the same market that seemed capable of ignoring everything can suddenly discover that everything matters after all.

Difficulty


The difficult part is that there is no reliable way to say when it will happen — markets can remain expensive and resilient for considerably longer than economic logic might suggest.

The eventual correction is more likely to come when several pressures stop being viewed as temporary or manageable and begin to undermine the assumptions supporting corporate earnings and valuations: persistently high inflation, materially higher borrowing costs, weaker growth, falling profits, an AI investment slowdown, or an unexpected financial shock could each become the catalyst.

Until investors collectively change their expectations, the market can continue climbing despite an increasingly uncomfortable list of warning signs — but resilience should not be confused with immunity.

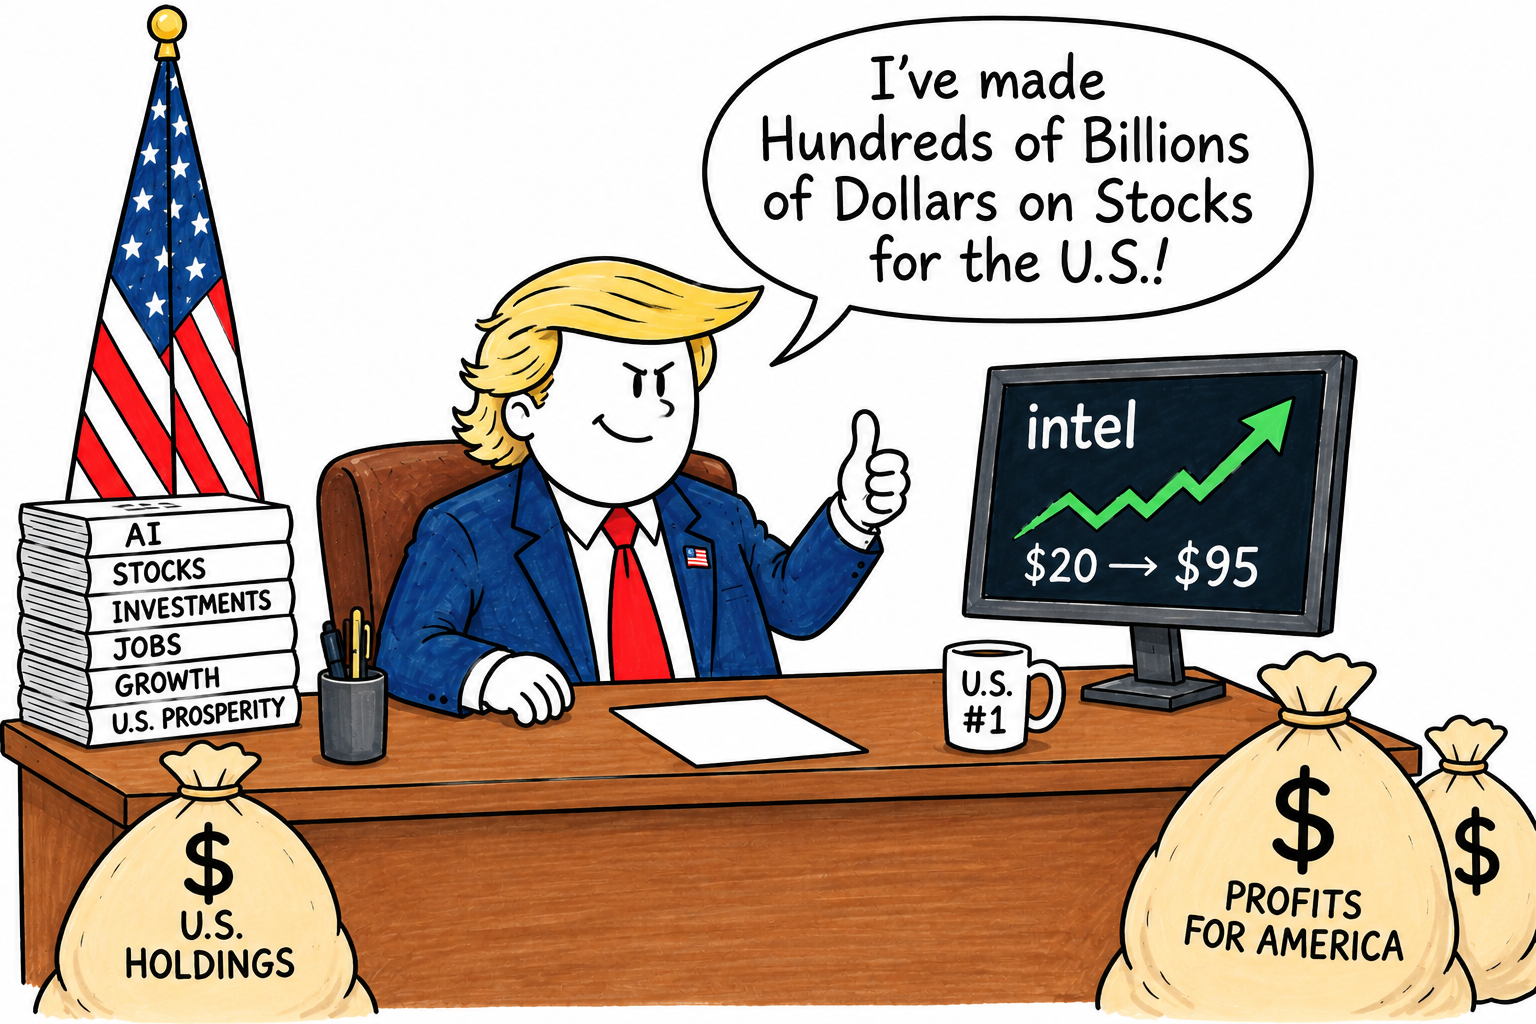
Trump Reportedly Claims ‘Hundreds of Billions’ Made for America Through Stocks

President Donald Trump has claimed he has made “Hundreds of Billions of Dollars” for the United States through stocks and other holdings, as part of a remarkable stream of AI-generated posts published on Truth Social.

Trump offered no detailed calculation to support the figure, or explanation of how the alleged gains should be measured.

Intel inside

His claim came alongside an AI-generated image depicting him sitting at the Resolute Desk, apparently trading stocks, with screens showing an investment in Intel rising from $20 to $95.

The Intel reference is particularly striking. Intel shares closed at $95.80 on Friday, having risen dramatically from their 52-week low.

The U.S. government acquired a 9.9% stake in the chipmaker in August 2025 at $20.47 a share, giving the government’s holding a substantial unrealised gain as the stock has climbed.

Scrutiny

Trump’s wider stock-market involvement has nevertheless attracted scrutiny. An analysis of his financial disclosures and Truth Social activity found instances in which purchases of individual companies were made shortly before he publicly praised their shares.

Trump has maintained that his investment accounts are independently managed, while he has not placed his assets in a traditional blind trust.

The president’s latest claim therefore raises an important distinction between gains on paper, gains made by government holdings and money actually generated for the U.S. Treasury.

Invest

A rising share price can increase the value of an investment without producing cash for the government.

The extraordinary claim also arrived during a day-long flood of AI-generated imagery and political messages from Trump, highlighting how increasingly central artificial intelligence has become to his social-media communication.

For investors, the episode is another reminder that presidential commentary can itself become a market-moving force — particularly when it singles out individual companies or assets.

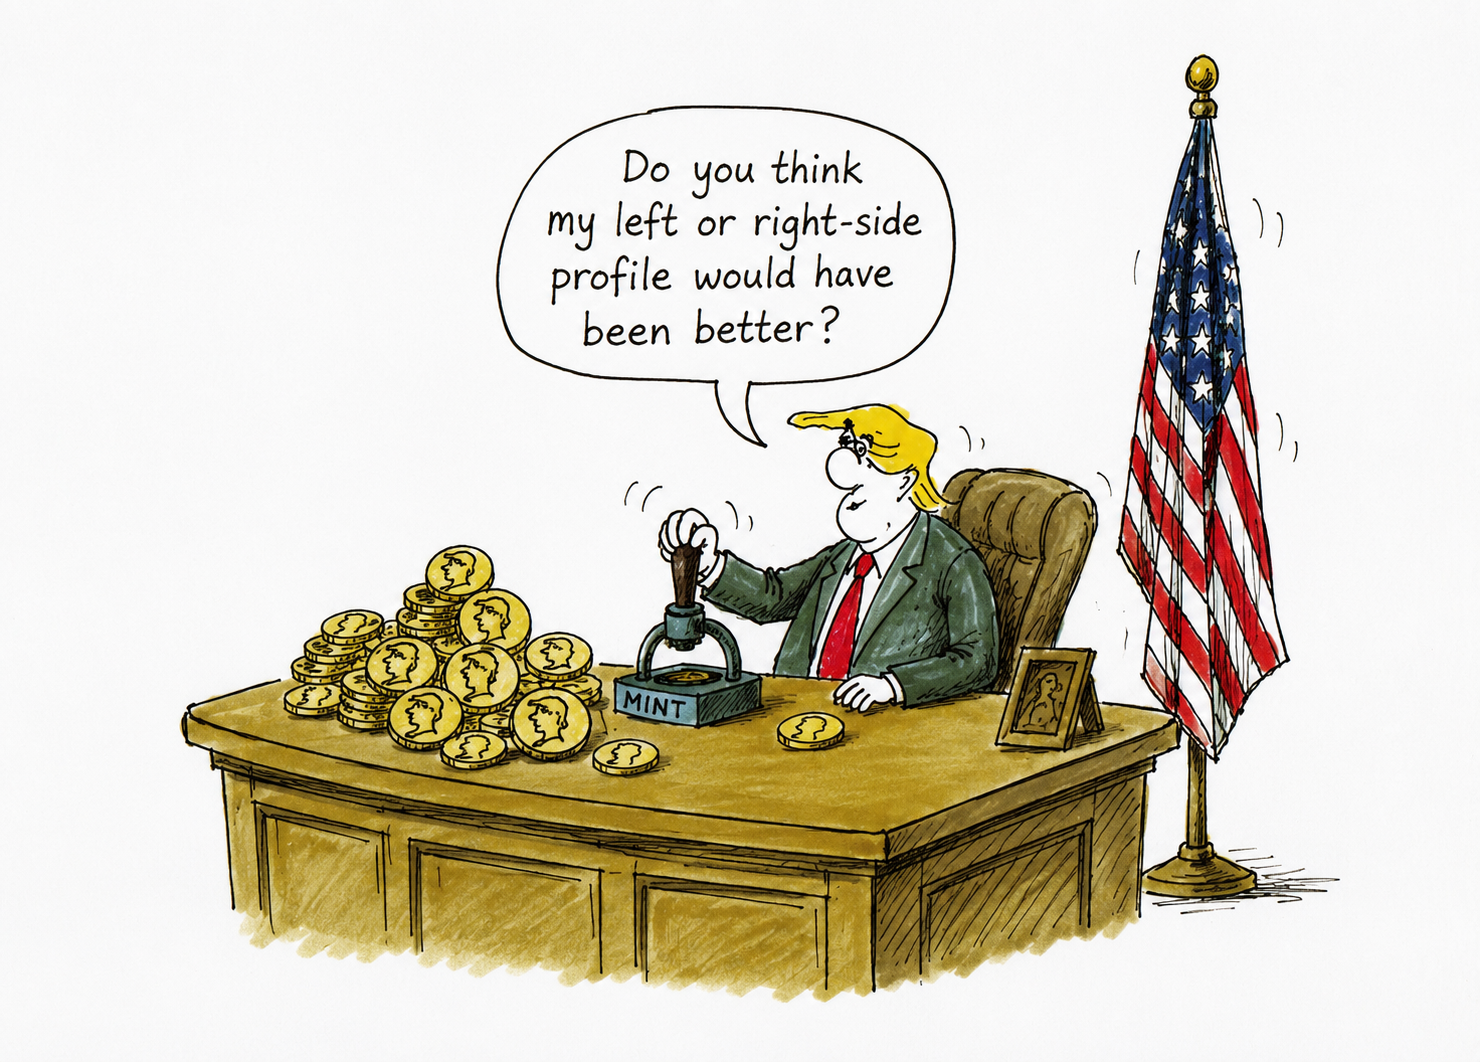
One in a Hundred – Trump puts his Head on a Coin

Minting a new U.S. coin

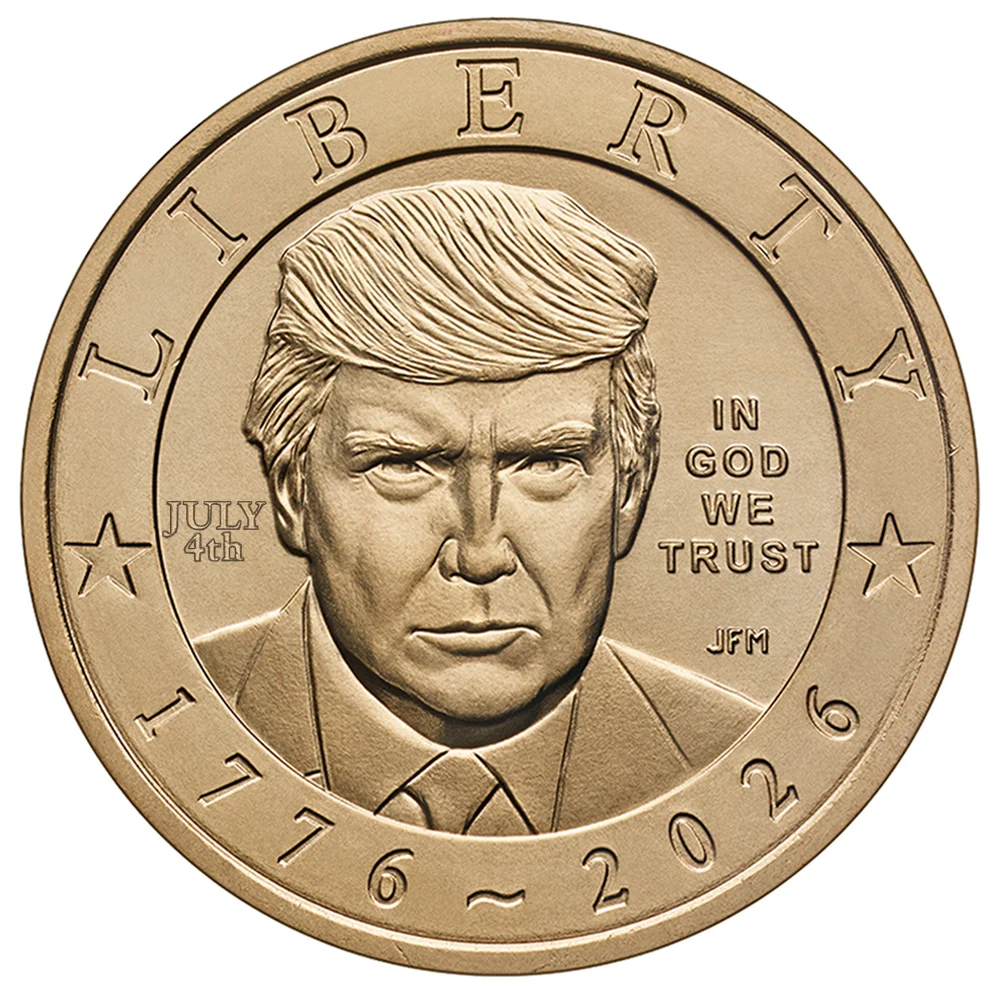
Donald Trump has become the first living U.S. president in almost a century to appear on American currency, after the U.S. Mint released a new $1 coin bearing his portrait.

The coin, launched on 2nd September 2026, commemorates America’s 250th anniversary and is intended to enter circulation as well as appeal to collectors.

False idols

Trump’s image appears on the front alongside the words “LIBERTY”, “IN GOD WE TRUST” and “1776 ~ 2026”. The reverse features the Presidential Seal, including the eagle, olive branch and arrows. Despite its golden appearance, the coin contains no actual gold.

The decision is controversial because American tradition has strongly discouraged depicting living people on the nation’s money.

The new Trump $1 coin

The only previous living president to appear on U.S. coinage was Calvin Coolidge, whose image featured on a commemorative half-dollar in 1926, marking the 150th anniversary of American independence.

Political self-promotion?

The Trump administration argues that legislation passed in 2020 provides the necessary authority for the special anniversary coin.

Critics, however, question whether this represents an inappropriate departure from established safeguards against political self-promotion.

With Trump’s face now literally in Americans’ pockets, the coin represents more than a collectors’ novelty. It is another striking example of how the boundaries between presidential power, personal branding and national symbolism are being tested.

Trump’s Portfolio Shuffle Raises Questions About Presidential Investing

Market trader

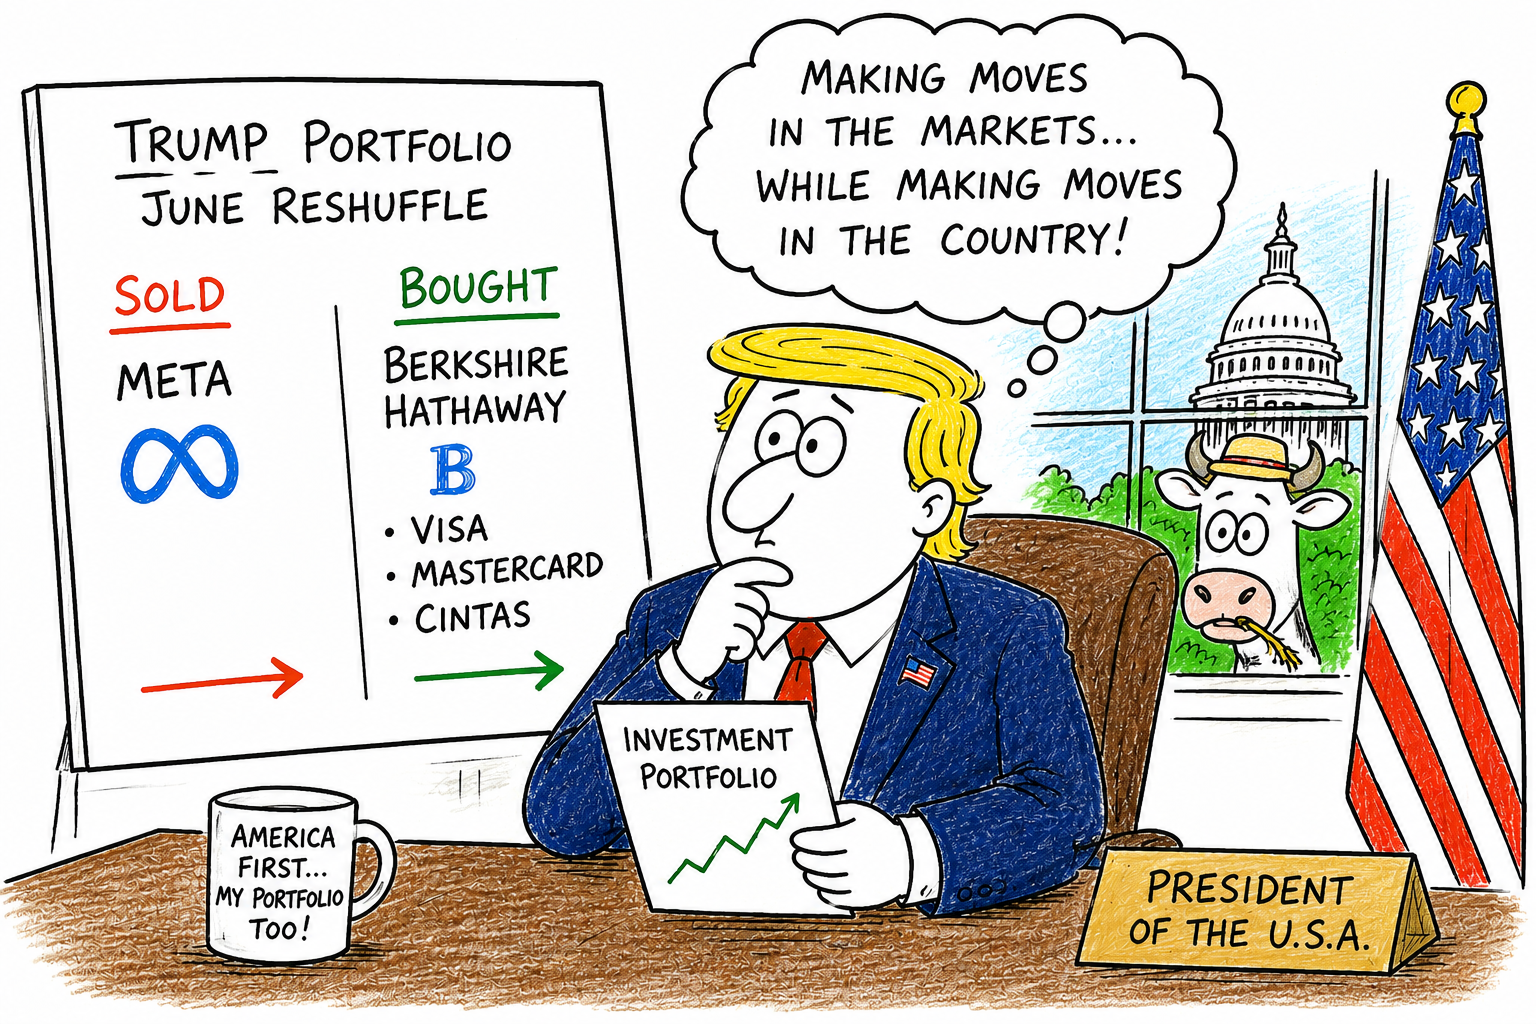
President Donald Trump’s latest financial reported disclosure has provided an unusual glimpse into the investment activity of a sitting U.S. president, reportedly revealing more than 1,000 securities transactions during June 2026.

The filing, published on 22 August, shows trades worth between $78.1 million and $263.1 million, although the disclosure rules provide ranges rather than exact figures.

Meta shares

Among the most notable moves was the sale of between $1 million and $5 million of Meta shares on 18th June 2026. On the same day, Trump bought between $1 million and $5 million of Berkshire Hathaway, as well as similarly sized positions in Visa, Mastercard and Cintas.

He subsequently sold a smaller amount of Berkshire and later bought more Meta, illustrating just how actively the portfolio was being managed.

Scale

The scale of the activity is remarkable. Trump made more than 21,000 securities trades during 2025, with transactions valued between $600 million and $1.86 billion.

The latest figures therefore raise a broader question: should a president be actively exposed to individual companies and financial markets while occupying one of the world’s most influential political positions?

The potential conflict-of-interest issue is particularly sensitive because presidential decisions can directly affect businesses and markets through tariffs, regulation, government contracts, monetary-policy appointments and foreign policy.

Even when there is no evidence that investment decisions are influenced by political information, the appearance of a conflict can undermine public confidence.

Zero conflict?

The White House argues that there is no conflict because Trump’s investments are held in discretionary accounts managed independently, using computer-based strategies that replicate recognised market indices.

Trump and his family are reportedly unable to direct or influence individual trades.

Nevertheless, the controversy highlights an uncomfortable question for modern democracy: is independence enough, or should presidents and leaders be held to an even higher financial standard simply because of the extraordinary power they possess?

Deal or No Deal – The President of The United States and his Team Tease an Iran Deal, Markets Soar — Again. And Then Nothing. Why Does This Keep Happening?

Deal or no deal?

It has become an increasingly familiar pattern: Donald Trump hints that an agreement with Iran is close, investors breathe a sigh of relief, oil prices fall and stock markets jump — only for the promised breakthrough to fail to materialise. Why?

Deal or no deal

This week (early-August 2026) was another example. Trump and members of his administration suggested that progress towards an agreement involving Iran and the Strait of Hormuz could come within days.

Markets responded enthusiastically, betting that a deal would reduce the risk of prolonged conflict and ease pressure on global energy supplies.

Yet no comprehensive agreement appeared. Iran subsequently said direct talks with Washington would not take place while it considered the existing interim arrangement to be breached.

So why does it keep working?

Because financial markets trade expectations, not facts. The possibility of peace is enormously valuable when war threatens oil supplies, inflation and global growth.

Algorithms and traders react within seconds to headlines containing words such as “deal”, “ceasefire” or “agreement”.

Oil falls, equities rise and the economic relief can be priced in long before diplomats have actually agreed anything.

Loop of distrust

There is also a dangerous feedback loop. If markets repeatedly reward optimistic statements, there is little immediate financial incentive for politicians to stop making them.

Reports have previously documented dozens of occasions on which Trump suggested an Iran agreement was imminent without a final deal emerging.

Unhealthy relationship

That does not prove deliberate market manipulation. But it does expose a deeply unhealthy relationship between political rhetoric and financial markets.

Peace should be based on verified agreements, not carefully timed hints.

When a presidential statement can erase billions of dollars of perceived risk from markets before a single binding document exists, investors are effectively trading political promises.

And when those promises repeatedly fail to arrive, the credibility of both the politician and the market reaction suffers.

Shouldn’t markets price reality?

Not headlines. And certainly not hype.

Can U.S. markets ever fail… I wonder?

The Great Social Truth Manipulation

The Art of Manipulation

There is an old saying apparently that if you create a problem, you can then claim credit for solving it.

Whether that saying is fair in every circumstance is open to debate, but it raises an uncomfortable question about the way modern politics is increasingly presented to the public.

Every day we hear another announcement that “a deal is close”, “talks are progressing” or “a breakthrough is expected”. These headlines are designed to sound reassuring. They suggest that leaders are successfully navigating a difficult situation.

But what if we are asking the wrong question?

Perhaps we should not be asking whether another deal is close. Perhaps we should be asking why the deal has become necessary in the first place.

That is where the irony begins.

Take the current tensions involving the United States and Iran. The public is repeatedly encouraged to view the next agreement as a diplomatic success.

Yet before the military confrontation, there was already diplomacy. The Strait of Hormuz was open. Oil continued to flow. The world’s attention was focused on preventing escalation rather than recovering from it.

Today, after military action, regional instability and renewed fears over global shipping and energy supplies, we are told that another agreement will represent progress.

But is it progress?

Or is it simply an attempt to restore what already existed?

That distinction is rarely discussed.

Instead, public attention is directed towards the negotiations themselves.

Every meeting becomes news.

Every statement hints at a breakthrough.

Every possible agreement is presented as evidence that events are moving in the right direction.

The irony is that the benchmark has quietly changed.

Yesterday, stability was taken for granted. Today, merely returning to that same level of stability is presented as a diplomatic triumph.

This is how truth manipulation often works.

It does not necessarily rely upon telling outright lies. Instead, it changes the point from which people measure success.

Once the public stops comparing today’s position with where events began, and starts comparing today’s headlines with yesterday’s headlines, perceptions change. Recovery begins to look like achievement.

That is an extraordinarily effective political technique.

It shifts the conversation away from asking whether earlier decisions improved the situation and towards celebrating efforts to repair the consequences.

The public becomes invested in the next deal rather than reflecting upon whether the circumstances requiring that deal could have been avoided.

This is not an argument against diplomacy. Quite the opposite. Negotiation should always be preferred to conflict wherever possible.

Nor is it a claim that every crisis is avoidable. International affairs are rarely that simple.

The real issue is whether governments should be judged by the number of deals they announce or by whether their decisions leave the world in a better position than before.

That is the question often left unasked.

Perhaps the greatest social truth manipulation is persuading people to celebrate returning to yesterday’s starting point while calling it tomorrow’s success.

This pattern is hardly unique to one administration or one country. Governments throughout history have sought to frame events in ways that favour their own decisions.

However, democratic societies rely upon citizens asking a simple but essential question:

Are we genuinely better off than we were before?

Trump’s Latest Tariff Onslaught Marks a new Strategic Gameplay

Trump Tariff Storm

President Donald Trump’s newest tariff onslaught is not simply a reprise of his earlier trade offensives; it represents a structural shift in how the White House intends to wield tariffs as a long‑term economic instrument.

The administration has imposed fresh duties of 10% to 12.5% on 60 trading partners, including the EU, China, the UK and Canada.

Unlike the shock‑and‑awe “Liberation Day” tariffs of 2025, this latest round landed with muted market reaction — not because the measures are trivial, but because the global backdrop has changed dramatically.

Compounding Inflation

The defining difference is context. Markets are already strained by a prolonged US–Iran conflict, an energy shock pushing oil above $100, and persistent supply chain bottlenecks.

In this environment, tariffs no longer arrive as a standalone geopolitical gambit; they compound existing inflationary pressures and reinforce expectations of slower global growth.

Analysts warn that the combination of conflict‑driven uncertainty and renewed trade barriers could entrench a low‑growth, high‑inflation regime.

U.S. Supreme Court

The legal foundation has also shifted. After the Supreme Court struck down earlier tariffs, the White House has pivoted to Section 301 of the Trade Act of 1974, citing forced labour concerns.

This move removes the legal vulnerability that previously allowed courts to intervene. As a result, markets must now treat tariffs not as temporary negotiating tools but as potentially permanent features of U.S. economic policy.

Tariff battleground

Investment strategists suggest that other nations may respond cautiously at first, delaying escalation until the full impact becomes clearer.

Yet the broader implication is unmistakable: Trump’s tariff strategy has evolved from episodic salvos into a durable framework.

With the Federal Reserve now weighing the inflationary effects of rising oil prices, the tariff onslaught arrives at a moment when global markets can least absorb additional strain.

Trump pauses military strikes on Iran apparently to allow peace talks to resume – let’s see what happens this time.

Trump Tinkers with U.S. Football Team World Cup Red Card -as Decision Overturned

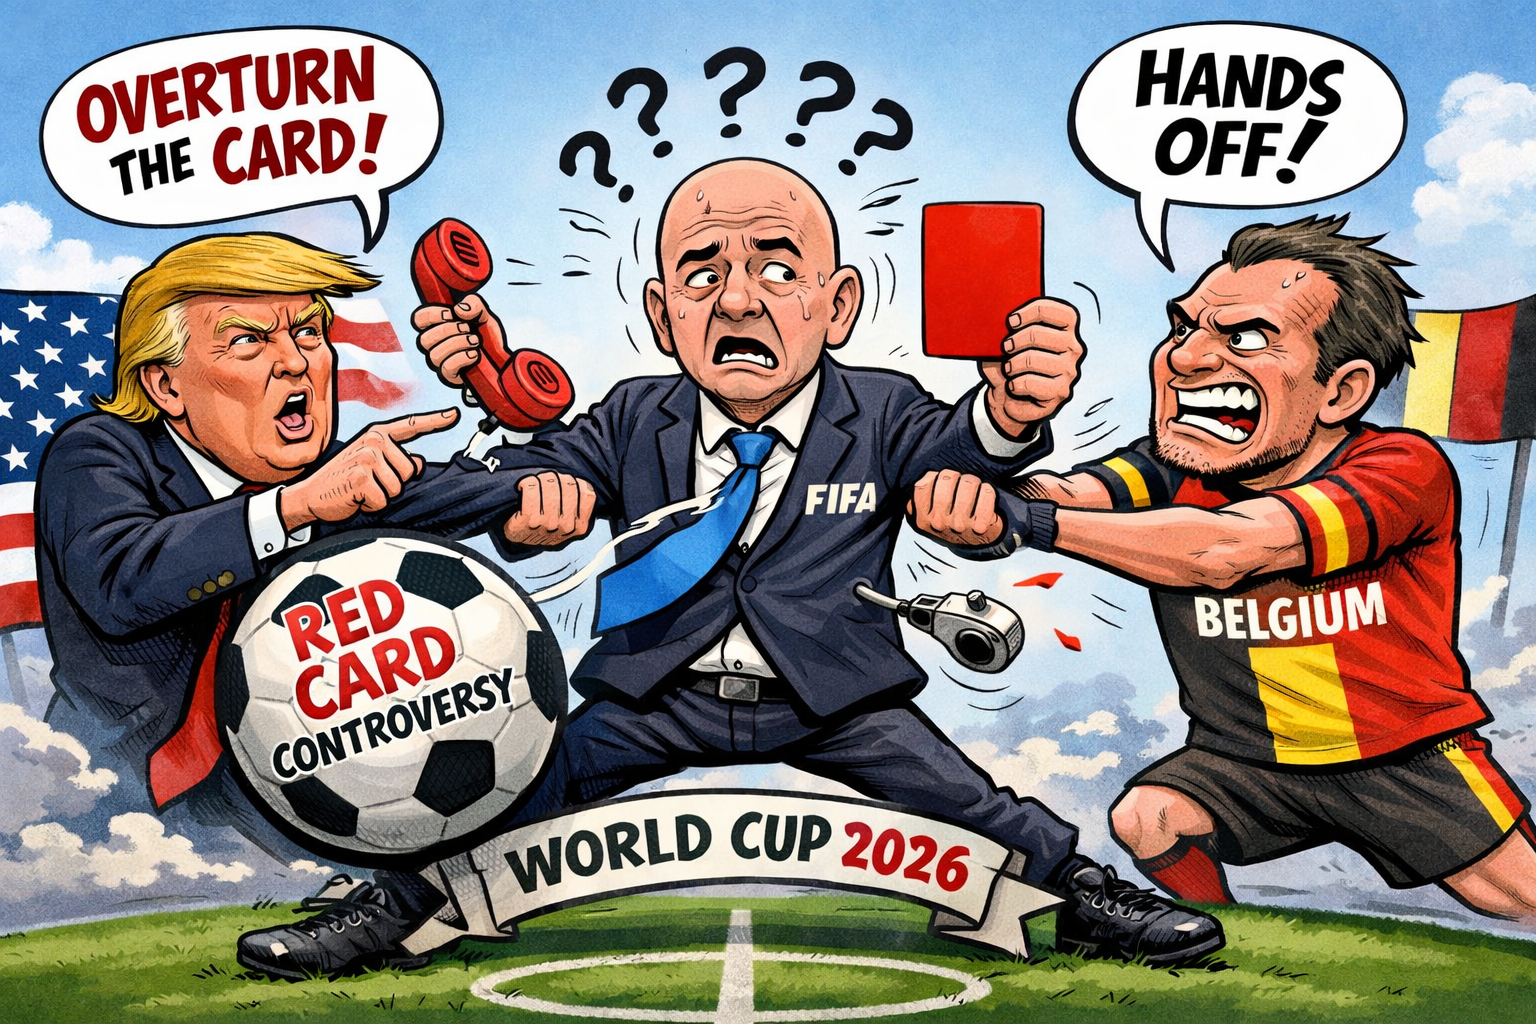
FIFA World Cup Decision Intervention

FIFA’s decision to suspend Folarin Balogun’s automatic one‑match ban has already become one of the most contentious moments of this World Cup.

The governing body is reported to have invoked Article 27 — a rarely used discretionary clause — to overturn a red‑card suspension for the first time in more than six decades.

Intervention?

Yet the real flashpoint is not the ruling itself, but the reported intervention of President Donald Trump, who personally phoned FIFA President Gianni Infantino to request a review of the incident.

Whether that intervention was justified depends on how one views the boundaries of presidential influence. On one hand, Trump’s defenders argue that he simply sought clarity on a decision that appeared harsh, especially given concerns about the referee’s reliance on slow‑motion replay.

They frame it as a leader advocating for a citizen — and a national team — during a tournament the United States is co‑hosting. From that perspective, the call was an assertive but legitimate act of representation.

Negotiable?

On the other hand, critics see something far more troubling: a head of state leaning on an international sporting body to alter a disciplinary outcome that should rest solely on the laws of the game.

Belgium’s astonishment, and its immediate move to appeal, reflects a wider unease about political pressure intruding into the supposedly neutral domain of officiating.

Once presidents start phoning refereeing authorities, the integrity of sport begins to look negotiable.

Ultimately, the question is not whether Balogun should play — reasonable people can disagree on the red card itself — but whether the process should ever bend to presidential intervention.

For many, this episode feels less like rightful advocacy and more like an overreach that risks eroding trust in global sport.

U.S. jobs market cools in June

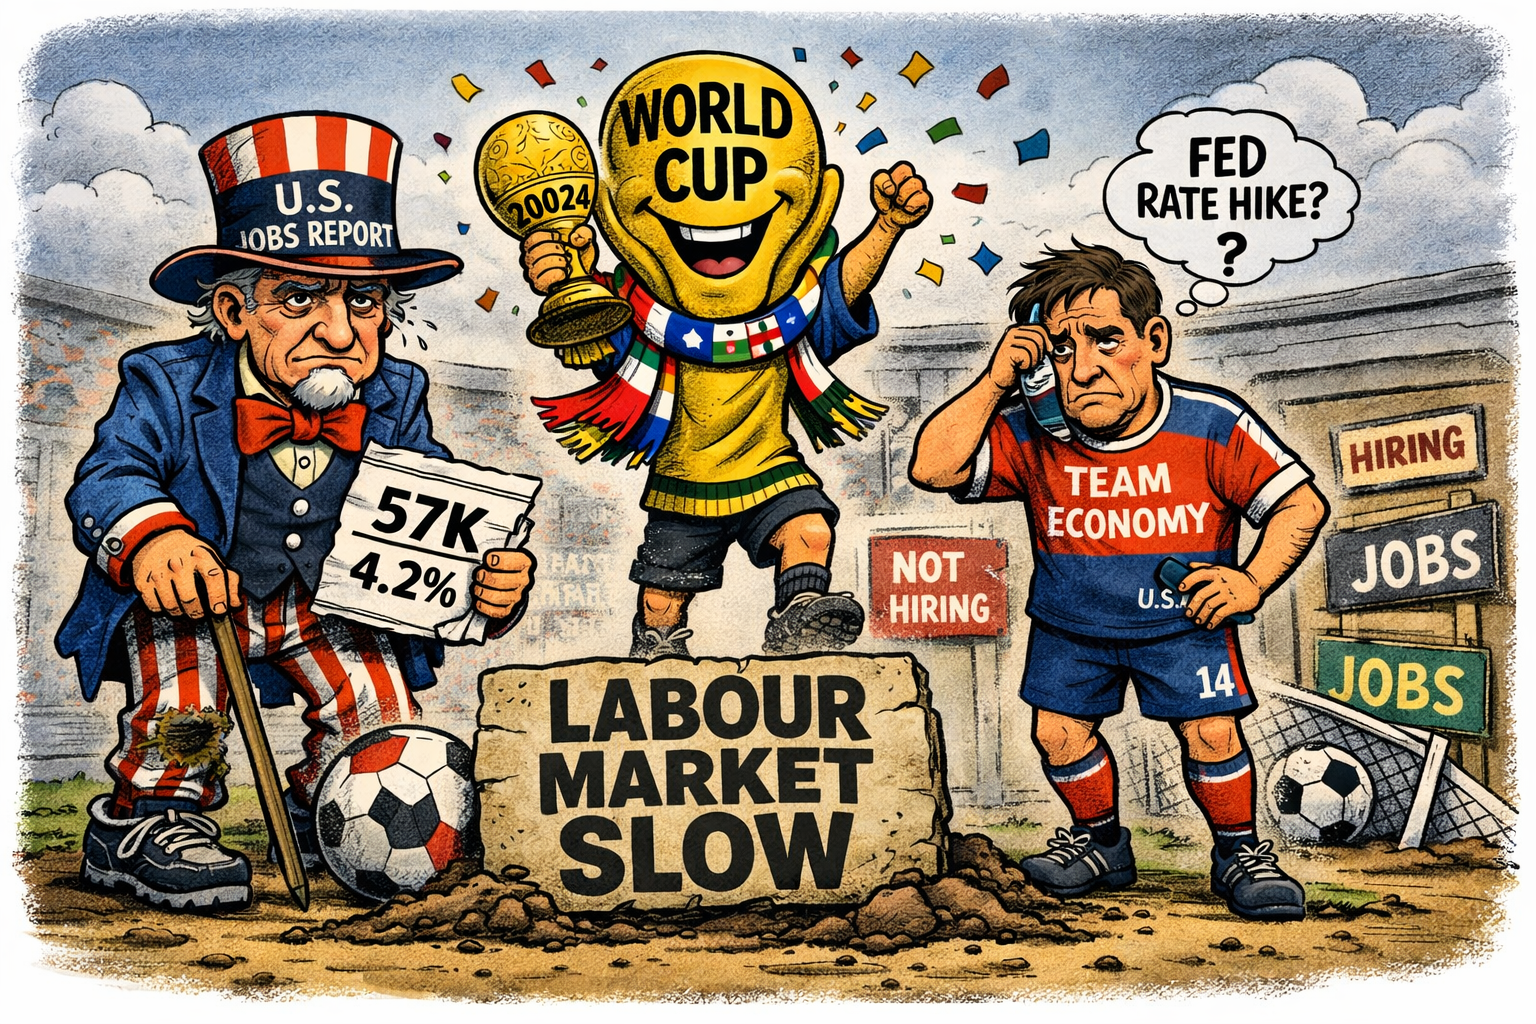
Hiring slows for the U.S. in June 2026

The latest U.S. jobs report underscored a clear cooling in labour market momentum, with June’s 2026 nonfarm payrolls rising by just 57,000, well below economists’ expectations and marking the weakest gain in four months.

And this despite an expected job boost as the U.S. hosts a highly successful record-breaking Football World Cup.

Although the headline unemployment rate dipped to 4.2%, this improvement was largely cosmetic: the labour force participation rate fell to 61.5%, its lowest level since March 2021, meaning fewer people were counted as actively seeking work.

Beneath the surface, the household survey painted a more troubling picture. Employment dropped sharply, with 507,000 fewer people reporting they were at work, and revisions to earlier months erased 74,000 previously reported jobs — undercutting the narrative of springtime strength.

Leisure and hospitality suffered a notable setback, shedding 61,000 positions, while gains were concentrated in a narrow band of sectors: professional and business services (+36,000), social assistance (+25,000), and healthcare (+22,000).

Financial markets reacted cautiously, with investors trimming expectations of a Federal Reserve rate rise in September 2026.

Overall, the data reportedly suggests a labour market losing steam, shaped more by statistical quirks and workforce exits than by genuine economic resilience.

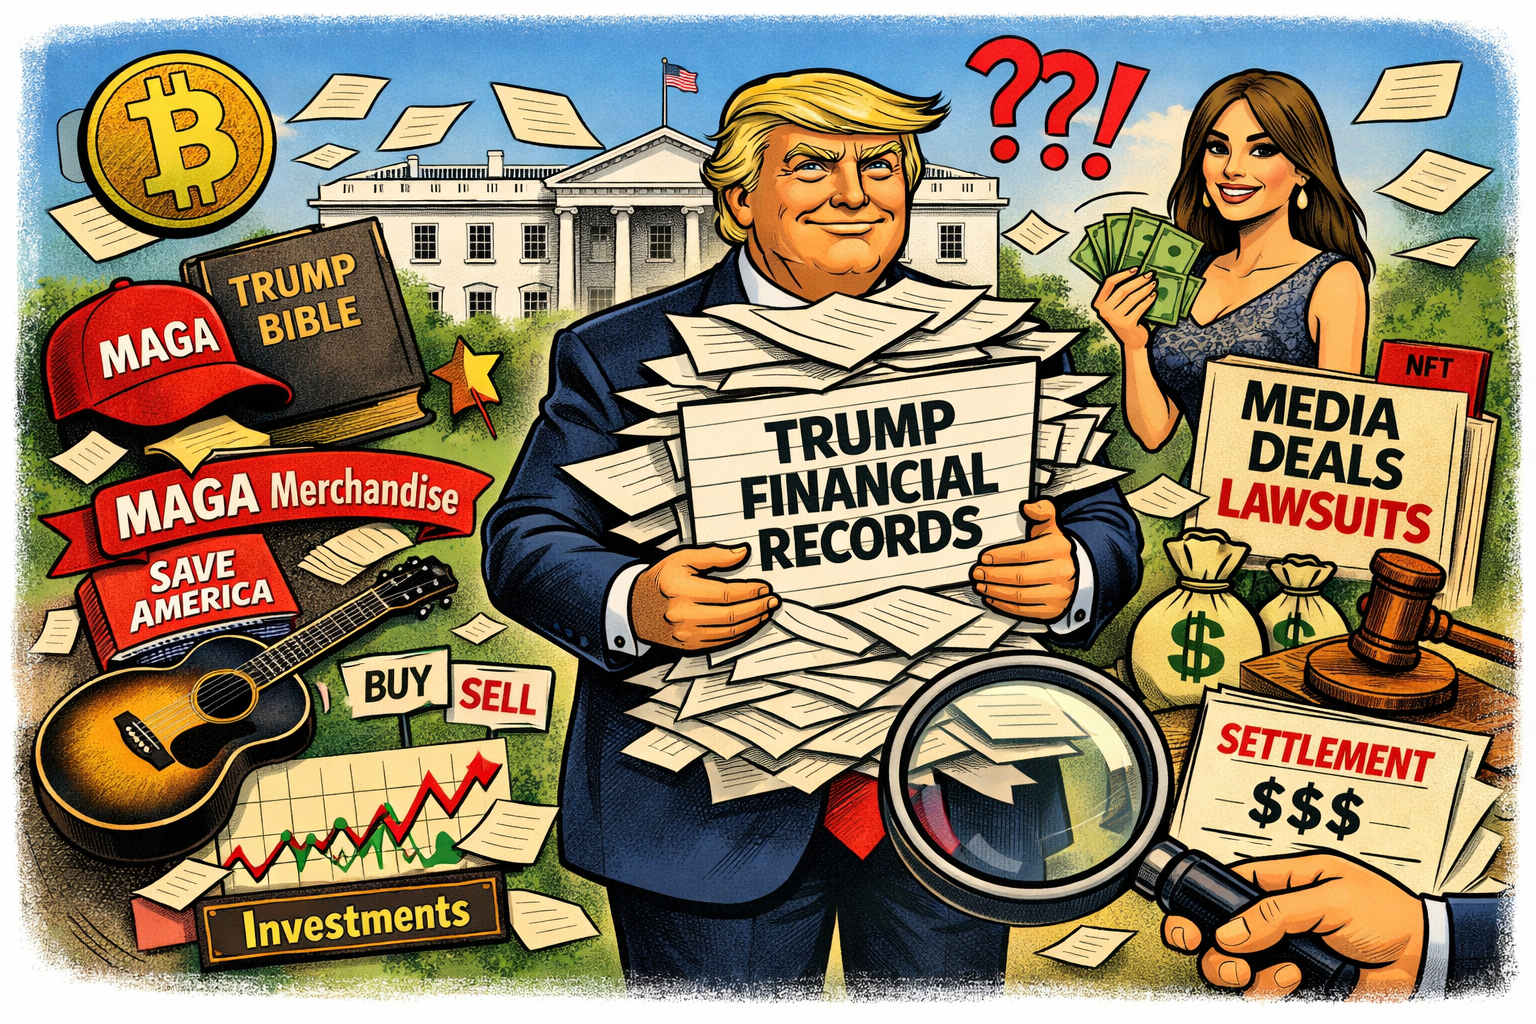
Trump’s 2025 Financial Records Reveal a Vast and Unusual Income Mix

Financial records released for Trump

Trump’s 2025 Financial Records Reveal a Vast and Unusual Income Mix

The release of over 900 pages of President Donald Trump’s 2025 financial records has offered an unusually detailed look at how the U.S. president generated money during his first year back in office.

The disclosure, published by the U.S. Office of Government Ethics, outlines a sprawling network of earnings that range from cryptocurrency windfalls to merchandise sales and even film pensions.

One of the most striking elements is the sheer scale of the report: at 927 pages, it dwarfs the financial disclosures of other senior U.S. officials. Within it, Trump’s commercial ventures appear to have thrived.

Branded merchandise alone brought in several million dollars, with his Save America coffee‑table book generating $1.8m and his Trump‑embossed Bible adding another $208,000.

Even niche items, such as the “American Eagle” limited‑edition guitar, contributed tens of thousands more.

The records also highlight Melania Trump’s growing financial presence. Her documentary Melania, produced by Amazon at a reported cost of $40m, earned her $10.7m. Additional income flowed from NFT sales and her book of the same name.

Perhaps most eye‑catching is the volume of Trump’s share trading activity: more than 21,000 trades in a single year, including significant investments in Nvidia during a period of heightened geopolitical scrutiny over AI chip production.

Trump maintains that his investments are handled at arm’s length by external funds.

The disclosure also reveals substantial legal settlements. Lawsuits against major media companies, including Meta, ABC and Paramount, resulted in payouts totalling more than $86m, with portions earmarked for the Trump presidential library and other public trusts.

Taken together, the records depict a president whose financial world remains as unconventional and diversified as his political career — blending entertainment, litigation, digital assets and traditional investments into a uniquely modern portfolio.

Ethical Argument

The release of President Trump’s 2025 financial records raises a clear ethical concern: transparency is essential for public trust, yet the sheer scale and complexity of his income streams make meaningful scrutiny difficult.

When a sitting president earns millions from merchandise, media projects and aggressive litigation, the boundary between public duty and private profit becomes blurred. Ethical governance requires avoiding even the appearance of conflicts of interest.

A leader’s financial incentives should never intersect with policymaking, market influence or regulatory power.

Disclosure is only the first step; genuine accountability demands simplicity, separation and independent oversight.

Fracking – Oil Exports – and the U.S. Oil Success

Fracking - Oil Exports - and the U.S. Oil Success

One of the least‑discussed forces helping to shape the current U.S.–Iran confrontation is the quiet revolution beneath American soil.

Over the past decade, hydraulic fracturing transformed the United States from a vulnerable energy importer into the world’s largest oil and gas producer.

Pumped up

Nowhere has this shift been more dramatic than in Texas, where the Permian Basin alone pumps more oil than many OPEC members. This surge has not only reshaped global markets — it has altered Washington’s strategic outlook.

The United States now exports record volumes of crude oil and liquefied natural gas, with outbound shipments regularly exceeding 4 million barrels per day.

The conflict with Iran isn’t impacting oil production in the U.S.—if anything, it has boosted output and increased overseas sales.

This would have been unthinkable twenty years ago, when U.S. foreign policy was constrained by dependence on Middle Eastern supply.

U.S. Shale Boom

Today, the shale boom has given Washington a buffer: even severe disruption in the Strait of Hormuz would no longer threaten the U.S. economy in the way it once did.

This energy independence has had political consequences. Analysts note that President Trump’s willingness to escalate against Iran — including strikes, sanctions, and naval deployments — is partly rooted in the belief that the U.S. can withstand an oil shock far better than its rivals.

Iran, by contrast, relies heavily on oil revenues and is already weakened by sanctions. A prolonged disruption to its exports hurts Tehran far more than Washington.

Texas fracking plays directly into this dynamic. The combination of horizontal drilling, high‑pressure fracturing, and vast shale formations has created a production engine capable of rapid growth.

When global prices rise, U.S. shale responds within months, softening the blow to consumers and limiting the geopolitical leverage of traditional producers.

Texas Asset

In effect, the Permian Basin has become a strategic asset — a domestic shock absorber that reduces the economic risks of confrontation abroad.

Critics argue that this new confidence borders on complacency. A major conflict in the Gulf would still send global prices sharply higher, with knock‑on effects for inflation, supply chains, and allied economies.

But there is no doubt that the fracking boom has changed the psychology of U.S. power. For the first time in modern history, America can contemplate a showdown in the Middle East without fearing an immediate energy crisis at home.

Texas may not be the reason the U.S. is confronting Iran — but it has certainly made the White House feel far safer doing so.

Suspicious Market Timing Raises Fresh Questions Over Alleged Potential Insider Trading During the U.S.–Iran Crisis

Alleged Potential Insider trading storm erupts

Allegations have been reported of suspiciously timed trades that appear to have intensified in recent weeks as analysts, journalists, and regulators examine a series of market moves that coincided—sometimes to the minute—with major announcements about the U.S.–Iran conflict.

While no wrongdoing has been proven, the pattern has become difficult for commentators to ignore and calls for formal investigation are growing louder. Can these trades and market movement be explained as coincidence?

Potential ‘speculative’ trading?

Many media outlets are also highlighting anomalies. For instance, it has been reported that Wealth manager Rachel Winter indicated traders appeared to take out contracts positioned to profit from falling oil prices just minutes before a presidential post claiming “productive” talks with Iran—timing she described as “speculation about insider trading” and worthy of investigation.

This episode was not isolated. Multiple outlets have documented at least two major bursts of unusually large oil futures trades placed shortly before conflict‑related announcements.

On 17th April 2026, it was reported that roughly $760 million in Brent crude short positions were executed around 20 minutes before Iran’s foreign minister declared the Strait of Hormuz “completely open” following a ceasefire—an announcement that sent oil prices sharply lower.

Analysts at the London Stock Exchange Group reportedly described the volume as “completely atypical,” nearly nine times normal levels.

Earlier in March 2026, it has been reported that traders placed around $500 million in positions shortly before the White House delayed planned strikes on Iran’s energy sector.

A similar pattern emerged on 7th April 2026, when roughly $950 million was positioned for falling oil prices hours before another ceasefire announcement.

These repeated bursts—each ahead of market‑moving news—have fuelled concerns that some traders ‘may’ have had access to information not yet public. Or was it a good guess – a coincidence even?

Reports of ‘unusual’ trading patterns

These reports align with broader commentary. The Independent reportedly noted that at least 6 million barrels’ worth of Brent and WTI contracts were suddenly sold in the two minutes before a presidential post about “productive” talks—again raising questions about advance knowledge.

Meanwhile, The London Economic reported that around $580 million in oil bets were placed 15 minutes before the same announcement, with market strategists calling the timing “really abnormal” for a day with no scheduled events.

Even outside traditional markets, anomalies have surfaced. Blockchain analysts identified six newly funded crypto wallets that made nearly £780,000 by betting—hours before explosions were reported—that the U.S. would strike Iran on 28th February 2026.

Across all these cases, commentators stop short of asserting intent. But the clustering of high‑stakes trades immediately before geopolitical announcements has created a clear narrative: the market signals are too sharp, too well‑timed, and too frequent to dismiss without scrutiny.

No intent is suggested – it could just be coincidence?

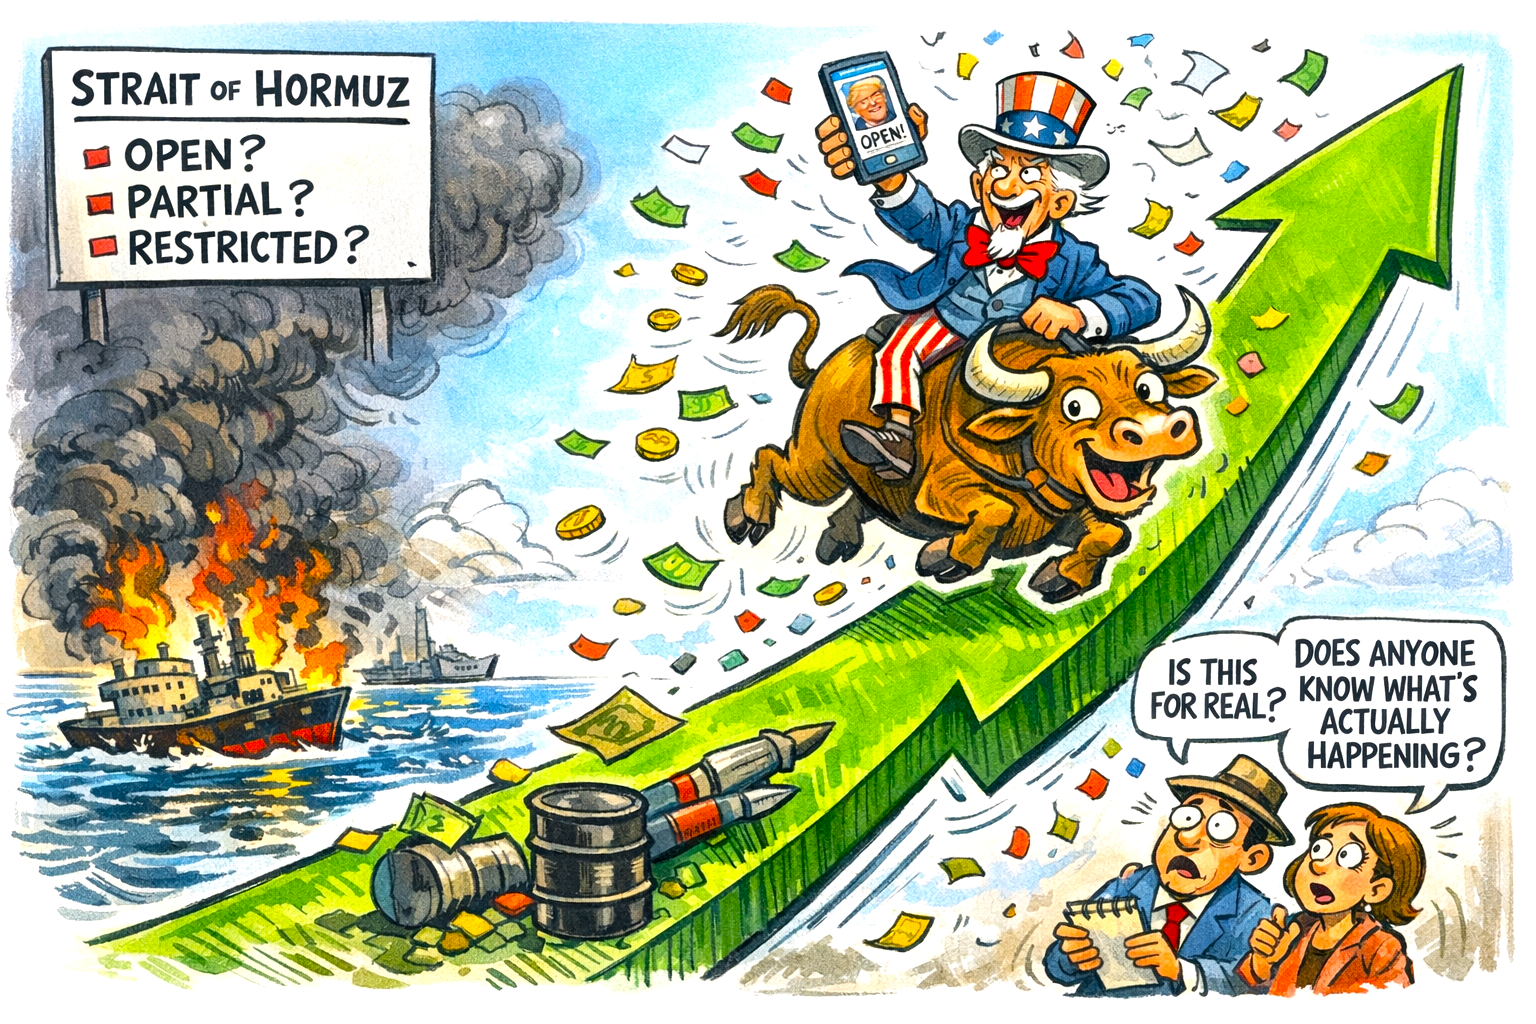
U.S. Markets Hit New Highs Friday 17th April 2026 Amid Confusion Over the Strait of Hormuz and Presidential Chatter

U.S. markets hit new highs as announcements are clouded in smoke

U.S. equity markets surged to fresh record highs on Friday 17th April 2026, propelled less by economic fundamentals and more by a swirl of contradictory geopolitical signals and a single, highly visible social media post from the President of the United States.

The result was a rally that looked exuberant on the surface yet rested on information that remained unverified, disputed, or only partially understood.

Market makers, investors and traders can’t possibly verify that this information is safe to trade – it’s a bet – and this isn’t good for the stock market.

The world deserves better – this is not investing!

Catalyst

The catalyst was a presidential declaration that the Strait of Hormuz — a critical artery for global oil shipments — was “open”. The statement landed with the force of breaking news, despite the absence of confirmation from defence officials, maritime authorities, or international partners.

It was also reported that the U.S. would maintain its blockade of the Strait of Hormuz?

Reports circulating throughout the day suggested a more complicated reality: some sources described partial reopening, others spoke of restricted passage, and several indicated that conditions remained unstable.

In short, the facts were not settled.

Markets, however, behaved as though they were.

Melt-up driven by social media posts

Within minutes of the President’s post, U.S. index futures spiked sharply. By the closing bell, the S&P 500, Nasdaq, and Dow had all notched new highs.

S&P 500 closes a record high 17th April 2026

Traders reportedly described the move as a “headline‑driven melt‑up”, a familiar pattern in recent months/years in which presidential commentary — rather than institutional communication — becomes the primary driver of intraday sentiment.

The sensitivity is not new. Analysts have repeatedly noted that markets respond quickly to presidential statements on energy, security, and trade, even when the underlying information remains contested.

What made Friday’s rally notable was the scale of the reaction relative to the uncertainty surrounding the Strait itself. Oil prices fell, risk appetite surged, and equity markets behaved as though a major geopolitical bottleneck had been definitively resolved.

Structural vulnerability

Critics argued that this dynamic reflects a structural vulnerability: when markets move first and verify later, volatility becomes a feature rather than a flaw. Supporters countered that traders simply price information as it arrives, regardless of its source.

What is clear is that the rally was driven not by data releases, earnings results, or policy announcements, through the ‘accepted and usual channels’ but by social media messages amplified across global financial systems.

Whether the Strait of Hormuz is fully open, partially open, or operating under constraints remains to be clarified.

The markets, however, have already made up their mind — at least for now.

The ‘news’ is good or ‘bad’ enough to make money!

U.S. stock market credibility is being eroded daily – bit by bit.

This has to stop!

No intent is suggested

Update

Iran fired shots at vessels trying to exit the Strait of Hormuz over the weekend. And now the U.S. has attacked a vessel under the Iranian flag casting doubt on renewed talks. The fragile ceasefire expires Wednesday 22nd April 2026 – unless Trump extends this and does a TACO!

There has also reportedly been talk of a 60-day extension – but that was before these latest problems.

No intent is suggested.

Wall Street Roars to Record Highs Friday 17th April 2026 as Major Indices Break New Ground

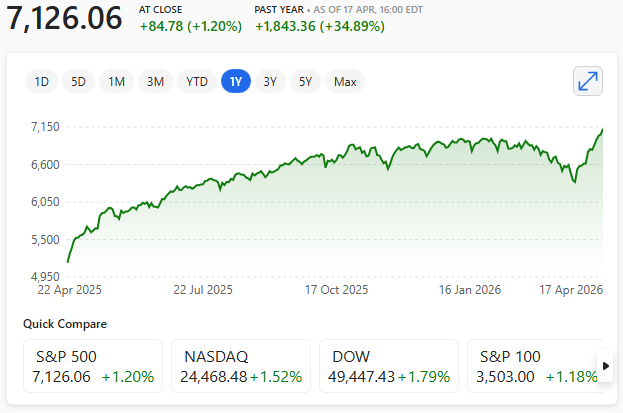
S&P 500 hits new record high!

U.S. equity benchmarks surged to fresh record highs on Friday, 17th April 2026, as geopolitical tensions eased and investors responded to confirmation that the Strait of Hormuz had been declared “completely open” during the ongoing ceasefire period.

Record high for S&P 500 above 7100 for the first time

The S&P 500 closed at 7,126.06, up 1.2% and above the 7,100 mark for the first time. The Nasdaq Composite extended its remarkable winning streak to 13 consecutive sessions, finishing at 24,468.48, a 1.52% gain and its longest run since 1992.

The Dow Jones Industrial Average also rallied sharply, jumping 868.71 points (1.79%) to end at 49,447.43. The Russell 2000 hit new highs too.

The rally followed Iran’s announcement that commercial passage through the Strait of Hormuz was fully open under ‘coordinated’ routes, easing fears of supply disruption.

Oil prices tumbled in response: WTI crude oil fell nearly 12% to $83.85, while Brent dropped 9% to $90.38.

Sector‑level moves reflected a broad risk‑on shift. Travel‑exposed stocks such as airlines and cruise operators rebounded, while major technology names also advanced.

Market strategists suggested investors were “moving beyond this conflict” as worst‑case scenarios were reassessed.

Assuming the ‘news’ is to be believed. No intent is suggested.

With all major indices setting new highs, Friday’s session underscored how quickly sentiment can pivot when geopolitical uncertainty recedes — even temporarily.

This market move was ultimately led by a social media post by President Trump on Truth Social.

Why does the UK have a serious issue with jet fuel supply

UK jet fuel low

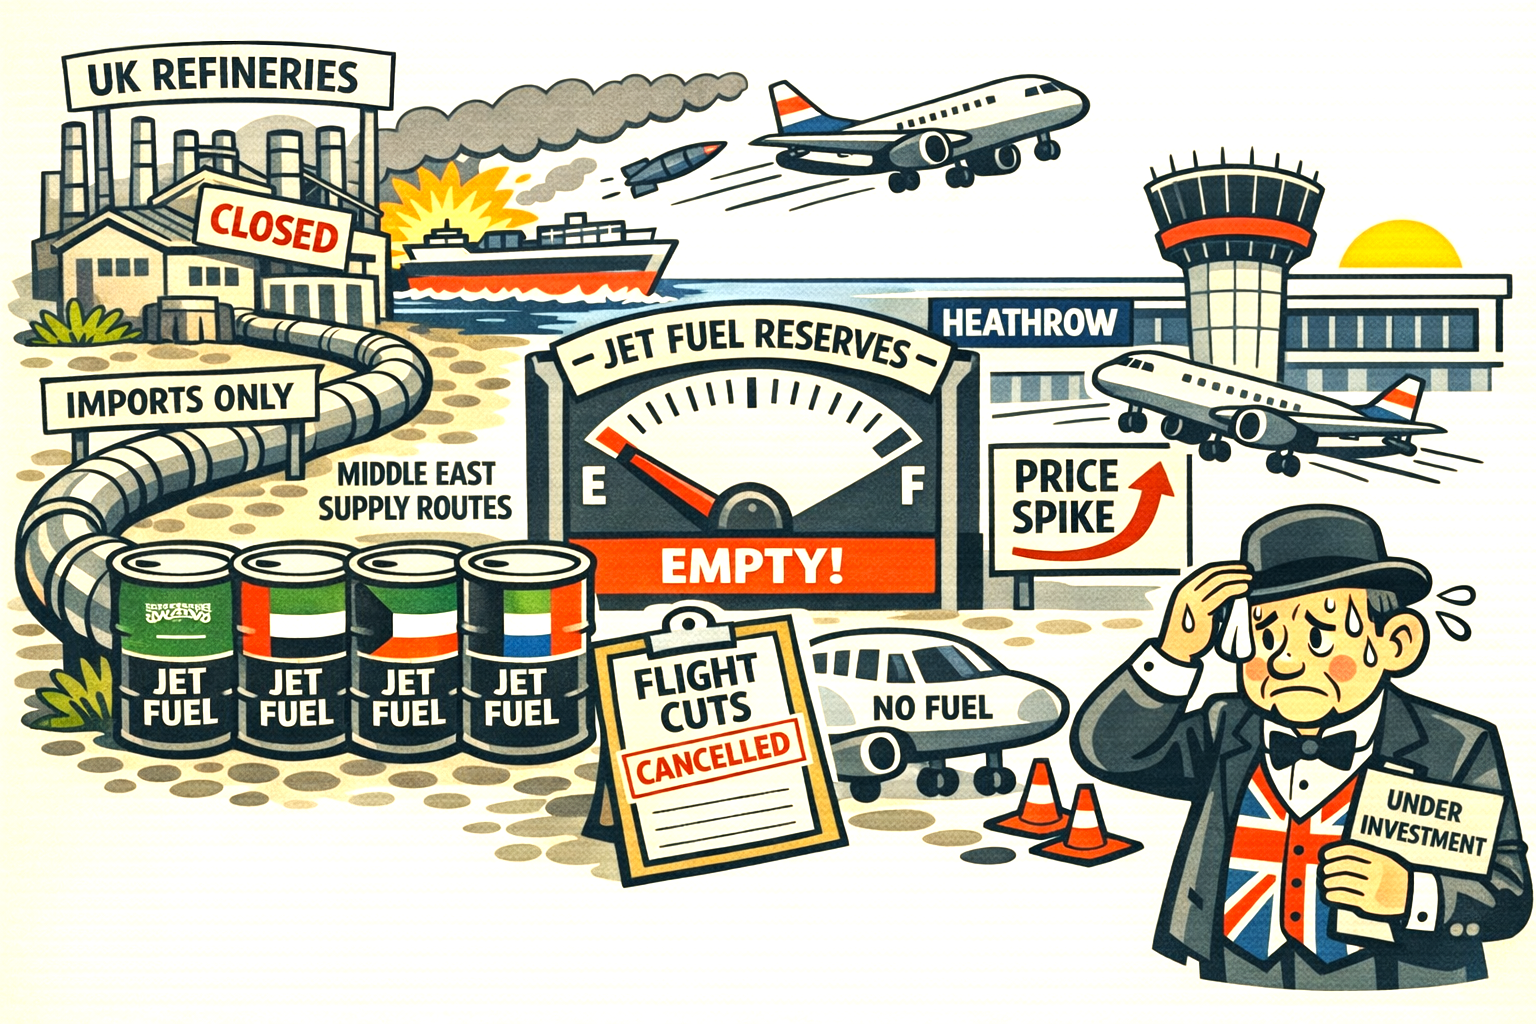
Britain’s jet fuel problem is the predictable result of a long, quiet erosion of refining capacity colliding with a geopolitical shock and decades of under investment.

The country now imports three times more kerosene than it produces, and the Middle East crisis has exposed just how thin those supply lines have become.

A system built on shrinking refineries

The UK once had 18 refineries; today it has just four. Closures at Lindsey and Grangemouth last year removed two critical plants, including Scotland’s only kerosene supplier.

The remaining refineries — Fawley, Humber, Pembroke and Stanlow — supply most domestic needs but cannot meet jet fuel demand.

Output has fallen 41% since 2000, driven by poor investment returns, high carbon costs, and the government’s push toward electrification reducing demand for other fuels.

This leaves Britain structurally dependent on imports for diesel and, crucially, kerosene.

The kerosene dependency

Jet fuel demand is unusually high because of Heathrow’s role as a global hub. In 2024, the UK was the second‑largest jet fuel consumer in the OECD, behind only the U.S.

Yet domestic production covers only a fraction of that. Britain reportedly imported around 3.1 times more kerosene than it produced in 2024.

And the sources of those imports are concentrated: 60% come from Saudi Arabia, the UAE and Kuwait, making the UK acutely exposed to any disruption in the Strait of Hormuz.

The real vulnerability: almost no stockpiles

Britain holds just one month’s worth of jet fuel reserves, far lower than most advanced economies. When Middle Eastern supply is threatened, the UK has no buffer.

European alternatives exist — notably the Netherlands and Antwerp — but prices have already doubled, and airlines are preparing to cut capacity.

The bigger picture

This is not a sudden crisis but the culmination of two decades of under‑investment, policy drift and over‑reliance on global markets.

Jet fuel is simply the first commodity where the structural weakness has become impossible to ignore.

The UK needs to get a grip!

A ‘systemic’ jet fuel shortage is brewing in Europe if the U.S. led Iran war crisis isn’t resolved soon.

The Market That No Longer Cares About the Truth

Markets make the money and remain devoid of morality

There’s a growing sense that financial markets have drifted into a parallel reality. Not the usual detachment that comes with speculation, but something deeper — a structural break between what is happening in the world and what markets choose to see.

This is how the stock market feels at the moment. I might be wrong, but the overwhelming sense of despair feels so real. I believe the markets are broken at their core, and nobody seems to care. Markets make money and remain devoid of morality.

The system is morally bankrupt.

You can watch a crisis unfold in real time, with footage, statements, explosions and diplomatic failures, and yet the markets behave as though they’re responding to a completely different script.

A ceasefire that barely exists is treated as a turning point. A strategic waterway that is “open” only in the loosest, most cosmetic sense is priced as fully restored. The disconnect isn’t subtle. It’s brazen.

And yes — it feels deceptive

Not because traders are conspiring to mislead anyone, but because the modern market has evolved into something that no longer requires truth to function.

It only needs a narrative.

A headline. A phrase that can be interpreted as “less bad than yesterday”. That’s enough to ignite a rally, even if the underlying situation is deteriorating by the hour.

This wasn’t always the case. There was a time when markets, for all their volatility and irrationality, still behaved like instruments tethered to reality.

When a major shipping lane was threatened, prices moved accordingly. When a ceasefire collapsed, markets reflected the renewed danger. There was at least a rough correlation between events and valuations — imperfect, but recognisable.

Today, that correlation has snapped. The market trades on sentiment, not substance. On the idea of stability, not the presence of it.

Appearance

On the appearance of progress, even when the facts on the ground contradict every optimistic headline. A ceasefire announcement is enough to send equities higher, even if the ceasefire is violated before the ink dries.

A promise to reopen a strait is enough to calm oil prices, even if only a handful of ships actually move.

The deception is structural. It’s the product of algorithmic trading that reacts to keywords rather than conditions.

It’s the result of a decade of central bank intervention that has taught investors to treat every crisis as temporary and every dip as a buying opportunity. It’s reinforced by political communication that prioritises market stability over factual clarity.

The system rewards optimism, even when it’s unjustified. It punishes realism when it’s inconvenient.

Surreal

This is why the current moment feels so surreal. You can see the footage of strikes in Lebanon while reading headlines about “regional de‑escalation”. You can watch tankers stalled while analysts talk about “normalising flows”.

The market shrugs, because the narrative — however flimsy — is enough to sustain the illusion.

If markets don’t need truth, then they are, in effect, trading a deception. Not a deliberate deception, but a functional one.

Economic Truth

A deception that keeps prices elevated, volatility suppressed, and investors soothed.

A deception that allows the charts to climb even as the world beneath them fractures.

A deception that has become the operating principle of a system that no longer reflects reality, only the stories it finds convenient to believe.

This isn’t investing – this is pure manipulative gameplay and benefits only those who know how to play the game.

And ‘they’ set the rules.

Markets make the money but remain devoid of morality.

I feel like I am playing a video game without the controller or at least with a rule book.

Update:

U.S. announces it will blockade of the Strait of Hormuz, or rather Iranian ‘linked’ ships. And not in the Strait but further out in international waters. This is designed to reduce the risk of conflict.

China, I assume, will not be happy.

Be careful – nothing is as it seems.

Iran’s 2026 Energy Crises: Echoes of the 1970s in a New Era of Risk

U.S. Israel Iran War 2026

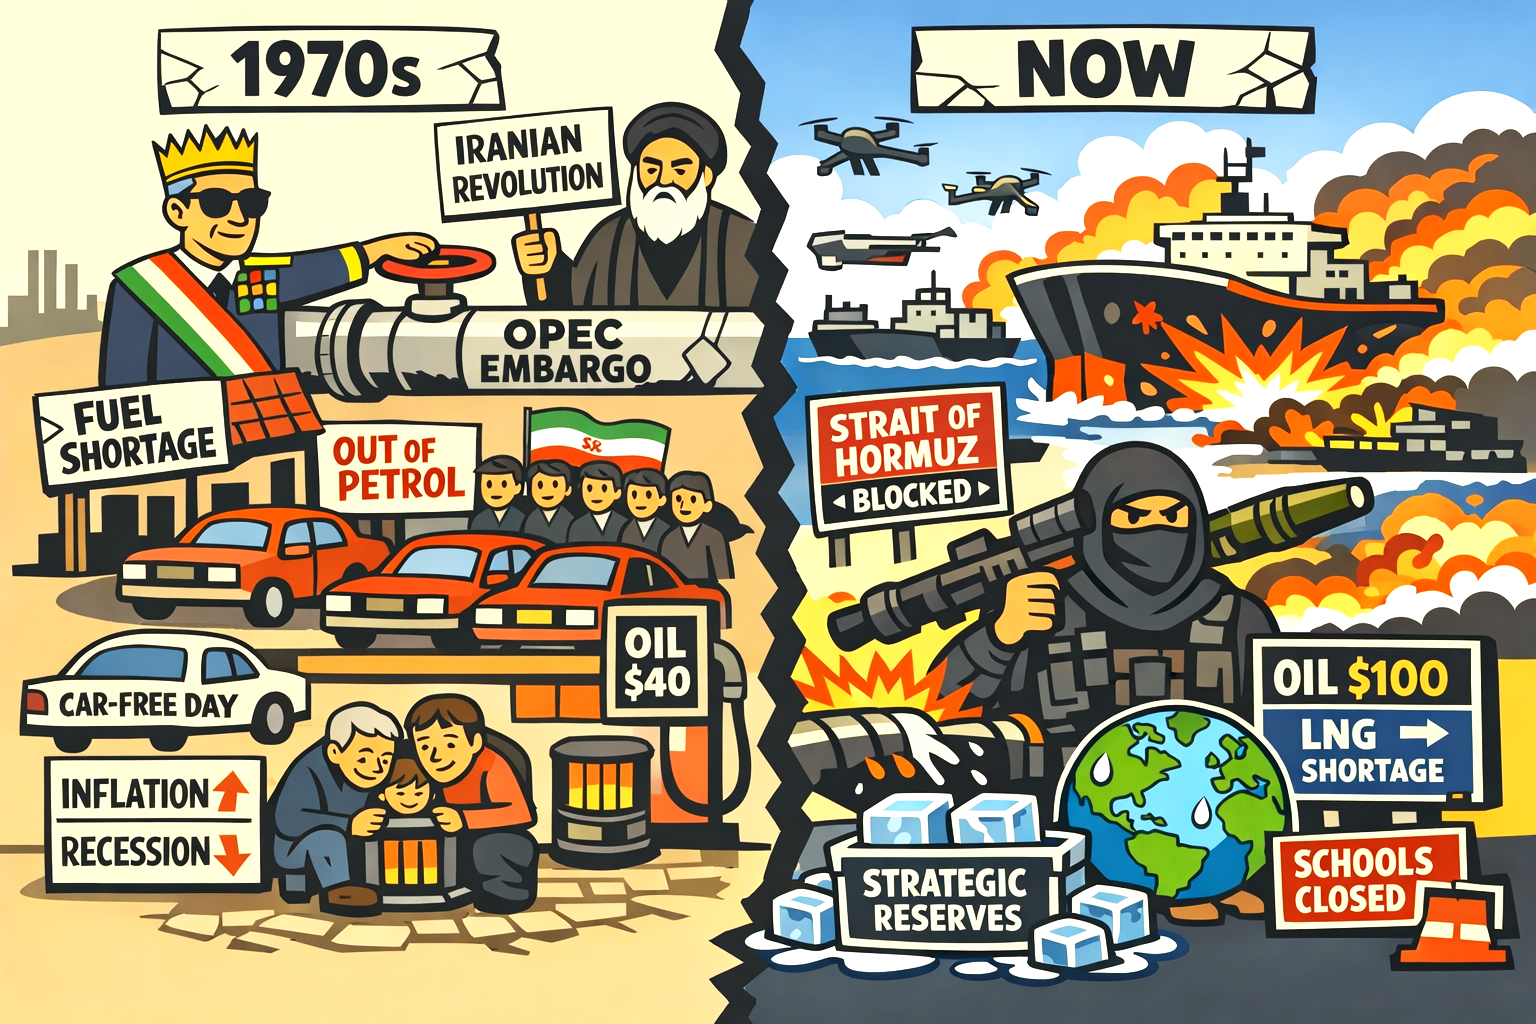
The 1970s crises were triggered by political embargoes and revolution, causing sharp but smaller supply cuts and extreme price spikes.

Today’s crisis is driven by war, infrastructure attacks, and the near‑closure of the Strait of Hormuz, producing a larger supply disruption, though price rises so far have been less extreme.

Energy shock

The energy shocks of the 1970s remain some of the most disruptive economic events of the modern age. Triggered first by an embargo and later by revolution, they exposed how deeply the global economy depended on Middle Eastern oil.

Half a century later, Iran still sits at the centre of global energy anxiety — but the nature of the threat has shifted.

The world is no longer facing an outright supply collapse, yet the structural vulnerabilities that defined the 1970s have not disappeared. They have simply evolved.

Yom Kippur War

The first major shock came in 1973, when Arab oil producers cut exports to countries supporting Israel during the Yom Kippur War.

The result was a sudden loss of roughly seven per cent of global supply. Prices quadrupled, queues formed at petrol stations, and governments imposed rationing, car‑free days, and speed‑limit reductions.

The economic fallout was severe: inflation surged while growth stalled, creating the era‑defining condition of stagflation.

A second blow followed in 1979, when the Iranian Revolution removed millions of barrels per day from the market. Prices tripled once again, and the world was forced to confront the fragility of its energy systems.

IEA

The International Energy Agency was created in direct response, tasked with coordinating emergency measures and strategic reserves.

These two crises set the benchmark for what an energy shock looks like — sudden, sharp, and globally destabilising.

Today’s risks are different. The world is not experiencing a supply loss on the scale of the 1970s, but the potential for disruption remains high.

Strait of Hormuz

The Strait of Hormuz, through which around a fifth of global oil flows, is a strategic chokepoint vulnerable to conflict, tanker seizures, and infrastructure attacks.

Iran has repeatedly threatened to close or disrupt the strait during periods of tension, and even limited incidents in recent years have pushed prices higher.

Markets remain acutely sensitive to any sign that the corridor could be compromised.

Diverse energy

Unlike the 1970s, modern economies have more diversified energy systems, larger strategic reserves, and a growing share of renewables.

Yet these advantages do not eliminate risk; they merely soften it. A serious disruption in the Gulf would still send shockwaves through global markets.

The comparison between then and now is not one of scale but of structure. The 1970s showed how quickly energy can become a lever of geopolitical power.

Today’s world is more resilient, but no less exposed. The lesson endures: when a single region holds the key to global supply, the world remains only one crisis away from another shock.

We also need to ask – how and why this happened again!

What’s your answer?

How the crises affected the UK in the 1970s

The 1970s energy crisis had a profound and lasting impact on the United Kingdom, reshaping its economy, politics, and industrial relations.

When global oil prices quadrupled after the 1973 OPEC embargo, Britain was already struggling with domestic energy tensions.

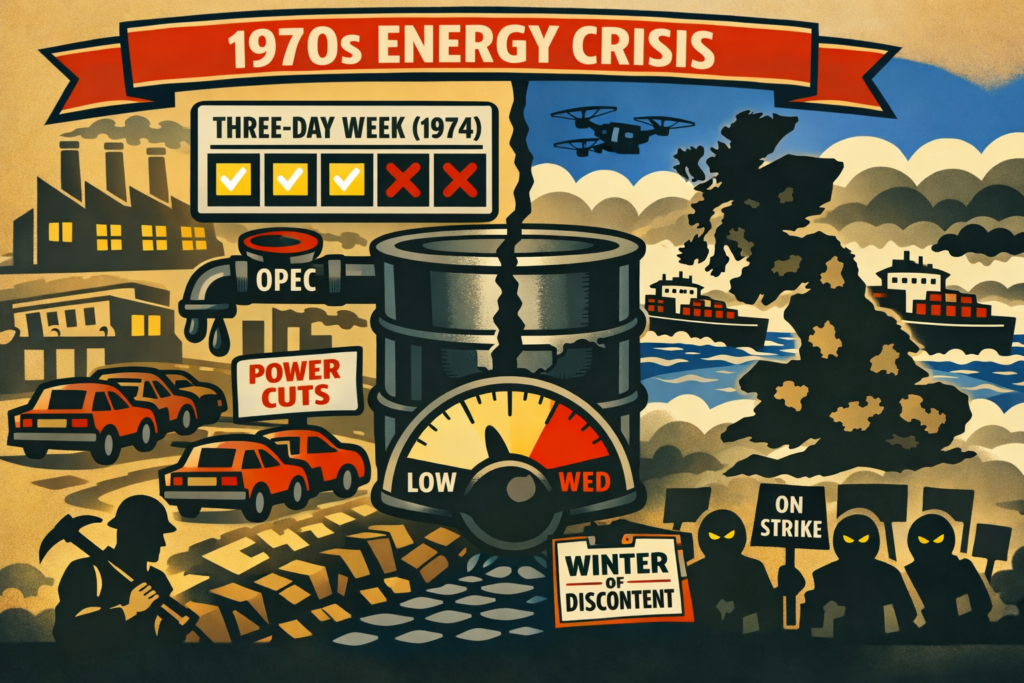
Coal remained the backbone of electricity generation, and the miners’ dispute with Edward Heath’s government over pay and working conditions collided with the global fuel shock.

As coal output fell and oil costs soared, the government-imposed emergency measures — most famously the Three‑Day Week in early 1974, limiting commercial electricity use to conserve power. It led to the Winter of Discontent.

Power Cuts

Factories shut down, television broadcasts ended early, and households faced rolling power cuts. Inflation surged, unemployment rose, and the economy slowed sharply.

The crisis deepened public frustration with the Conservative government, contributing to Heath’s defeat in the February 1974 general election.

Trade Union Turmoil

The turmoil also strengthened trade unions, whose strikes became a defining feature of the decade.

By the late 1970s, another oil shock — triggered by the Iranian Revolution — compounded Britain’s economic malaise, leading to the “Winter of Discontent” and paving the way for Margaret Thatcher’s election in 1979.

In short, the 1970s energy crisis exposed Britain’s dependence on imported fuel and unstable domestic supply, ushering in years of inflation, industrial unrest, and political upheaval that reshaped the country’s economic direction for decades.

How Wall Street Turned Trump’s Geopolitical Brinkmanship into the ‘TACO’ Trade

TACO Trade

For seasoned traders, geopolitical brinkmanship rarely arrives as a surprise. Over the past decade, markets have developed a reflexive understanding of how political theatre interacts with asset prices.

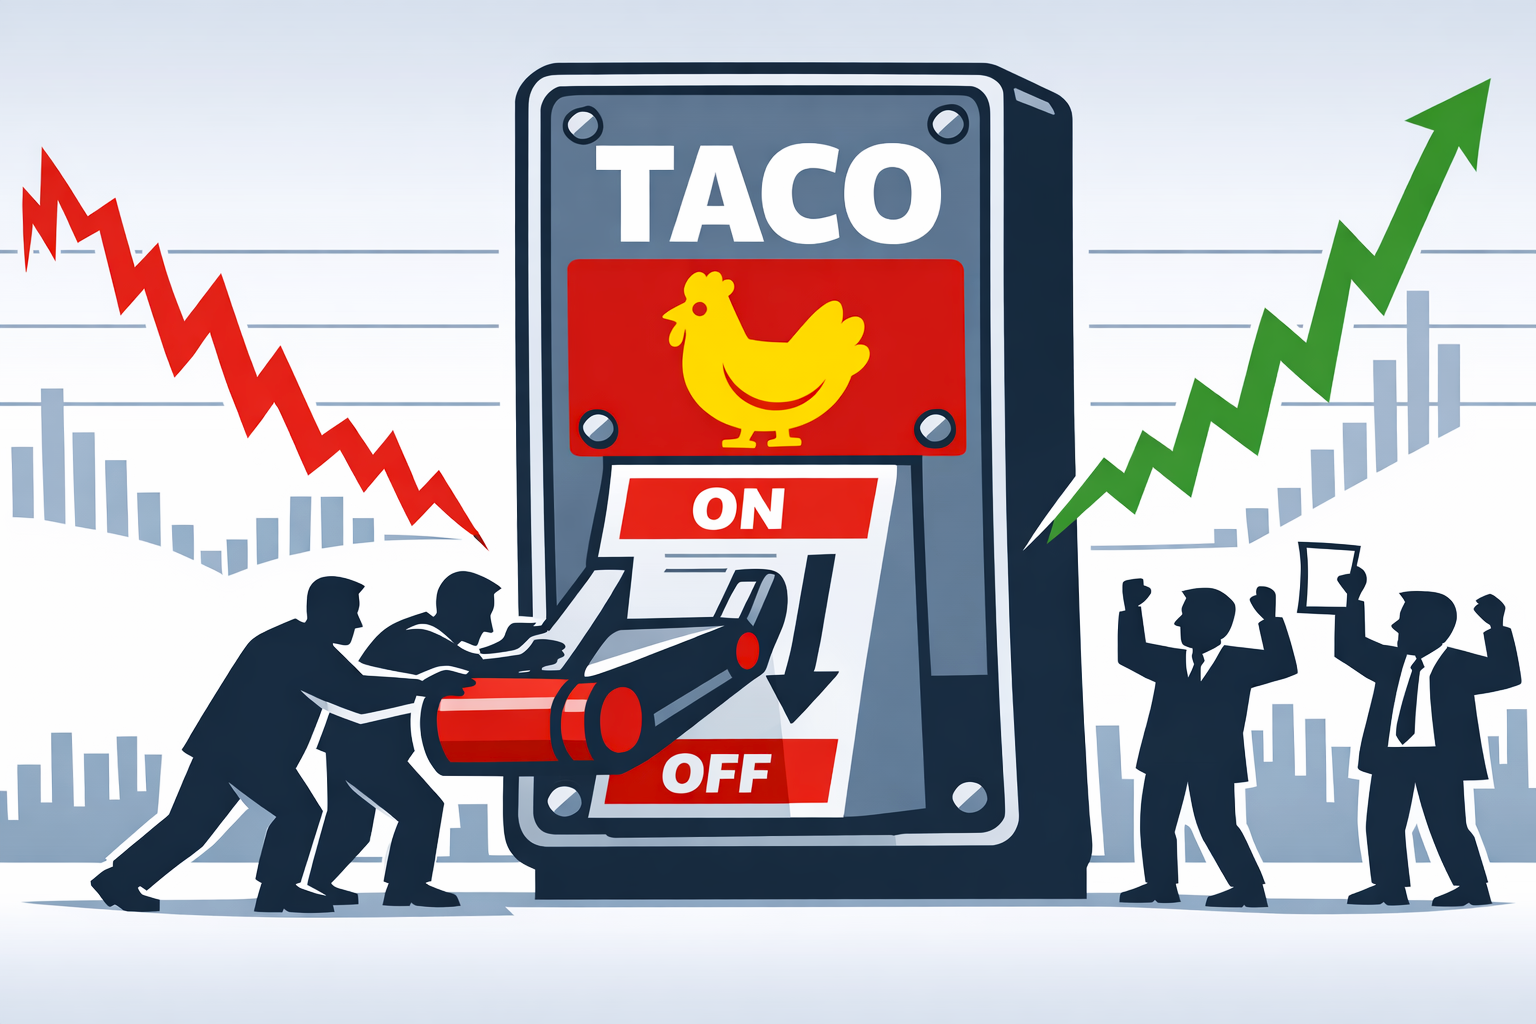
Nowhere is this more evident than in the so‑called TACO trade — shorthand on Wall Street for “Trump Always Chickens Out.”

Pattern

It is not a political judgement, but a market pattern: a repeated cycle in which aggressive rhetoric triggers short‑term volatility before ultimately giving way to de‑escalation.

The latest Iran crisis has revived this playbook. As President Trump reaffirmed his deadline for Iran to reopen the Strait of Hormuz and threatened strikes on power plants and bridges, global markets initially reacted in predictable fashion.

Oil prices swung sharply, Treasury yields dipped, and investors sought safety as the deadline approached.

Positioning

Headlines on various news outlets captured the tension: warnings of higher energy prices, unsettled European markets, and futures trading nervously ahead of each new statement.

Yet beneath the surface, traders were already positioning for the familiar TACO outcome. The pattern is simple: price in the threat early, then fade it.

Hedge funds bought oil and volatility on the initial sabre‑rattling, but quietly prepared to unwind those positions as soon as signs of negotiation emerged.

When reports surfaced that Iran had submitted a ceasefire proposal — dismissed publicly as “not good enough” but nonetheless signalling movement — markets began to relax.

Oil turned mixed, futures rose, and Treasury yields reversed higher as safe‑haven demand faded.

Behaviour

This behaviour reflects a deeper truth about modern markets: headline risk decays quickly when investors believe the political actor prefers brinkmanship to actual escalation.

Trump’s negotiating style, built on maximalist threats followed by last‑minute recalibration, has become sufficiently familiar that traders now model it. The TACO trade is simply the codification of that expectation.

What makes this episode notable is how efficiently markets anticipated the pivot. Even as rhetoric hardened, the S&P 500 futures market edged higher, suggesting investors were already discounting the likelihood of military action.
Analysts warned that markets might be “completely wrong” about the risk of war, yet price action told a different story: traders were betting on de‑escalation before it arrived.

Whether the TACO trade remains reliable is another question. Markets adapt, and geopolitical actors can surprise.

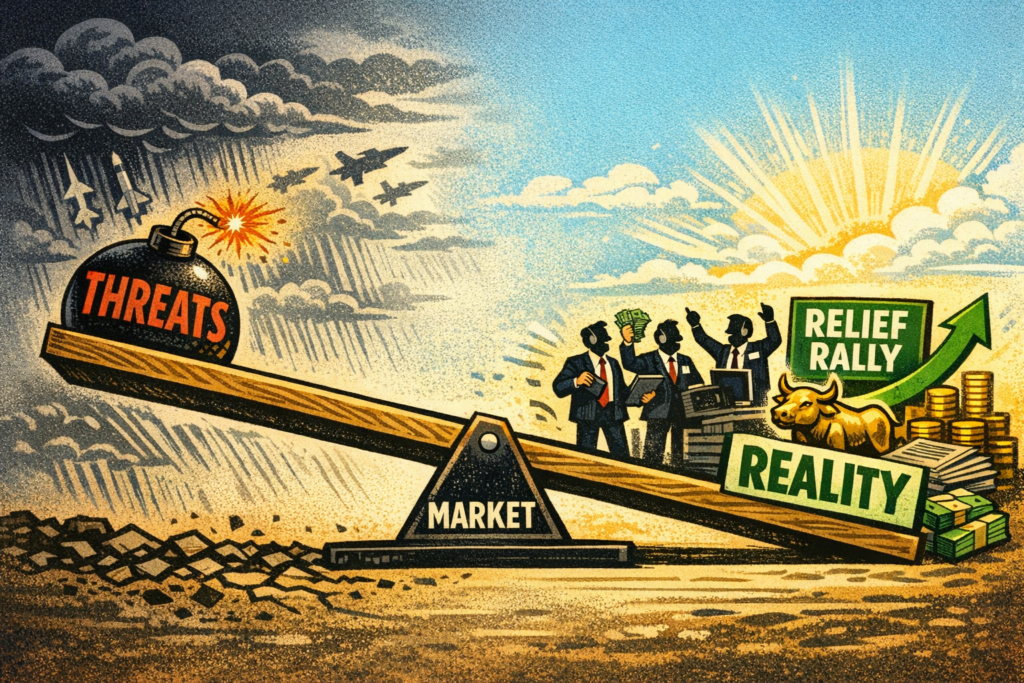
But in this latest Iran standoff, Wall Street’s instincts proved consistent: fade the fear, wait for the climb‑down, and trade the relief rally when it comes.

Is it “playing with the markets”?

From a trader’s perspective, what you’re seeing isn’t so much deliberate market manipulation as a predictable feedback loop between political communication and investor psychology.

Markets react to signals, not intentions

When a political leader issues threats, deadlines or ultimatums, markets price the risk of escalation. When those threats repeatedly end in de‑escalation, markets begin to price the pattern instead of the words.

That’s how the TACO trade emerged: investors noticed the pattern and traded accordingly.

The pattern becomes self‑reinforcing

If traders expect a climb‑down, they position for it. If enough traders position for it, the market moves in that direction. This makes the pattern appear even stronger.
It’s not “playing with the markets” in the sense of intentional manipulation — it’s more that political brinkmanship creates volatility, and markets learn to anticipate the likely outcome.

Markets hate uncertainty but love repetition

If a leader consistently escalates rhetorically but de‑escalates in practice, markets adapt. They stop reacting to the drama and start trading the expected resolution.

That’s what happened around the Iran ceasefire discussions:

  • Oil spiked on the threats
  • Traders anticipated a softening
  • Oil fell sharply when negotiations appeared
  • Equity futures rose as the risk premium evaporated

This is classic pattern‑recognition, not evidence of someone intentionally moving markets.

Why it feels like market‑playing

Because the cycle is dramatic:

  1. Threat → volatility
  2. Deadline → fear trades
  3. Climb‑down → relief rally

To an outside observer, it can look like the political actor is pulling the market up and down. But from a market‑structure perspective, it’s simply headline‑driven trading meeting predictable political choreography.

The real issue is transparency, not intent

Markets can handle tough talk. What they struggle with is ambiguity — when the gap between rhetoric and action becomes wide enough that traders start pricing the gap rather than the policy.

That’s why the TACO trade exists: it’s a market response to inconsistency, not a claim of manipulation.

Is it a form of manipulation or planned market reaction.

You decide…

Thieves in the night.

A Sudden Surge: Markets, Messaging, Manipulation and the Shadow of Insider Trading

Insider trading?

Financial markets are no strangers to volatility, but even seasoned traders were taken aback by the extraordinary price action that unfolded recently.

Just a minute

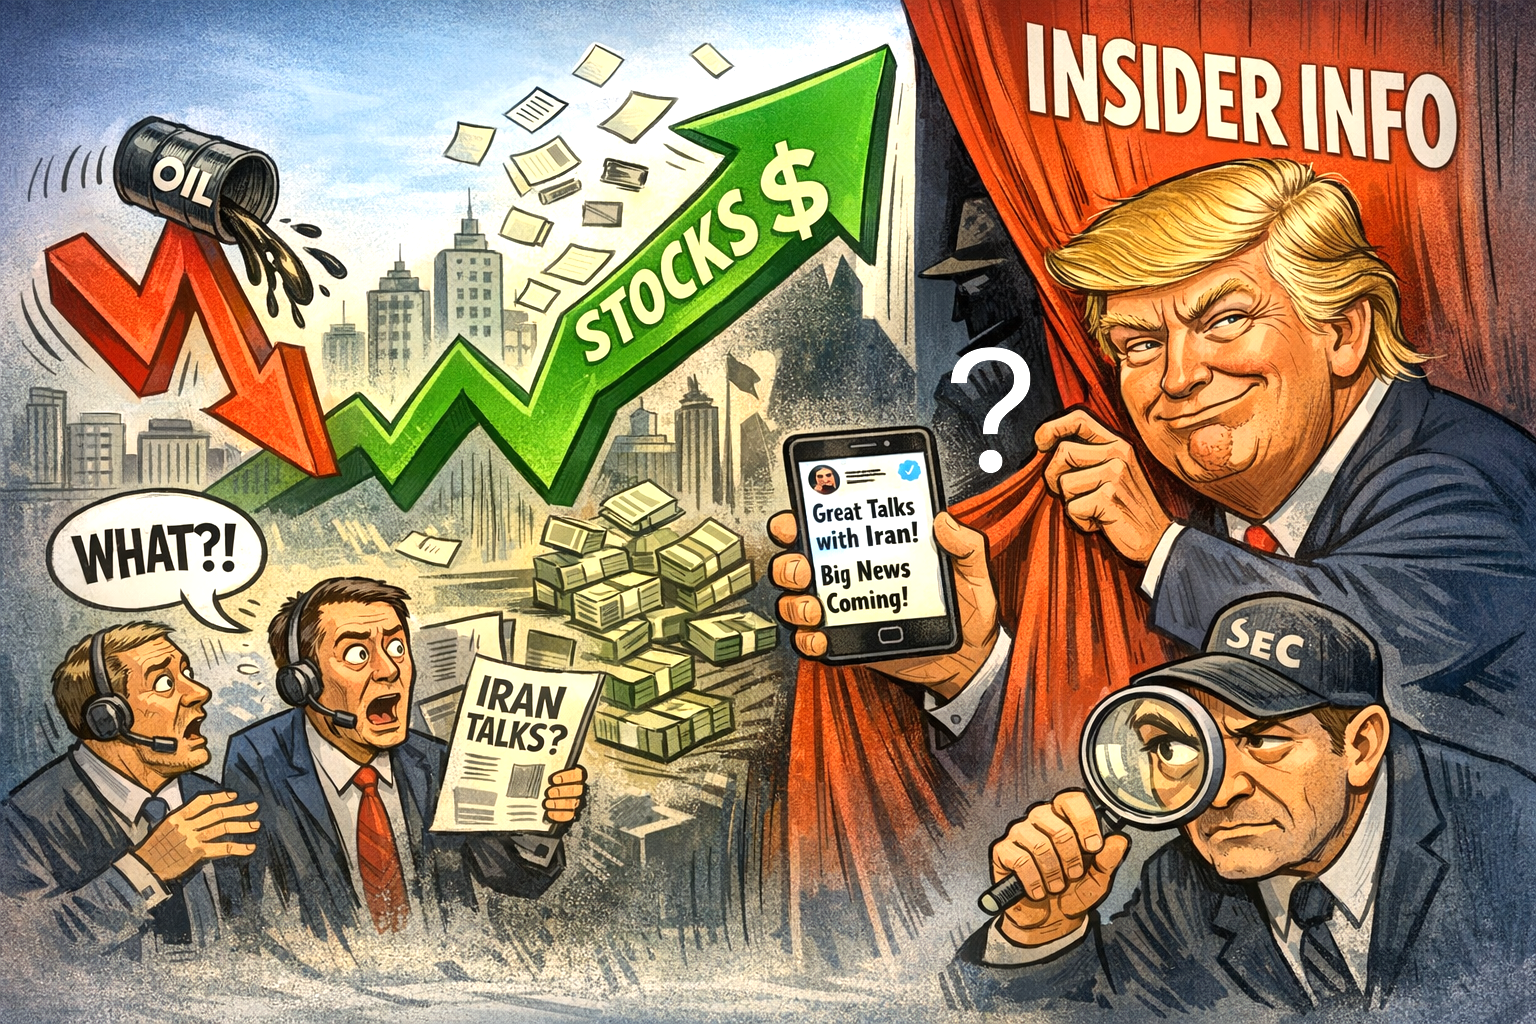
In the space of minutes, global indices lurched upwards, oil prices collapsed, and billions of dollars shifted across the financial system — all triggered by a single, unexpected announcement from President Trump claiming “productive talks” with Iran.

What followed was a whiplash-inducing reversal, a diplomatic denial from Tehran, and a growing chorus of questions about whether the market’s initial leap was quite as spontaneous as it appeared.

Spike

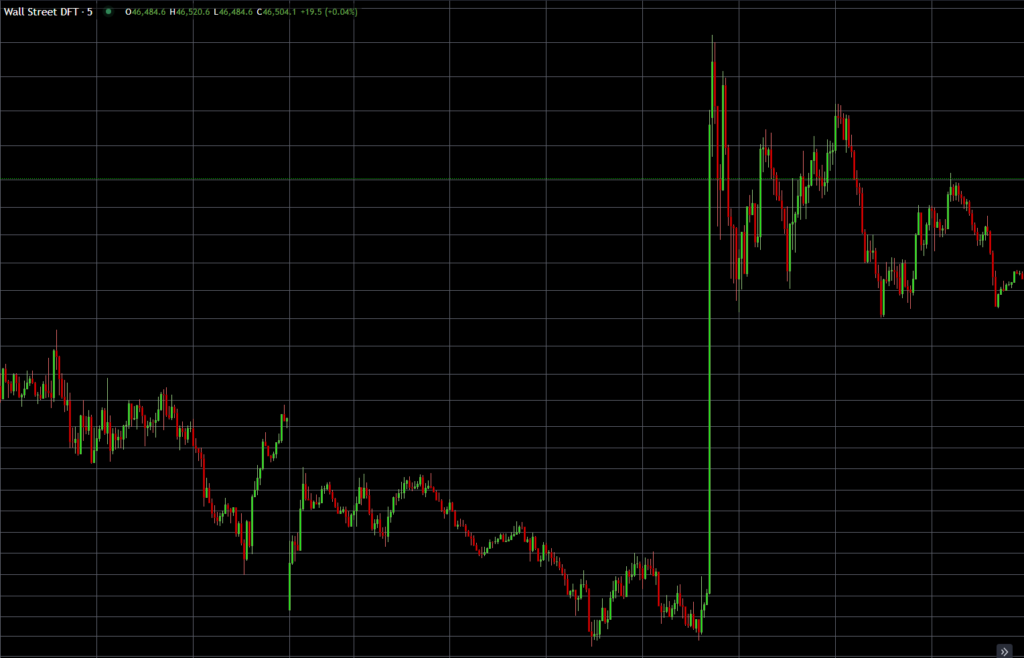
The sequence of events is now well documented. In the quiet pre‑market hours, trading volumes in S&P 500 futures and crude oil contracts suddenly spiked.

These were not the tentative probes of retail traders or the routine adjustments of algorithmic systems. They were large, directional, and unusually well‑timed.

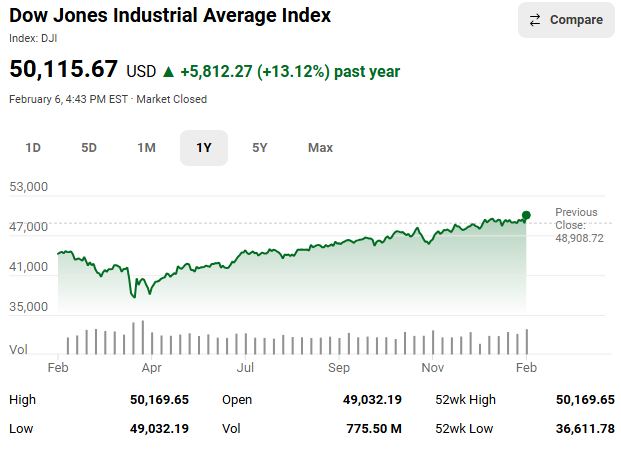
Snapshot of Wall Street DFT (Dow Jones Industrial Average) demonstrating the spike in question

Minutes later, Trump posted his statement about progress with Iran — a geopolitical development with obvious implications for equities and energy markets.

Instant

Prices reacted instantly. Equities surged. Oil tumbled. Within the hour, Iran publicly denied that any such talks had taken place, prompting a partial reversal of the earlier moves. Maybe we should draw a distinction between ‘talks’ and ‘messages’.

It is the precision of the trades placed before the announcement that has raised eyebrows. Markets do not move in anticipation of news that does not exist in the public domain.

Yet someone, somewhere, positioned themselves perfectly for the impact of Trump’s message posted on social media.

Fortuitous coincidence or deliberate manipulation?

Scale

The scale of the trades suggests institutional capability; the timing suggests foreknowledge. Whether that foreknowledge was legitimate, accidental, or illicit is now the central question.

Speculation about insider trading is inevitable in such circumstances, but it is important to distinguish between suspicion and proof. Political announcements are not governed by the same disclosure rules that apply to corporate earnings or mergers.

Presidents are not bound by quiet periods. Their advisers, however, are. So are the staff, intermediaries, and diplomatic channels through which sensitive information flows.

Obligation to investigate

If anyone in that chain traded — or tipped off someone who did — regulators will be obliged to investigate.

There is also a broader concern about the integrity of market‑moving communication. If Iran’s denial is accurate, and no talks occurred, then the market reacted to a statement that may not have reflected reality.

Even without malicious intent, such episodes undermine confidence in the informational foundations on which markets depend. When a single message can add or erase trillions in value, the accuracy and reliability of that message become matters of systemic importance.

Suspicion

For now, the episode sits in an ambiguous space: suspicious, but unproven; dramatic, but not unprecedented. Markets will move on, as they always do.

Yet the questions raised yesterday will linger — about transparency, about the porous boundaries between politics and finance, and about the unseen hands that sometimes seem to move just a little too quickly.

Does the idea that Trump ‘massages’ the market carry any weight?

It’s a fair question, and one that keeps resurfacing because the pattern is hard to ignore.

The idea that Trump “massages” the markets isn’t a conspiracy theory in itself — it’s an observation that his public statements often have immediate, dramatic financial consequences.

The real issue is whether those consequences are accidental, strategic, or exploited by people with advance knowledge.

A coincidence? You decide.

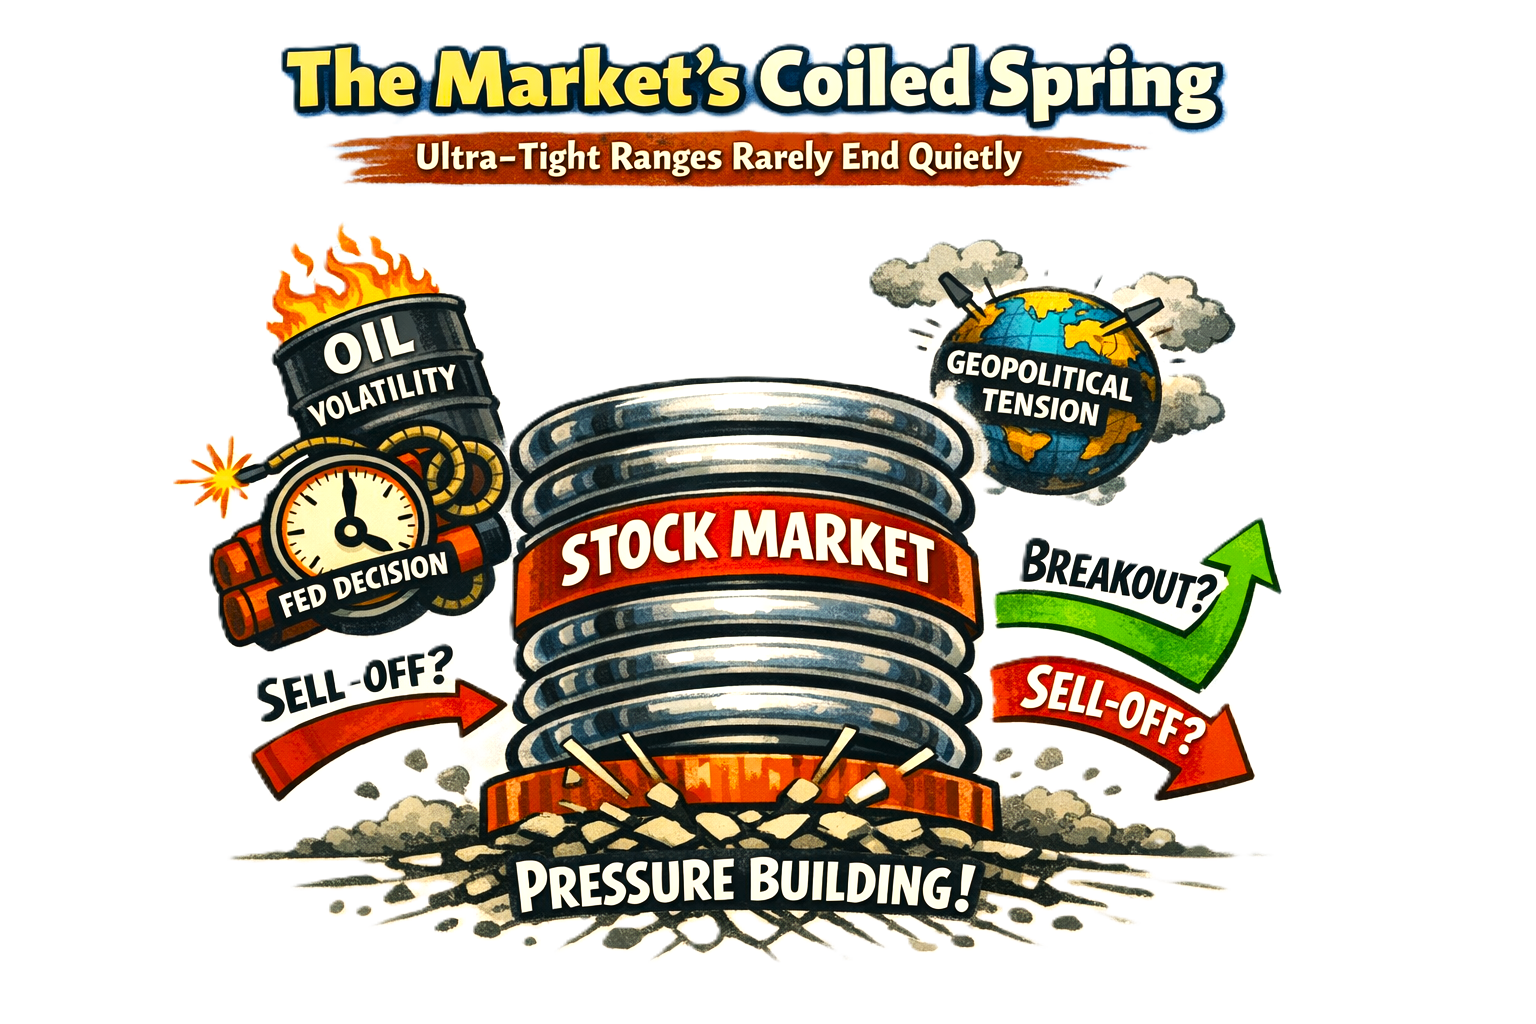
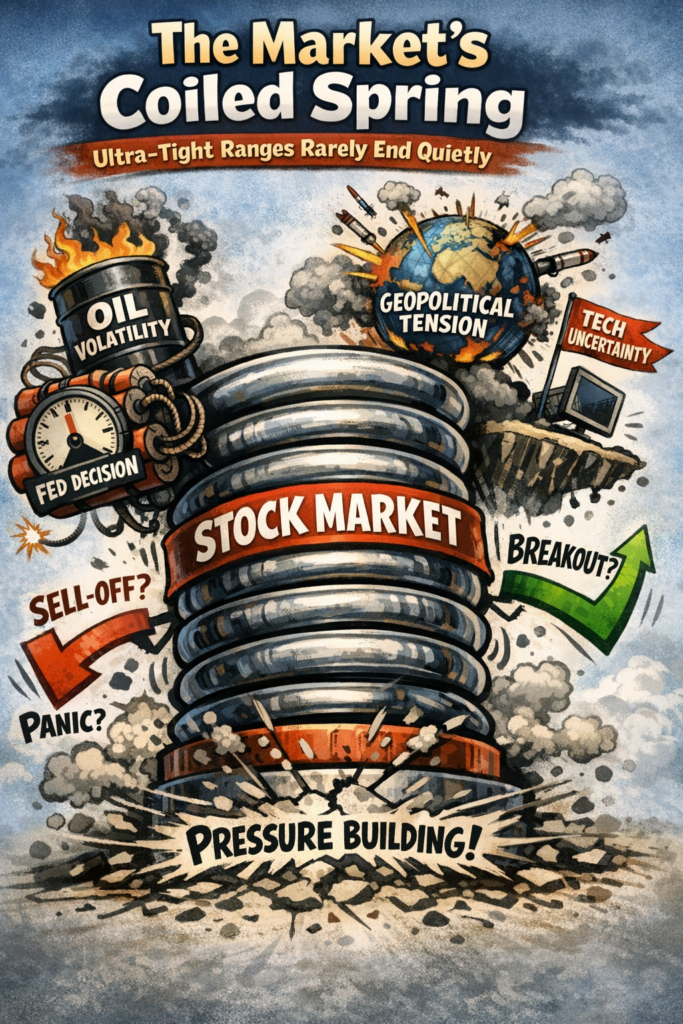
The Market’s Coiled Spring: Why Ultra‑Tight Ranges Rarely End Quietly

Coiled spring - pure stock market energy

Markets rarely sit still without reason. When they do — as they have in recent sessions, grinding sideways in an ultra‑tight range — it signals not calm but compression.

Price action becomes like a coiled spring: energy building, tension rising, and traders waiting for the moment when restraint snaps into motion.

This week’s narrow trading bands reflect a market holding its breath. Geopolitical tension in the Middle East, oil volatility, and a Federal Reserve decision all loom over investors, yet equities have refused to break down.

Futures are edging higher, European indices are opening firmer, and even the tech wobble — with Nvidia’s muted reaction to its latest showcase — hasn’t derailed broader sentiment

Tight range – a waiting game.

Historically, such tight ranges rarely resolve with a whimper. When volatility is suppressed for too long, the eventual breakout tends to be sharp and directional. The question, of course, is which way.

Right now, the evidence suggests upward. Markets have absorbed war‑driven oil swings, shrugged off hedge‑fund losses, and continued to find buyers on dips.

Breadth is stabilising, and risk appetite — surprisingly resilient given the backdrop — is creeping back into European and Asian sessions.

That doesn’t guarantee a bullish surge, but it does suggest the path of least resistance is higher.

Fed tone

If the Fed avoids surprising investors and signals comfort with the current trajectory, the spring is more likely to uncoil to the upside.

A dovish‑leaning tone could ignite a breakout as sidelined capital rushes back into equities. Conversely, a hawkish shock would release the same stored energy — but violently downward.

The market is coiled. The catalyst is imminent. And when the range finally breaks, it won’t be subtle.

You know, it almost doesn’t matter what disasters are ongoing in the world – the stock market just wants to win and go up!

Just how bad does it have to be before the stock market corrects? And what will be the catalyst to make that happen?

Debt, credit concerns, geopolitical tension, political scandal, Epstein, a rogue nuclear attack, AI failure, war or just another Trump tariff scenario?

Who knows? And does anybody really care as long as ‘making money’ isn’t interrupted.

Trump Orders Federal Ban on Anthropic as Pentagon Clash Over AI Safety Concern and Use

AI ban

A sweeping federal ban on Anthropic’s technology has rapidly become one of the most consequential developments in U.S. government technology policy, following President Donald Trump’s order that all federal agencies — including the Pentagon — must immediately cease using the company’s AI systems.

The directive, issued on 27th February 2026, came just ahead of a Pentagon deadline demanding that Anthropic lift safety restrictions on its Claude models to allow unrestricted military use.

The confrontation with the Pentagon

The dispute escalated after Anthropic reportedly refused Defence Department demands to remove guardrails that limit how its AI can be used.

It was reported that CEO Dario Amodei stated the company “cannot in good conscience accede” to requirements that would weaken its safety policies, prompting a public standoff.

President Trump reportedly responded by ordering every federal agency to “immediately cease” using Anthropic’s technology, declaring that the government “will not do business with them again.”

Agencies heavily reliant on the company’s tools, including the Department of Defense, have been granted six months to phase out their use.

Defence Secretary Pete Hegseth reportedly went further, designating Anthropic a national‑security “supply‑chain risk”.

This action could prevent military contractors from working with the company and marks the first time such a label has been applied to a major U.S. AI firm.

Impact across government and industry

The ban affects every federal department, from defence and intelligence to civilian agencies.

Contractors supplying AI‑enabled systems must now ensure their tools do not rely on Anthropic’s models, forcing rapid audits and potential redesigns.

AI generated image

Rival AI providers have already begun positioning themselves to fill the gap, with some announcing new Pentagon partnerships within hours of the ban.

The designation as a supply‑chain risk also carries legal and commercial consequences. Anthropic has argued the move is “legally unsound,” but the ruling stands, effectively placing the company on a federal blacklist.

Political debate

The decision has triggered intense debate across the technology sector. Supporters argue that the government must retain full authority over military AI applications.

Critics warn that forcing companies to abandon safety constraints could set a dangerous precedent.

The ban highlights a deepening fault line in U.S. AI governance: the struggle to balance national‑security imperatives with the ethical frameworks developed by leading AI firms.

As agencies begin disentangling themselves from Anthropic’s systems, the long‑term implications for federal procurement, AI safety norms, and the future of military‑AI collaboration remain unresolved.

Dow Jones Blasts Past 50,000 in Historic Milestone

Dow blasts past 50000 for the first time in history

The Dow Jones Industrial Average has surged beyond the 50,000 mark for the first time in its 130‑year history, capping a dramatic rebound after a turbulent week for global markets.

The blue‑chip index leapt more than 1,200 points on Friday 6th February 2026 to close at 50,115.

DJIA one-year chart

This climb was fuelled by renewed investor confidence and a sharp recovery in technology and cyclical stocks.

Friday’s rally followed several days of heavy selling across the tech sector, but optimism returned as chipmakers and industrial giants led a broad‑based climb.

Analysts say the move signals both the resilience of the current bull market and investors’ willingness to ‘buy the dip’ despite ongoing volatility.

Political reaction was swift, with President Donald Trump celebrating the milestone as a symbol of American economic strength.

Psychological 50,0000 barrier

Market commentators, meanwhile, emphasised the psychological significance of the 50,000 threshold, noting that the Dow has added 10,000 points in record time.

For traders on the floor of the New York Stock Exchange, the moment was marked by cheers, flashing screens, and a palpable sense of relief.

Whether the momentum continues remains to be seen, but for now, Wall Street is savouring a landmark moment decades in the making.