AI Is Breaking Down the Barriers to Starting a Business

The power of AI empowering business start-ups

Artificial intelligence is beginning to reshape the economics of starting and running a business.

AI is easily accessible

What once required substantial financial investment, specialist skills and a team of employees can increasingly be achieved by an individual with a computer, an internet connection and access to AI tools.

The implications could extend well beyond entrepreneurship, potentially changing productivity, employment, competition and economic growth.

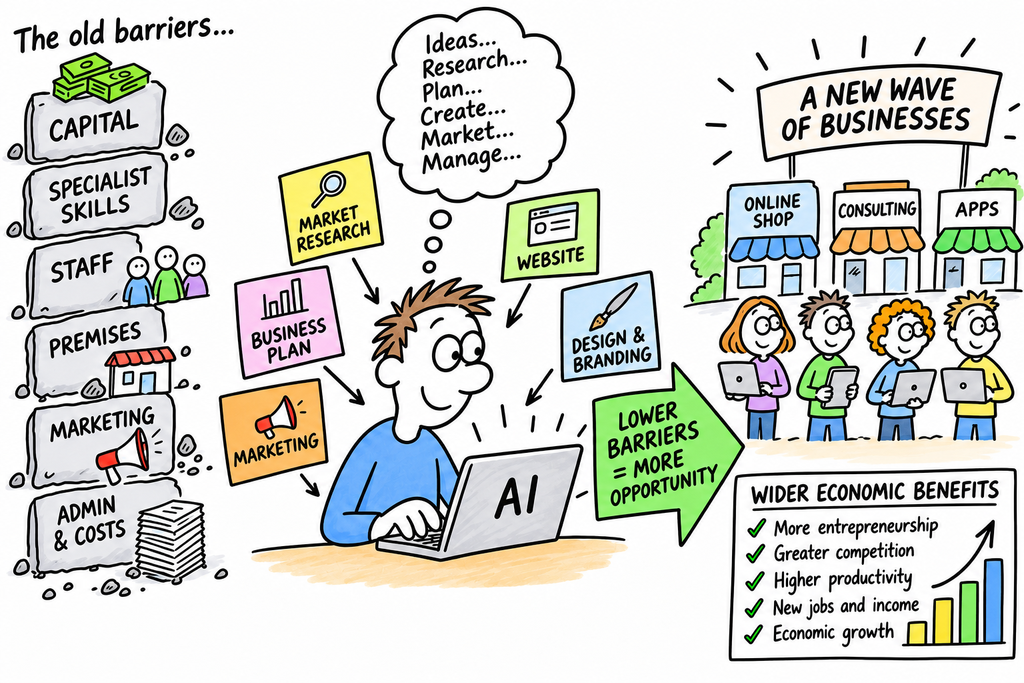
Traditionally, starting a business involved considerable upfront costs. Entrepreneurs needed to invest in staff, premises, marketing, professional services, technology and administration, often before generating their first pound of revenue.

These expenses created significant barriers to entry, particularly for individuals without access to capital or business connections.

AI is changing this economic equation

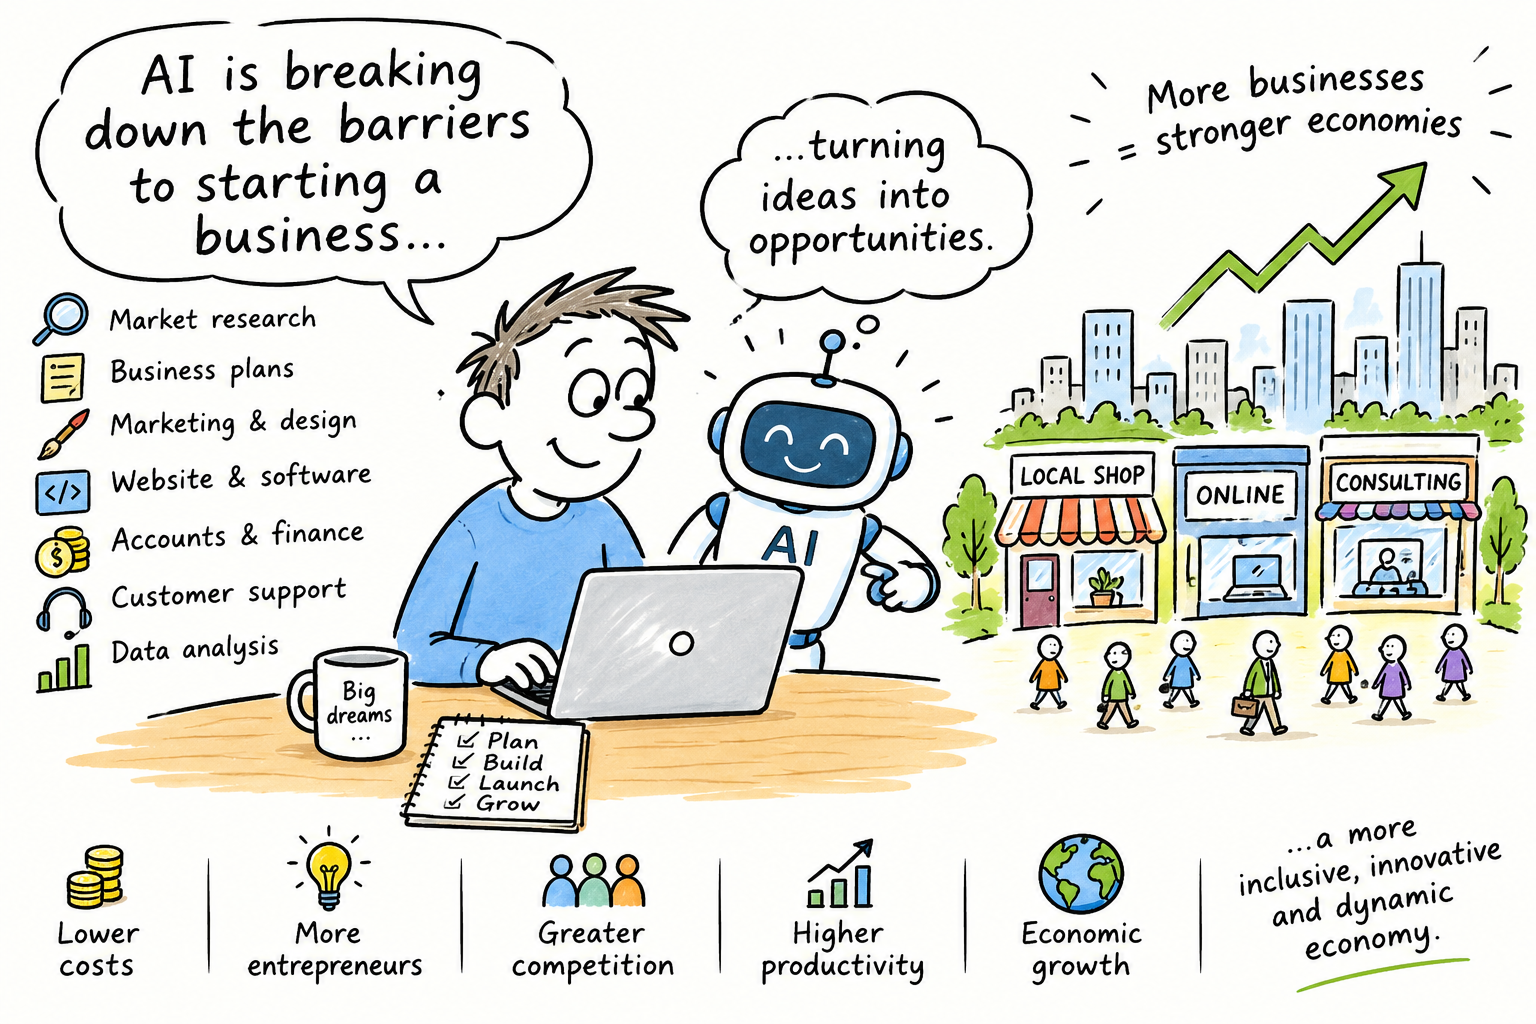
An individual can now use AI to conduct market research, develop business plans, build websites, write software, produce marketing campaigns, analyse financial information and manage customer enquiries.

Tasks that previously required several employees or expensive external consultants can increasingly be handled by one person at a fraction of the cost.

This has the potential to create a new generation of micro-businesses, independent entrepreneurs and highly productive one-person companies.

Lower operating costs could allow businesses to become profitable with considerably less revenue than was previously necessary.

For the many

The wider economic consequences could be significant. If millions of individuals can establish businesses with relatively little capital, entrepreneurship could become a much more accessible route to generating income and creating employment.

Smaller businesses may also become more competitive, challenging established corporations that have traditionally benefited from economies of scale, larger workforces and greater financial resources.

But first we will have a period of transition and discovery.

Productive

There is also a potentially important productivity dividend. Businesses able to produce more with fewer employees could reduce operating costs, improve margins and increase output.

At a national level, this could contribute to economic growth without requiring the same expansion in the workforce.

For governments struggling with ageing populations, labour shortages and weak productivity, AI could become an increasingly important economic tool.
Saturation

However, there is another side to the equation. As the cost of establishing a business falls, competition will intensify.

Markets could become saturated with similar products and services, while automation may displace certain administrative, creative and professional roles.

The economic benefits will depend partly on whether new businesses and industries create sufficient opportunities to offset employment lost elsewhere.

Access to AI will also matter. If the technology becomes concentrated among a small number of powerful companies, the savings generated by automation may not be distributed evenly.

Nevertheless, AI could represent a significant democratisation of business ownership. The traditional advantages of capital, staffing and infrastructure may become less important, while creativity, commercial judgement and the ability to identify opportunities become increasingly valuable.

The Next Wave

The next wave of business creation may not come from large corporations investing billions, but from individuals using AI to build businesses that previously would have been financially impossible.

AI is not eliminating the risks of entrepreneurship. It is, however, dramatically reducing the cost of trying. That could have profound implications for the future structure of the global economy.
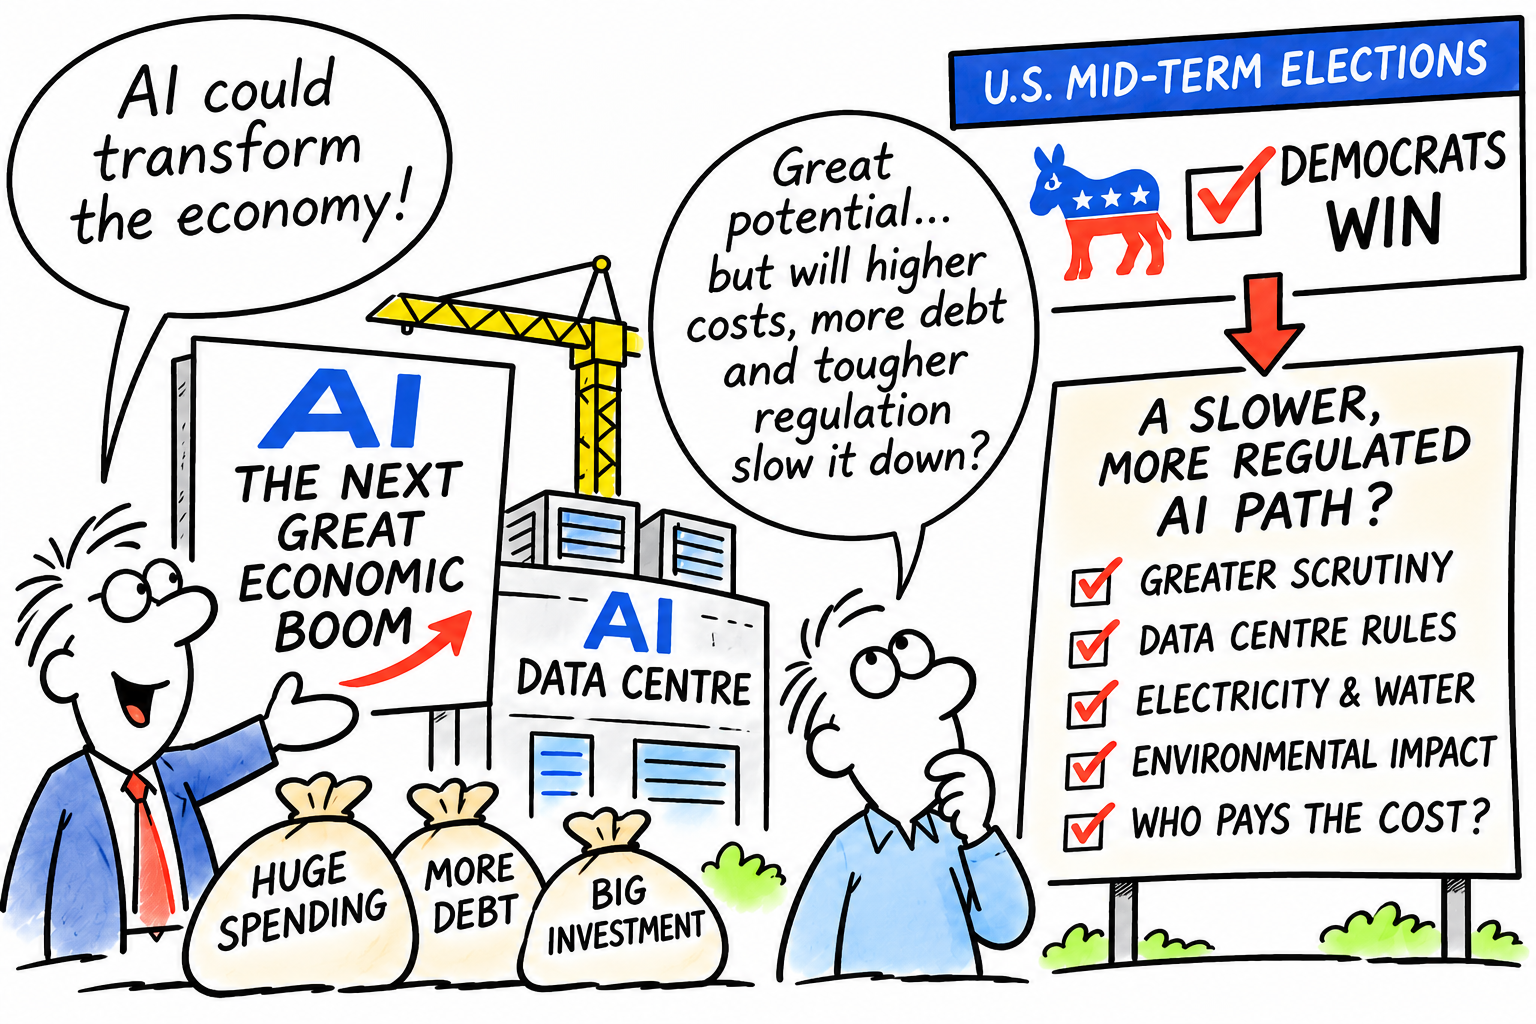
AI: The Next Great Economic Boom – But at What Financial and Economic Cost?

The artificial intelligence revolution continues to dominate financial markets, attracting extraordinary investment from some of the world’s largest technology companies.

Yet beneath the enthusiasm, a growing number of economic, financial and political concerns are emerging. While technology shares have recently staged a recovery, the fundamental questions surrounding the sustainability of the AI investment boom remain unanswered.

The central issue is becoming increasingly difficult to ignore: can the commercial returns from artificial intelligence justify the enormous cost of building the infrastructure required to support it?

An unprecedented investment programme

Microsoft, Amazon, Alphabet, Meta, Oracle and many others are committing hundreds of billions of dollars to data centres, specialist processors and supporting infrastructure. Their ambitions are substantial, with AI expected to transform productivity, business operations, healthcare, manufacturing and countless other industries.

However, the scale of expenditure is creating growing financial pressures. The Bank of England has highlighted the increasing reliance on borrowing to finance AI infrastructure. Morgan Stanley reportedly estimated that global AI-related debt issuance had reached approximately $450 billion by early September 2026, more than double the total for the whole of 2025.

The Bank has also highlighted the growing involvement of private credit and more complicated financing arrangements. These developments raise questions about where the financial risks ultimately sit, particularly if expected commercial returns fail to materialise.

Debt itself is not necessarily a problem. Large companies routinely borrow to finance expansion. The concern is whether the investment will generate sufficient cash flow to service that borrowing while continuing to fund further development.

The returns question

Technology companies are investing on the assumption that AI adoption will eventually produce enormous commercial opportunities. However, the gap between infrastructure expenditure and demonstrable financial returns remains an important consideration.

Data centres are expensive to construct and operate. Specialist chips require continual investment, while electricity, cooling, water and network infrastructure add further costs.

The industry must also contend with rapidly changing technology. Today’s expensive processors and facilities could become less competitive as more efficient systems emerge.

There is also the possibility that investment is running ahead of commercial demand. Businesses are experimenting with AI, but widespread adoption does not automatically translate into sufficient revenue to justify the enormous infrastructure costs.

Investors will increasingly want evidence that AI-related revenues and productivity improvements are keeping pace with capital expenditure.

Chinese competition adds another complication

Competition from China represents another potential challenge.

Chinese developers have demonstrated that increasingly capable AI models can be produced using more cost-efficient approaches. This could put pressure on the pricing structures of American technology companies.

If businesses can access capable AI systems at considerably lower prices, the commercial returns expected by companies investing heavily in infrastructure could be affected.

The AI industry may ultimately become much larger, but that does not guarantee that every company currently investing in it will generate attractive returns.

The political landscape changes

The U.S. midterm elections have introduced another dimension.

Democrats have secured control of both the House of Representatives and the Senate, creating a more challenging political environment for President Trump during the remainder of his term.

Technology companies could face increased scrutiny over data-centre construction, electricity consumption, environmental considerations, water supplies and AI regulation.

There are already disagreements in Washington over who should pay for the additional electricity infrastructure required by data centres. Some lawmakers want technology companies to shoulder more of the cost rather than passing it on to ordinary electricity consumers.

These concerns are particularly relevant in states such as Texas, where substantial AI infrastructure investment is planned.

Greater political scrutiny does not necessarily mean that AI development will stop. However, additional regulation, planning restrictions and infrastructure costs could slow the expansion or reduce the profitability of some projects.

Why is the Nasdaq recovering?

Despite these concerns, technology shares have recently demonstrated considerable resilience.

On 3rd November 2026, the Nasdaq gained approximately 0.83%, supported by a recovery in major AI and semiconductor shares. Nvidia, Broadcom and Micron were among the beneficiaries.

However, this recovery seemed to start ahead of the full midterm election results. Following the Democratic victories, global markets initially reacted negatively, reflecting concerns about potential regulatory changes and the future pace of AI infrastructure investment.

The recovery in technology shares should therefore not be interpreted as evidence that the underlying problems have disappeared.

Investors may be buying following recent declines, taking advantage of lower valuations or closing short positions. Such activity can produce substantial market recoveries without any corresponding improvement in the industry’s financial fundamentals.

A defining moment for investors

The AI revolution could ultimately prove to be one of the most important technological developments in modern economic history. Its potential should not be underestimated.

However, technological success and investment success are not necessarily the same thing.

The companies building the infrastructure must demonstrate that their investments can generate sustainable revenues, adequate cash flow and acceptable returns. Meanwhile, increasing borrowing, competition, resource constraints and political intervention could complicate that process.

For investors, the next stage of the AI story may be less about excitement surrounding technological possibilities and more about financial discipline.

Capital expenditure, debt issuance, free cash flow, AI-related revenues and institutional investment decisions deserve particularly close attention.

The wider economic consequences also matter. If AI delivers the productivity improvements its supporters anticipate, the benefits could extend well beyond the technology sector.

Conversely, if investment expectations become disconnected from commercial reality, the financial consequences could reach credit markets and the wider economy.

The AI revolution may be gathering momentum, but the investment boom financing it is approaching an important test.

The question is no longer simply how transformative AI might become. It is whether the extraordinary sums being committed today can generate sufficient economic value tomorrow.

For investors, that distinction could become increasingly important.

When Water Becomes the Weak Link in Europe’s Energy System

Energy, AI, Data Centres, people and water!

Europe’s extraordinary summer heatwave is exposing an uncomfortable truth about modern energy systems: electricity may be generated from uranium, gas, coal, wind or sunlight, but much of the infrastructure still depends on something increasingly unreliable — water.

The Danube has become the most dramatic example. Romania has now shut down both reactors at its Cernavoda nuclear power station after the river fell to historically low levels. The plant normally supplies around a fifth of Romania’s electricity.

Hungary’s Paks nuclear station has also been operating at sharply reduced output as the Danube struggles to provide sufficient cooling water.

Emergency engineering measures have even been considered to raise water levels around the plant.

But this is not simply a Danube problem

France’s huge nuclear fleet is facing a different version of the same challenge. Several reactors have been shut down or had their output reduced because rivers and seawater have become too warm.

Nuclear plants need enormous quantities of cooling water, but environmental rules restrict how much additional heat can be discharged into rivers when their temperatures are already dangerously high.

As of 13th August 2026, almost 20% of French nuclear capacity was unavailable, with the heatwave expected to force further reductions.

Jellyfish blockage

France has also encountered a rather more bizarre cooling problem. At Gravelines, one of Europe’s largest nuclear stations, huge quantities of jellyfish clogged seawater intake systems, forcing three reactors temporarily offline.

Warmer seas may make such biological disruptions more frequent

Elsewhere, Italy, Poland and Slovenia have also experienced power-plant restrictions linked to low river levels or excessive water temperatures.

Slovenia’s Krško nuclear plant, for example, reduced output because of hydrological and meteorological conditions affecting the Sava River.

The problem extends beyond nuclear: coal, gas and other thermal power stations also require cooling, while drought reduces the water available for hydroelectric generation.

UK gas heats up

Britain has not escaped the problem. During an earlier heatwave, five major gas-fired power stations reportedly had to reduce output because high temperatures made cooling more difficult.

The UK grid has also been under unusual summer pressure as air-conditioning demand rises, power-plant efficiency is affected and electricity imports become more important.

The bigger warning

Climate change does not simply mean hotter weather. It means the simultaneous arrival of several stresses: higher electricity demand for cooling, lower river flows, warmer cooling water, drought, wildfires, reduced hydroelectric output and pressure on transmission infrastructure.

Irony

The irony is striking. We build power stations to protect society from the weather, yet increasingly extreme weather can interfere with the very systems designed to keep the lights on.

Europe’s energy challenge is therefore becoming a climate-and-water challenge as much as an electricity challenge.

Future power stations may need alternative cooling systems, greater water efficiency, more storage, stronger interconnections and a much wider mix of generation.

Water security

The lesson from this summer is uncomfortable but simple: energy security depends on water security too.

U.S. AI vs China AI – the difference

China and U.S. AI

China’s AI industry has indeed cultivated a reputation for ‘doing more with less’, while the U.S. has poured vast sums into AI development, raising concerns about overinvestment and inflated valuations.

The contrast lies not only in the scale of funding but also in the efficiency and strategic focus of each country’s approach.

The U.S. Approach: Scale and Spending

The United States remains the global leader in AI infrastructure, driven by massive private investment and access to advanced computing resources.

Venture capital deals in U.S. AI and robotics startups have more than quadrupled since 2023, surpassing $160 billion in 2025.

This surge has produced headline-grabbing valuations, such as humanoid robotics firms raising billions in single rounds. Yet analysts warn of bubble risks, with valuations often detached from sustainable revenue models.

The U.S. strategy prioritises scale: building the largest models, securing the most powerful GPUs, and attracting top-tier talent.

This has led to breakthroughs in generative AI and large language models, but at extraordinary cost.

Estimates suggest that OpenAI alone has spent over $100 billion on development. Critics argue this reflects a ‘more is better’ philosophy, where innovation is equated with sheer financial muscle.

China’s Approach: Efficiency and Restraint

China, by contrast, has invested heavily but with a different emphasis. In 2025, Chinese AI investment is reportedly projected at $98 billion, far below U.S. levels.

Yet Chinese firms have achieved notable progress by focusing on cost-efficient innovation. For example, AI2 Robotics developed a model requiring less than 10% of the parameters used by Alphabet’s RT-2, demonstrating a commitment to leaner, more resource-conscious design.

Foreign investors are increasingly drawn to China’s cheaper valuations, which are roughly one-quarter of U.S. equivalents.

This efficiency stems from lower research costs, government-led initiatives, and a culture of frugality shaped by regulatory pressures and limited access to advanced hardware.

Rather than chasing scale, Chinese firms often prioritise practical applications and affordability, enabling broader adoption across industries.

Doing More with Less?

The evidence suggests that China has achieved competitive outcomes with far fewer resources, while the U.S. has arguably overpaid in pursuit of dominance.

However, the U.S. still leads in infrastructure, talent, and global influence. China’s strength lies in its ability to innovate under constraints, turning scarcity into efficiency.

Ultimately, the question is not whether one side has ‘overinvested’ or ‘underinvested’, but whether their strategies align with long-term sustainability.

The U.S. risks a bubble fuelled by excess capital, while China’s leaner approach may prove more resilient. In this sense, China is indeed ‘doing more with less’—but whether that will be enough to surpass U.S. dominance remains uncertain.

Bubble vulnerability

The sheer scale of U.S. AI investment has left the industry vulnerable to bubble shock, as valuations and spending appear increasingly detached from sustainable returns.

Analysts warn that the U.S. equity market is showing signs of an AI-driven bubble, with trillions poured into data centres, chips, and generative models at unprecedented speed.

While this has fuelled rapid innovation, it has also created irrational exuberance reminiscent of the dot-com era, where hype outpaces monetisation.

If growth expectations falter or capital tightens, the U.S. could face sharp corrections across tech stocks, credit markets, and employment, exposing the fragility of an industry built on extraordinary but potentially unsustainable levels of investment.

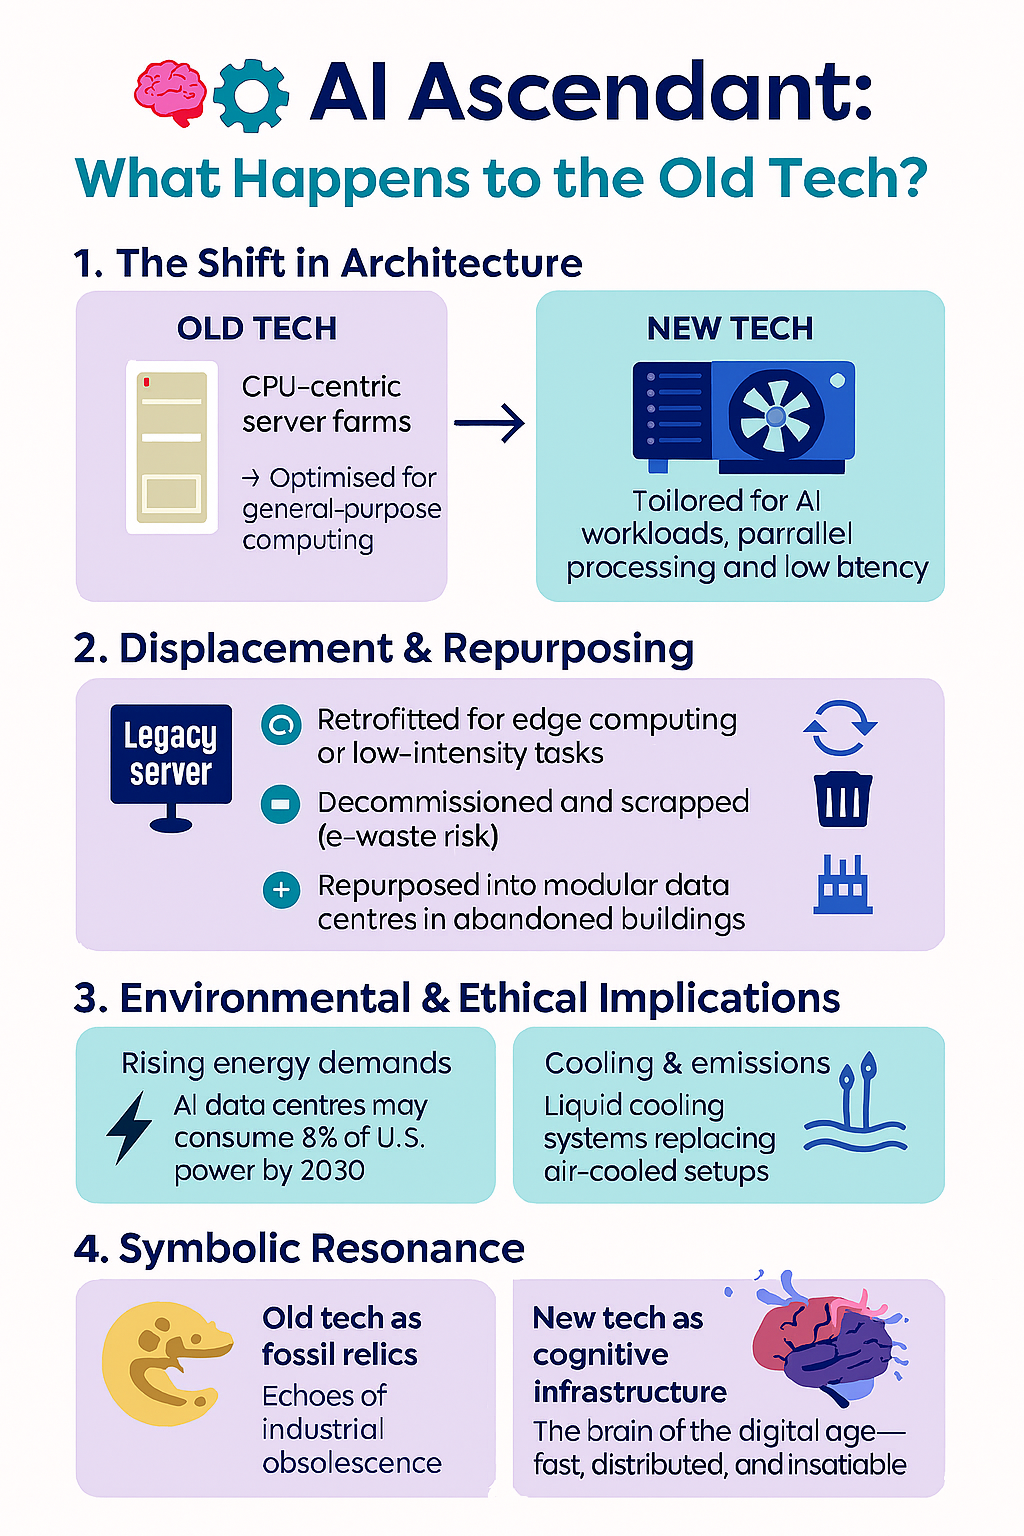
With all the new AI tech arriving in the new AI data centres – what is happening to the old tech it is presumably replacing?

AI - dirty little secret or clean?

🧠 What’s Happening to the Old Tech?

Shadow in the cloud

🔄 Repurposing and Retrofitting

  • Many traditional CPU-centric server farms are being retrofitted to support GPU-heavy or heterogeneous architectures.
  • Some legacy racks are adapted for edge computing, non-AI workloads, or low-latency services that don’t require massive AI computing power.

🧹 Decommissioning and Disposal

  • Obsolete hardware—especially older CPUs and low-density racks—is being decommissioned.
  • Disposal is a growing concern: e-waste regulations are tightening, and sustainability targets mean companies must recycle or repurpose responsibly.

🏭 Secondary Markets and Resale

  • Some older servers are sold into secondary markets—used by smaller firms, educational institutions, or regions with less AI demand.
  • There’s also a niche for refurbished hardware, especially in countries where AI infrastructure is still nascent.

🧊 Cold Storage and Archival Use

  • Legacy systems are sometimes shifted to cold storage roles—archiving data that doesn’t require real-time access.
  • These setups are less power-intensive and can extend the life of older tech without compromising performance.

⚠️ Obsolescence Risk

  • The pace of AI innovation is so fast that even new data centres risk early obsolescence if they’re not designed with future workloads in mind.
  • Rack densities are climbing—from 36kW to 80kW+—and cooling systems are shifting from air to liquid, meaning older infrastructure simply can’t keep up.

🧭 A Symbolic Shift

This isn’t just about servers—it’s about sovereignty, sustainability, and the philosophy of obsolescence. The old tech isn’t just being replaced; it’s being relegated, repurposed, or ritually retired.

There’s a tech history lesson unfolding about digital mortality, and how each new AI cluster buries a generation of silicon ancestors.

Infographic: ‘New’ AI tech replacing ‘Old’ tech in data centres

🌍 The Green Cost of the AI Boom

⚡ Energy Consumption

  • AI data centres are power-hungry beasts. In 2023, they consumed around 2% of global electricity—a figure expected to rise by 80% by 2026.
  • Nvidia’s H100 GPUs, widely used for AI workloads, draw 700 watts each. With millions deployed, the cumulative demand is staggering.

💧 Water Usage

  • Cooling these high-density clusters often requires millions of litres of water annually. In drought-prone regions, this is sparking local backlash.

🧱 Material Extraction

  • AI infrastructure depends on critical minerals—lithium, cobalt, rare earths—often mined in ecologically fragile zones.
  • These supply chains are tied to geopolitical tensions and labour exploitation, especially in the Global South.

🗑️ E-Waste and Obsolescence

  • As new AI chips replace older hardware, legacy servers are decommissioned—but not always responsibly.
  • Without strict recycling protocols, this leads to mountains of e-waste, much of which ends up in landfills or exported to countries with lax regulations.

The Cloud Has a Shadow

This isn’t just about silicon—it’s about digital colonialism, resource extraction, and the invisible costs of intelligence. AI may promise smarter sustainability, but its infrastructure is anything but green unless radically reimagined.

⚡ The Energy Cost of Intelligence

🔋 Surging Power Demand

  • AI data centres are projected to drive a 165% increase in global electricity consumption by 2030, compared to 2023 levels.
  • In the U.S. alone, data centres could account for 11–12% of total power demand by 2030—up from 3–4% today.
  • A single hyperscale facility can draw 100 megawatts or more, equivalent to powering 350,000–400,000 electric vehicles annually.
AI and Energy supply

🧠 Why AI Is So Power-Hungry

  • Training large models like OpenAI Chat GPT or DeepSeek requires massive parallel processing, often using thousands of GPUs.
  • Each AI query can consume 10× the energy of a Google search, according to the International Energy Agency.
  • Power density is rising—from 162 kW per square foot today to 176 kW by 2027, meaning more heat, more cooling, and more infrastructure.

🌍 Environmental Fallout

  • Cooling systems often rely on millions of litres of water annually. For example, in Wisconsin, two AI data centres will consume 3.9 gigawatts of power, more than the state’s nuclear plant.
  • Without renewable energy sources, this surge risks locking regions into fossil fuel dependency, raising emissions and household energy costs. We are not ready for this massive increase in AI energy production.

Just how clean is green?

The Intelligence Tax

This isn’t just about tech—it’s about who pays for progress. AI promises smarter cities, medicine, and governance, but its infrastructure demands a hidden tax: on grids, ecosystems, and communities.

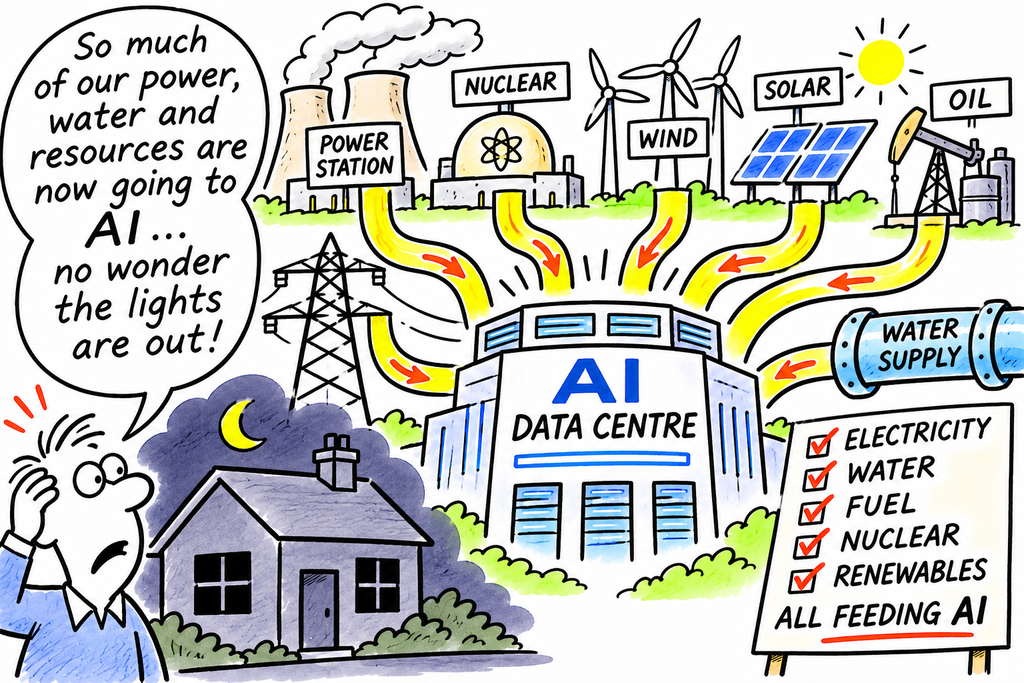
AI is a hungry beast, and it needs feeding. The genie is out of the bottle!

AI power – the energy hunger game!

Powering AI will not be clean...?

As artificial intelligence surges into every corner of modern life—from predictive finance to generative art—the question isn’t just what AI can do, but what it consumes to do it.

The energy appetite of large-scale AI models is no longer a footnote; it’s the headline.

Training a single frontier model can devour as much electricity as hundreds of UK homes use in a year. And once deployed, these systems don’t slim down—they scale up.

Every query, every image generation, every chatbot exchange draws from vast data centres, many powered by fossil fuels or water-intensive cooling systems.

The irony? AI is often pitched as a tool for climate modelling, yet its own carbon footprint is ballooning.

This isn’t just a technical dilemma—it’s a moral one. The race to build smarter, faster, more responsive AI has become a kind of energy arms race. Tech giants tout efficiency gains, but the underlying logic remains extractive: more data, more compute, more power.

Meanwhile, communities near data centres face water shortages, grid strain, and rising costs—all for services they may never use.

Future direction

Where is this heading? On one side, we’ll see ‘greenwashed’ AI—models marketed as sustainable thanks to token offsets or renewable pledges. On the other, a growing movement for ‘degrowth AI’: systems designed to be lean, local, and ethically constrained. Think smaller models trained on curated datasets, prioritising transparency over scale.

AI power – the energy hunger game! NASA’s ambition is to place nuclear power on the moon

Governments are waking up, too. The EU and UK are exploring energy disclosure mandates for AI firms, while some U.S. states are scrutinising water usage and land rights around data infrastructure. But regulation lags behind innovation—and behind marketing.

Ultimately, the energy hunger game isn’t just about watts and emissions. It’s about values. Do we want AI that mirrors our extractive habits, or one that challenges them? Can intelligence be decoupled from excess?

The next frontier isn’t smarter models—it’s wiser ones. And wisdom, unlike raw compute, doesn’t need a megawatt to shine.

Why Nuclear Is Back on the Table

  • Global Momentum: Thirty-one countries have pledged to triple nuclear capacity by 2050, framing it as a cornerstone of clean energy strategy.
  • AI’s Power Problem: With data centres projected to consume more energy than Japan by 2026, nuclear is being pitched as the only scalable, low-carbon solution that can deliver round-the-clock power.
  • Baseload Reliability: Unlike solar and wind, nuclear doesn’t flinch at nightfall or cloudy skies. That makes it ideal for powering critical infrastructure—especially AI, which can’t afford downtime.

🧪 Next-Gen Tech on the Horizon

  • Small Modular Reactors (SMRs): These compact units promise faster deployment, lower costs, and safer operation. China and Russia already have some online.
  • Fusion Dreams: Still experimental, but if cracked, fusion could offer near-limitless clean energy. It’s the holy grail—though still more sci-fi than supply chain.

⚖️ The Catch? Cost, Waste, and Public Trust

  • Nuclear remains expensive to build and politically fraught. Waste disposal and safety concerns haven’t vanished, and public opinion is split—especially in the UK.
  • Even with advanced designs, the spectres of Chernobyl and Fukushima linger in the cultural memory. That’s a narrative hurdle as much as a technical one.

🛰️ Moonshots and Geopolitics

  • NASA’s push to deploy a nuclear reactor on the moon by 2029 underscores how strategic this tech has become—not just for Earth, but for space dominance.
  • The U.S.–China race isn’t just about chips anymore. It’s about who controls the energy to power them.

Nuclear is staging a comeback—not as a relic of the past, but as a potential backbone of the future.

Whether it becomes the dominant force or a transitional ally depends on how fast we can build, how safely we can operate, and how wisely we choose to deploy.

🌍 How ‘clean’ is green?

According to MIT’s Climate Portal, no energy source is perfectly clean. Even solar panels, wind turbines, and nuclear plants come with embedded emissions—from mining rare metals to manufacturing components and transporting them.

So, while they don’t emit greenhouse gases during operation, their setup and maintenance do leave a footprint.

How CLEAN is GREEN? Explainers | MIT Climate Portal

⚖️ Lifecycle Emissions Comparison

Here’s how different sources stack up in terms of CO₂ emissions per kilowatt hour:

Energy SourceCO₂ Emissions (g/kWh)Notes
Coal~1,000Highest emissions, plus toxic byproducts
Natural Gas~500Cleaner than coal, but still fossil-based
Solar<50Mostly from manufacturing panels
Wind~10Lowest emissions, mostly from materials
Nuclear (SMR/SNR)~12–20Low emissions, but waste and safety debates linger

Source: MIT Climate Portal

Big tech companies are increasingly adopting nuclear power to meet the high energy demands of their AI data centres

Data centre powered by nuclear reactors

Why?

Elevated Energy Needs

AI systems, particularly generative AI, necessitate substantial computational power, leading to significant energy use. Conventional energy sources might not meet these growing demands.

Environmental Commitments

Numerous tech firms have pledged to lower their carbon emissions. Nuclear power, a low-emission energy source, supports these environmental commitments.

Dependability

Nuclear energy offers a consistent and uninterrupted power supply, essential for data centres that operate around the clock.

Technological Advancements

Progress in nuclear technologies, such as small modular reactors (SMRs), has enhanced the feasibility and appeal of nuclear power for extensive use.

For example, Google has entered into an agreement with Kairos Power for electricity from small modular reactors to bolster its AI operations. In a similar vein, Microsoft has collaborated with Constellation to refurbish an inactive reactor at the Three Mile Island nuclear facility.

These collaborations mark a notable transition in the energy strategies of the tech sector, as they pursue dependable, eco-friendly, and robust power solutions to support their AI initiatives.

Desert location for energy and power generation

Electricity infrastructure

Will these projects alter the world weather pattern?

According to a study, installing large-scale wind and solar farms in the Sahara desert could increase rainfall and vegetation in the region. The researchers simulated the effects of covering 20% of the Sahara with solar panels and wind turbines and found that it would trigger a feedback loop of more monsoon rain and more plant growth.

This could have benefits for the local environment and the global climate, as well as providing a huge amount of clean energy for the world.

Could it also create a detrimental effect to the ecosystem too?

10.5 GW solar energy

The desert project would produce 10.5 GW of solar power and 3 GW of wind power. However, there are also challenges and uncertainties involved, such as the cost, feasibility, and environmental impacts of such a massive undertaking.

The Sahara is a desert on the African continent. With an area of 9,200,000 square kilometres, it is the largest hot desert in the world and the third-largest desert overall, smaller only than the deserts of Antarctica and the northern Arctic.

Daily global electricity energy demand

The global electricity energy demand is the amount of electricity that the world needs in a given day. It can be calculated by multiplying the average global electricity demand in GW by 24 hours. According to the International Energy Agency (IEA), the average global electricity demand in 2020 was about 3 TW or 3 000 GW. This means that the global electricity energy demand in 2020 was about 72 000 GWh or 72 TWh per day. However, this is an average value, and the actual demand may vary depending on the season, time of day, weather, and other factors.

The global electricity energy demand is expected to increase in the future, as population grows and living standards improve. The IEA projects that the average global electricity demand will reach 3.8 TW or 3 800 GW by 2030 and 5.2 TW or 5 200 GW by 2050 in the Announced Pledges Scenario, which reflects the full implementation of net-zero emissions targets by some countries and regions. This implies that the global electricity energy demand will reach 91 200 GWh or 91.2 TWh per day by 2030 and 124 800 GWh or 124.8 TWh per day by 2050.

Energy sources

The sources of electricity generation will also change in the future, as renewable technologies such as solar PV and wind become more dominant and coal use declines. The IEA reports that the main sources of electricity generation in 2020 were coal (34%), natural gas (23%), hydropower (16%), nuclear (10%), wind (8%), solar PV (4%), biofuels and waste (3%), and other renewables (2%).

The researchers simulated the effects of covering 20% of the Sahara with solar panels and wind turbines and found that it would trigger a feedback loop of more monsoon rain and more plant growth.

In the Announced Pledges Scenario, renewables in electricity generation rise from 28% in 2021 to about 50% by 2030 and 80% by 2050.

Powering the UK from energy created in Morocco

Japan Fukushima controversial water release

Tap waste water

Japan has started releasing treated radioactive water from the Fukushima nuclear plant into the Pacific Ocean on Thursday 25th August 2023. 

This is a controversial decision that has been opposed by China, South Korea, and some Pacific island nations. They fear that the water release will harm the marine environment and human health, and affect seafood exports.

Safe?

Japan says that the water release is safe and necessary for the decommissioning of the plant, which was damaged by a massive earthquake and tsunami in 2011. The water has been treated to remove most of the radioactive substances, except for tritium and carbon-14, which are considered to have low risks. The water will also be diluted to meet the international standards for drinking water before being discharged.

IAEA

The International Atomic Energy Agency (IAEA) has endorsed Japan’s plan and said that the water release will have a negligible impact on people and the environment. The IAEA will also monitor the water release and verify Japan’s compliance with the safety standards.

30 years

The water release is expected to take about 30 years to complete, and will involve pumping out about 1.34 million tonnes of water from more than 1,000 tanks at the Fukushima site.

Contaminated water
Japan Fukushima nuclear plant controversial release of potentially contaminated water