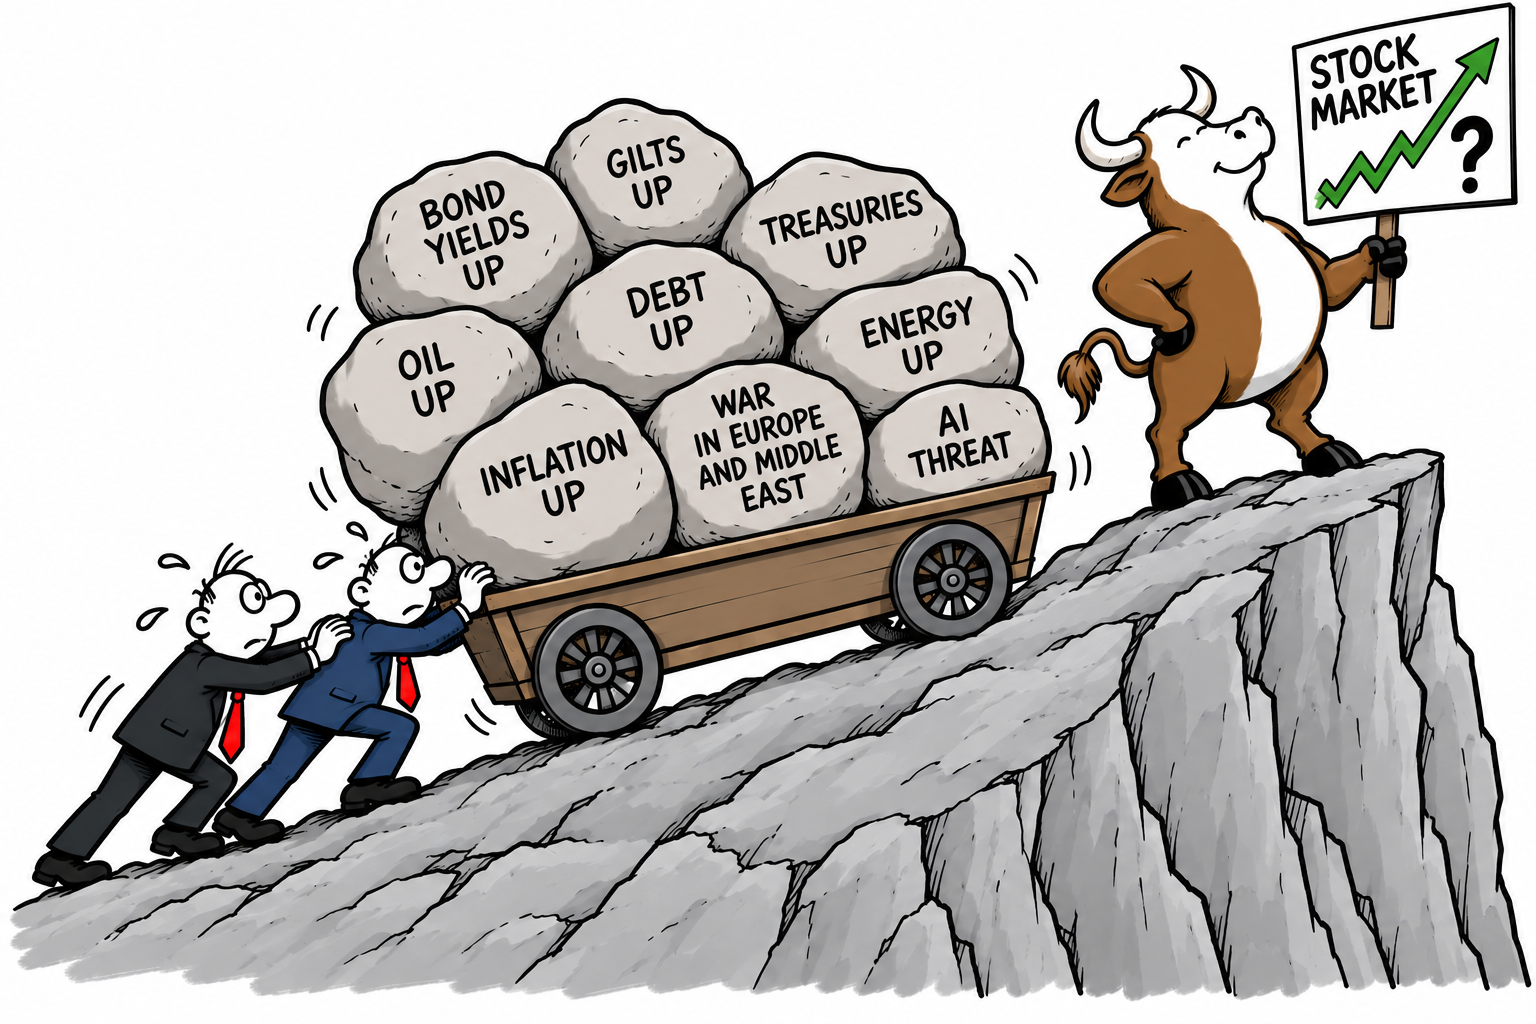
There was a time when any one of these developments would have been enough to frighten investors: rising government bond yields, higher borrowing costs, stubborn inflation, soaring oil and energy prices, mounting government debt, war in Europe and the Middle East and tariff wars.
And now with the growing threat of AI safety and concerns about whether the enormous investment in artificial intelligence can continue at its current pace.
Put them all together and, logically, the stock market should be facing a serious test.
Yet it continues to demonstrate remarkable resilience.
Irony
The irony is that many of these pressures are already showing up in financial markets. U.S. Treasury yields have moved above 5%, their highest levels since 2007, while oil has climbed above $100 a barrel.
Rising energy prices are feeding inflation concerns, while higher yields are increasing the cost of borrowing. Reuters reported on Tuesday that the Dow, S&P 500 and Nasdaq all fell, but the declines remained relatively contained.
So why hasn’t this combination produced a much larger correction?
One explanation is that markets are not simply pricing today’s problems. They are pricing what investors believe the world will look like several months or years from now – or so we are told.
Corporate earnings remain a powerful counterweight. If profits continue to grow rapidly, investors can tolerate higher interest rates and higher valuations for longer.
Reuters notes that continued earnings growth and enthusiasm surrounding AI have helped keep U.S. equities relatively resilient despite the rise in Treasury yields.
There is also an extraordinary amount of money invested in equities. Pension funds, investment funds, corporations and individual investors cannot simply abandon shares every time the economic outlook deteriorates.
There are relatively few places capable of absorbing enormous amounts of capital.
Don’t sell – carry on regardless
And perhaps most importantly, investors have repeatedly learned that selling during every crisis can be expensive.
Inflation? The market survived it.
War? Markets have survived wars before – but markets did correct.
Tariffs – markets have shrugged there off!
Higher interest rates? Markets can rise during tightening cycles if the economy and corporate profits remain strong.
Oil shocks? They can damage consumers and businesses, but they can simultaneously boost the profits of energy companies.
Even the AI problem is complicated. A slowdown in AI investment could hurt some enormously valued technology companies, but it would not necessarily destroy the entire economy.
Indeed, markets have already shown that AI concerns can cause sector-specific selling without automatically triggering a broad collapse.
The real question, therefore, may not be why the market hasn’t fallen.
It is what would finally make investors collectively stop believing that the next problem can be absorbed?
Because markets rarely collapse simply because there are lots of problems.
They collapse when investors suddenly decide that those problems can no longer be ignored.
Stock market offers ‘easy money’?
It certainly sounds like easy money — if only markets worked that way. The danger is assuming that resilience means invincibility: a market can shrug off one problem, then another, and even several simultaneously, right up until investors collectively decide that earnings, valuations, interest rates or economic growth no longer justify the prices they are paying.
Until that moment arrives, bad news can simply be absorbed, explained away or declared temporary; when it does arrive, however, the same market that seemed capable of ignoring everything can suddenly discover that everything matters after all.
Difficulty
The difficult part is that there is no reliable way to say when it will happen — markets can remain expensive and resilient for considerably longer than economic logic might suggest.
The eventual correction is more likely to come when several pressures stop being viewed as temporary or manageable and begin to undermine the assumptions supporting corporate earnings and valuations: persistently high inflation, materially higher borrowing costs, weaker growth, falling profits, an AI investment slowdown, or an unexpected financial shock could each become the catalyst.
Until investors collectively change their expectations, the market can continue climbing despite an increasingly uncomfortable list of warning signs — but resilience should not be confused with immunity.