Global debt has reportedly surged to $365 trillion, prompting economists to warn about a looming ‘vicious cycle’

Debt and the beggar

The combination of record global debt, higher borrowing costs and growing doubts about the enormous sums being committed to artificial intelligence is creating a more complicated backdrop for financial markets.

Global debt exceeded $365 trillion in the first half of 2026, according to the Institute of International Finance, with debt now around 310% of global GDP.

China and the U.S. debt mountain

The increase was driven particularly by China and the United States. At the same time, higher interest rates are making refinancing increasingly expensive, creating the possibility of a vicious cycle in which governments and companies borrow more simply to service existing obligations.

This is particularly significant for the AI boom. The OECD says governments and companies are expected to borrow around $29 trillion from markets during 2026, while corporate borrowing is also rising as businesses finance major investment programmes, including AI infrastructure.

Michael Burry

Michael Burry, famous for anticipating the U.S. housing crisis, has added another warning sign.

He has recently reportedly increased bearish positions involving Micron, Palantir, Nebius and the semiconductor sector, arguing that parts of the AI and chip boom could be vulnerable if supply increases faster than demand.

The concern is not necessarily that AI will fail. Rather, enormous investment and borrowing require enormous future revenues to justify them.

If AI spending produces lower-than-expected returns, highly valued technology shares could face pressure at the same time as heavily indebted companies face rising financing costs.

Could this affect the stock market now?

The ingredients for greater volatility are certainly present. Higher bond yields, expensive energy, inflation pressures and debt-servicing costs can compete with equities for investors’ money.

Reuters recently reported that global borrowing costs and energy prices were already creating concerns about the potential impact on equities and credit markets.

Yet markets have so far remained remarkably resilient, with U.S. shares still close to record levels.

The danger, therefore, may not be debt alone, but…

debt + high valuations + expensive AI investment + higher interest rates.

If those pressures reinforce one another, the adjustment in markets could become considerably more significant.
Why Are Markets Still Rising Despite Ongoing Bad World News?

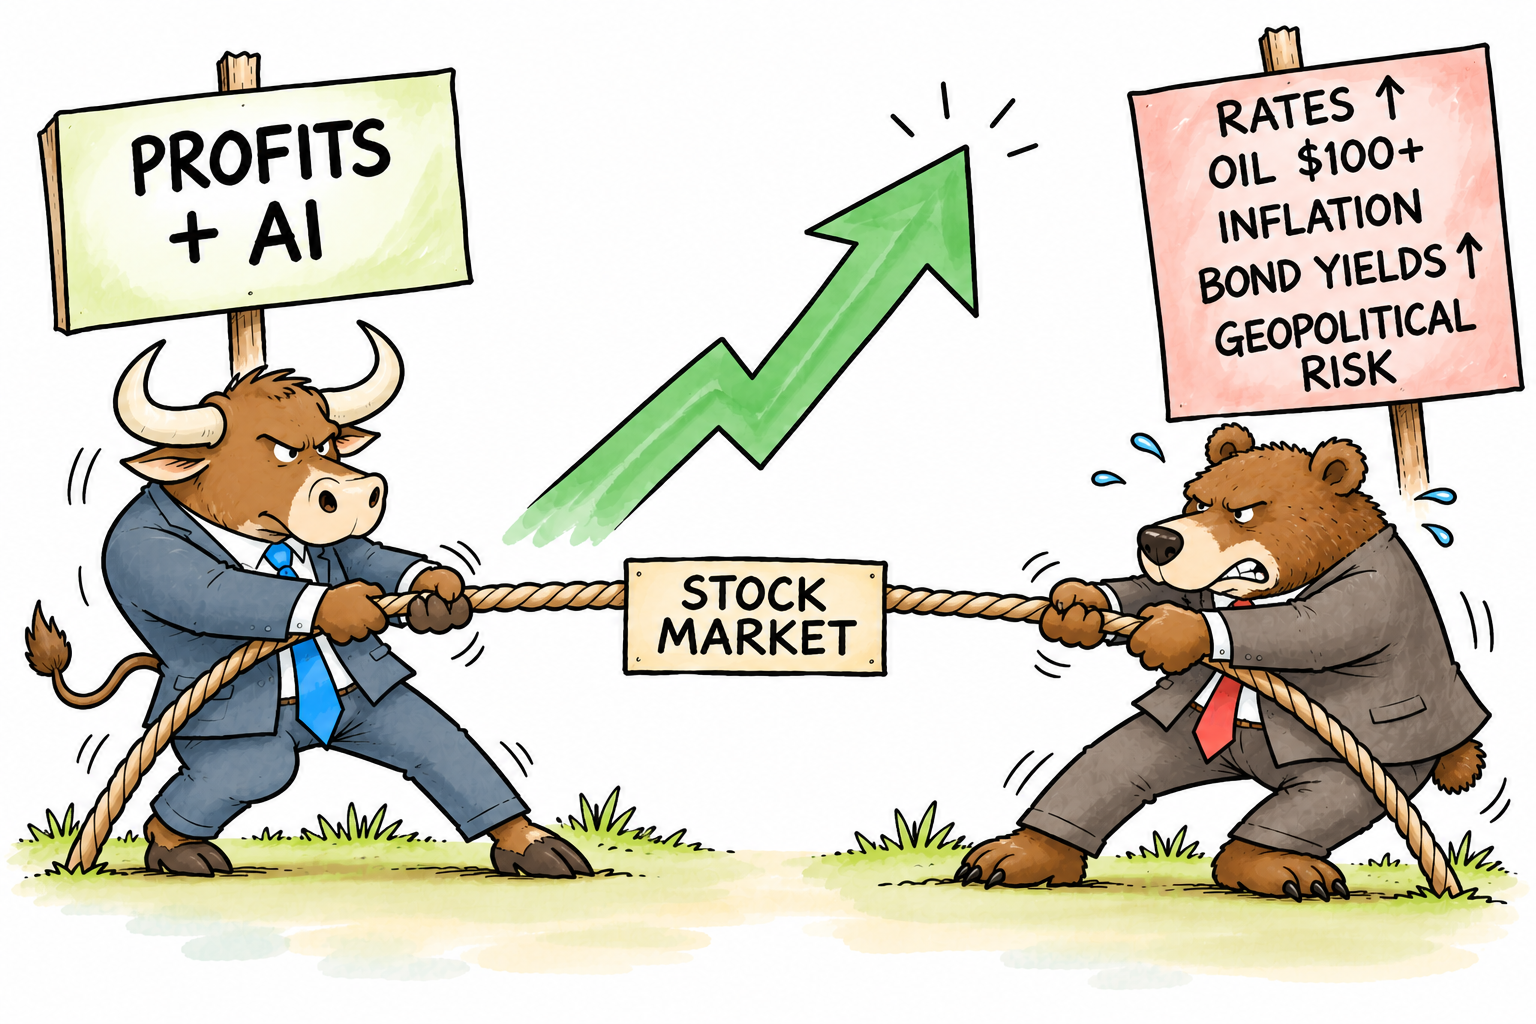
Stock market tug-o-war

Stock markets are continuing to climb despite a growing list of concerns that would normally be expected to unsettle investors.

Interest rates are higher, government bond yields have risen, oil prices are elevated and inflation remains a concern. Geopolitical tensions are also creating uncertainty. Tariffs still on the agenda. Global debt rising and rogue AI concerns.

Yet investors continue to buy shares, particularly in the United States.

So why?

One important reason is corporate earnings. Investors appear willing to tolerate higher interest rates and expensive valuations while they believe company profits will continue to grow.

Large technology companies, in particular, remain at the centre of this optimism, with huge investment in artificial intelligence fuelling expectations of strong future earnings.

Buying dips

Another factor is the willingness of investors to buy market dips. When share prices fall, investors who remain confident about the longer-term outlook see an opportunity to buy at cheaper prices.

This can create a self-reinforcing cycle: markets fall, buyers move in, confidence returns and prices rise again.

There is also a belief that the economy remains sufficiently resilient to withstand higher borrowing costs and expensive energy.

Bad news is therefore being viewed as a problem, but not necessarily one capable of seriously damaging corporate profits.

However, this resilience could eventually be tested.

Earnings faith

The market is currently placing considerable faith in continued earnings growth and the economic benefits of artificial intelligence. If either begins to disappoint, investors could reassess the high valuations attached to many shares.

Higher oil prices could also keep inflation elevated, forcing interest rates to remain higher for longer. Rising bond yields would then provide investors with an increasingly attractive alternative to shares.

Bull Bear

For now, the bulls remain in control of market prices, even though the bears have plenty of arguments on their side.

The important question is whether company profits can continue to justify today’s share prices.

If they can, markets may continue climbing despite the bad news. If they cannot, investors may suddenly start paying much closer attention to all those warning signs they have recently been ignoring.