VIX Surges as Wall Street Braces for More Turbulence

VIX Fear Gauge

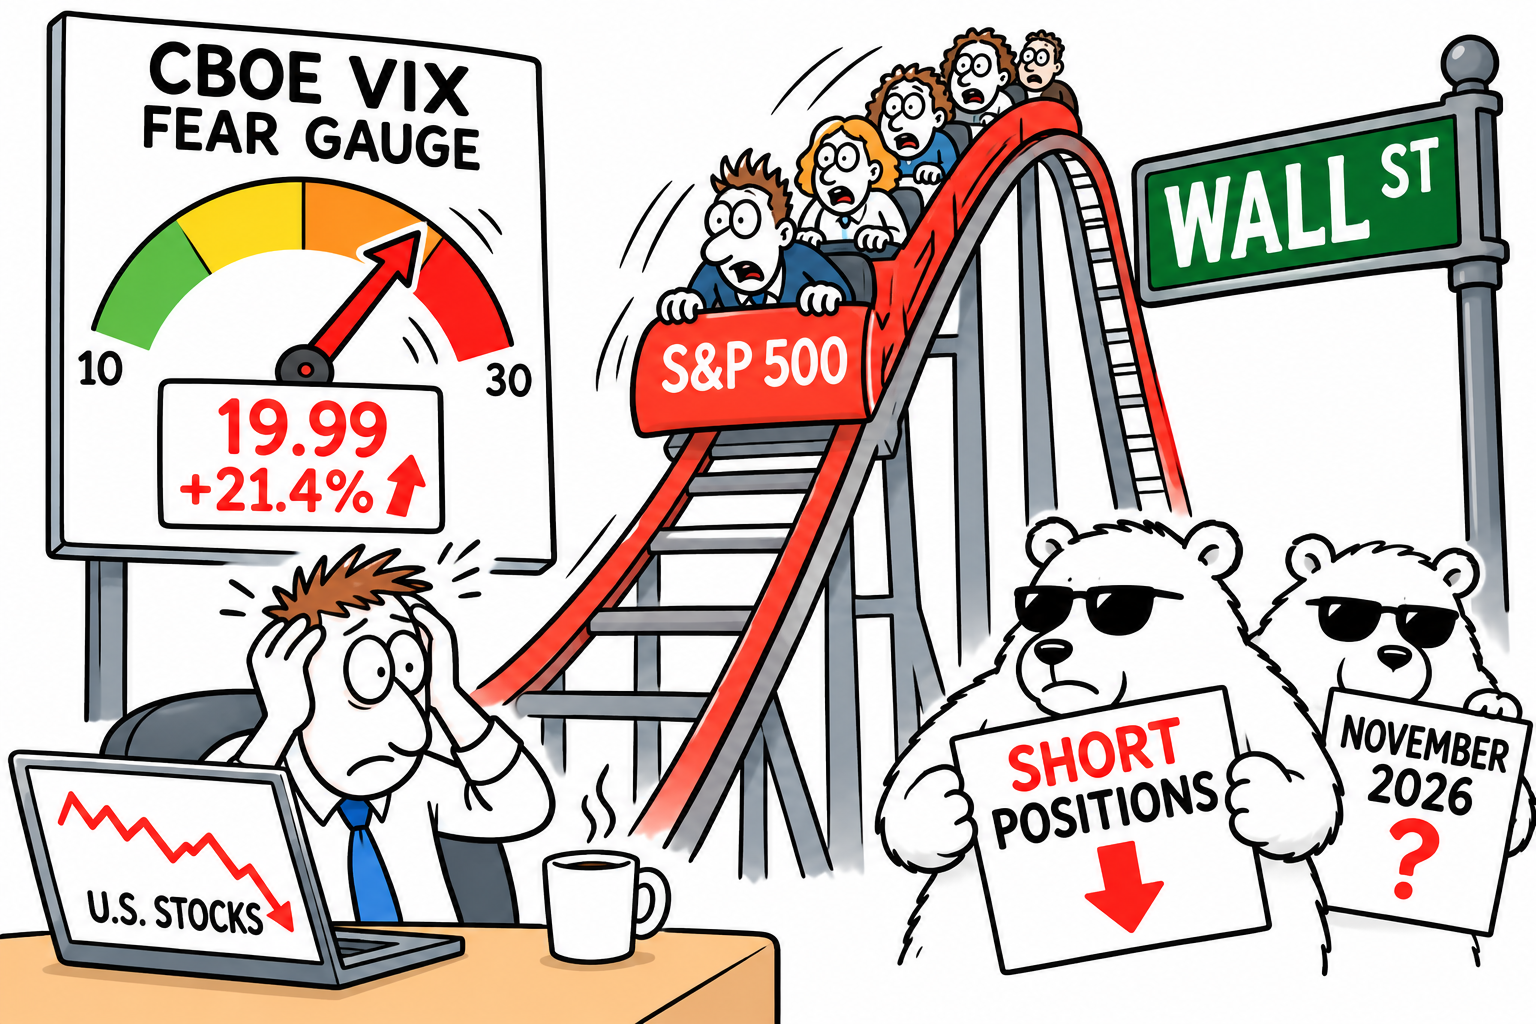
Wall Street’s fear gauge surged on Friday, 16th October 2026, as investors rushed to protect themselves against further market volatility.

The CBOE Volatility Index (VIX) jumped by 21.4% to close at 19.99, its highest closing level since late July 2026. The S&P 500 fell, while technology and semiconductor shares came under renewed pressure.

Volatility

The VIX measures the volatility investors expect in the S&P 500 over the coming 30 days, using options prices. A sharp rise indicates growing uncertainty and increased demand for protection against falling share prices.

It does not, however, predict a crash. A sustained move above 30 would suggest considerably greater market anxiety.

The concern is that rising volatility coincides with worries over expensive technology stocks, artificial intelligence investment, inflation, oil prices and borrowing costs. If investors begin reducing risk across the market, further falls could follow.

Bearish signals

There is also evidence of bearish positioning ahead of November 2026. The latest U.S. futures data show speculative traders holding a net short position of approximately 141,000 S&P 500 contracts as of 13th October.

This suggests some traders are positioning for weakness, although futures can also be used for hedging.

The combination of rising volatility and substantial short positions deserves attention. It is a warning sign, not proof of an impending crash.

NOTE:

What to watch next: If the VIX continues rising while the S&P 500 falls, the warning becomes more serious. Equally, a rapid decline in the VIX could indicate that investor anxiety is easing.

One important qualification: the futures figures show bearish positioning, but they do not establish that traders are specifically targeting November 2026 at this time.
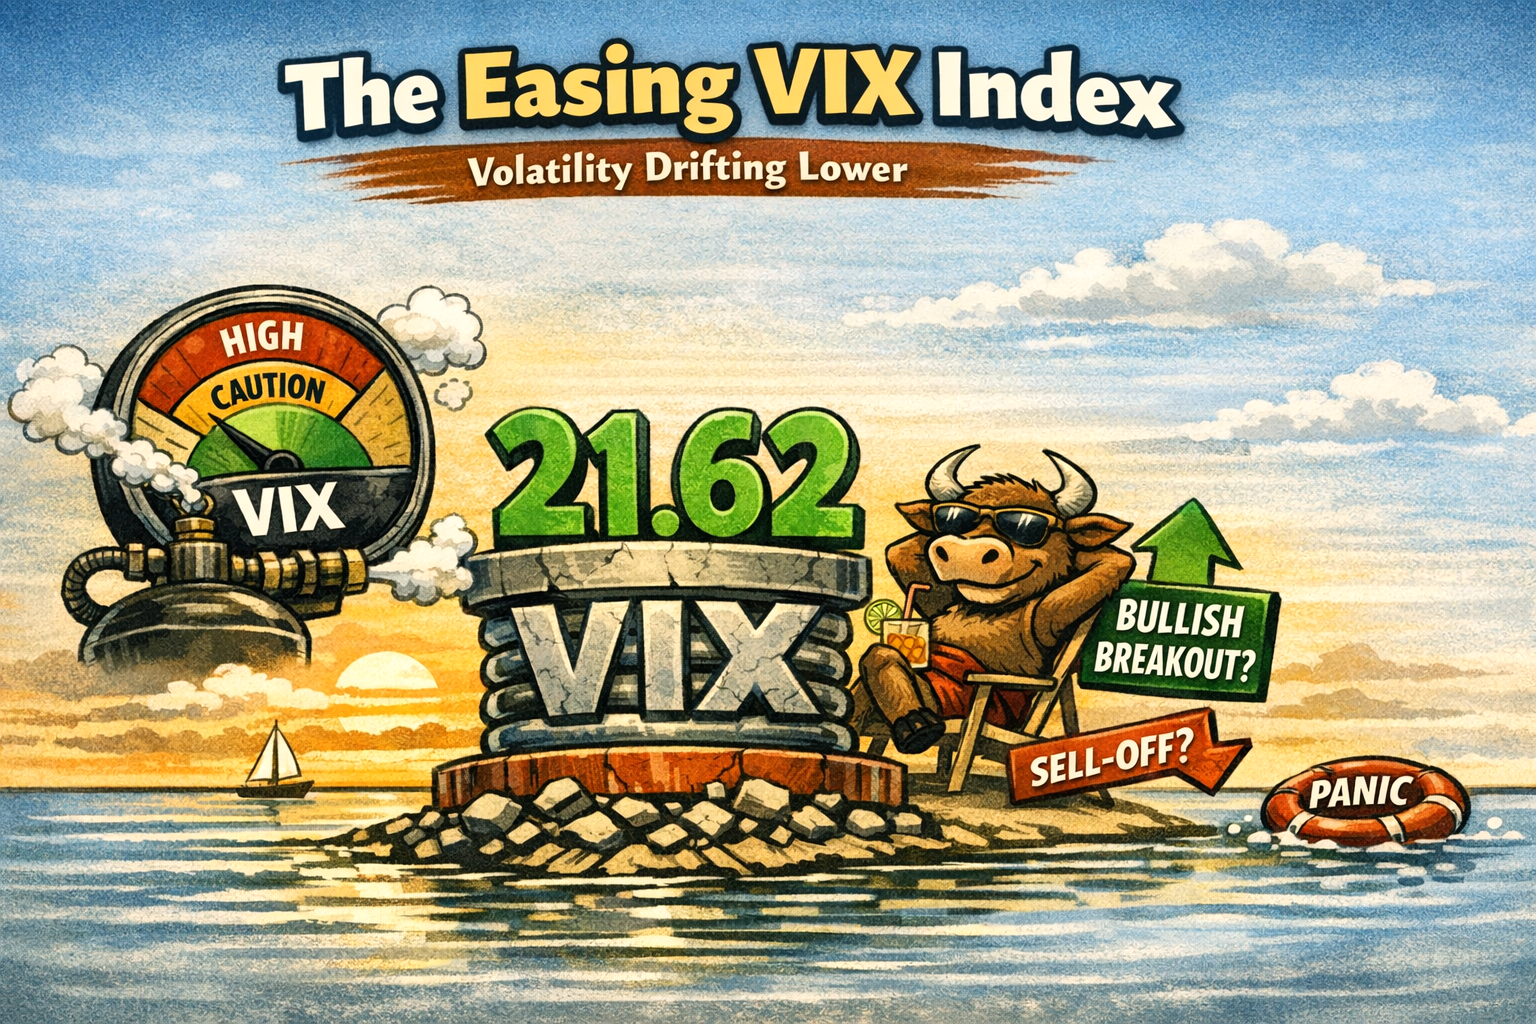
What does the VIX have to say about the current stock market?

VIX snapshot

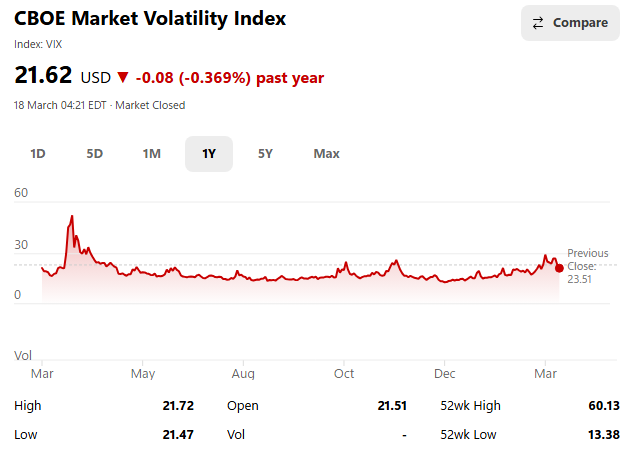
The VIX index currently (18th March 2026 – 8:30GMT) at 21.62, down around 8% from its previous close of 23.51. This drop suggests a modest easing in market fear, despite looming catalysts like the Fed decision and geopolitical tension.

VIX Snapshot – 18th March 2026

MetricValue
Current Price21.62 USD
Previous Close23.51 USD
Day Change−1.89 Down 8%
Intraday High/Low21.72 / 21.47
52-Week High/Low60.13 / 13.38
One-year market volatility index snapshot image 18th March 2026 at approx: 08:30 GMT

Implications

Still Elevated: A VIX above 20 suggests lingering unease, even if not full-blown panic.

Compression Context: This aligns with your “coiled spring” thesis — volatility is contained but not absent.

Directional Bias: If VIX continues to fall post-Fed, it supports a bullish breakout. A spike, however, would signal risk-off sentiment and potential sell-off.

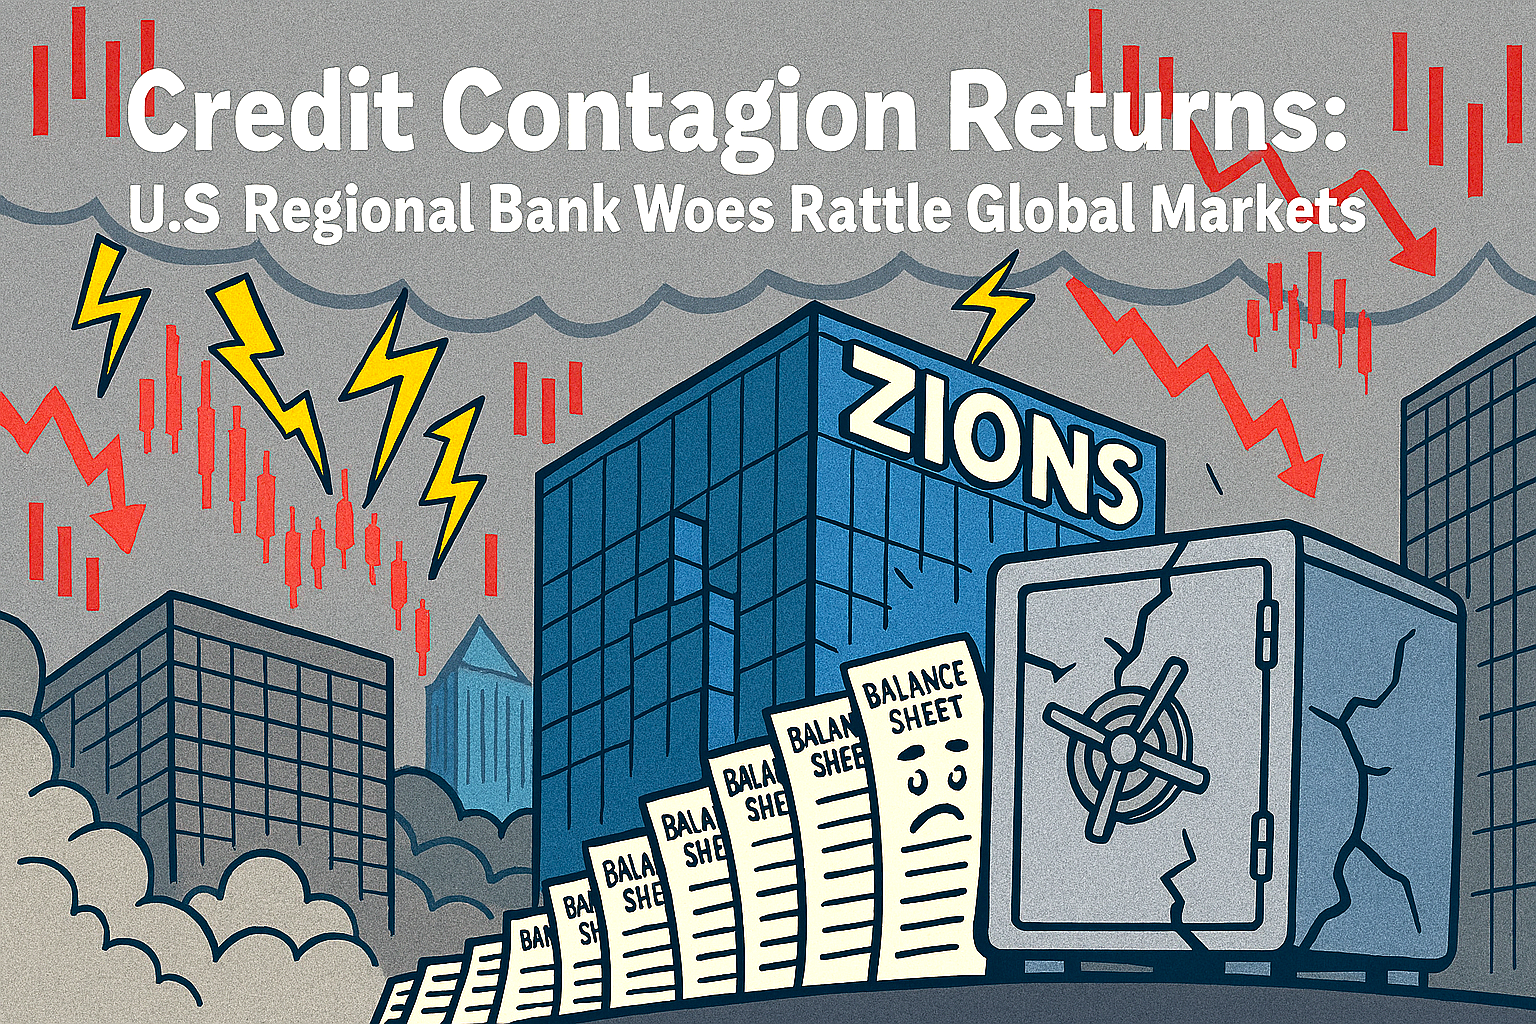
Concerns about credit contagion are back as troubles in U.S. regional banks shake global markets

U.S. Bank Credit Woes!

On Friday 17th October 2025, a fresh wave of credit concerns erupted across financial markets, triggered by troubling disclosures from U.S. regional lenders Zions Bancorporation and Western Alliance.

Both banks revealed significant exposure to deteriorating commercial real estate loans, reigniting fears of systemic fragility just months after the collapse of Silicon Valley Bank and Signature Bank.

The revelations sent shockwaves through Wall Street. Shares in Zions plunged over 11% in early trading, while Western Alliance dropped nearly 9%.

Larger institutions weren’t spared either—JP Morgan, Bank of America, and Citigroup all saw declines, as investors reassessed the health of the broader banking sector.

Volatile

The CBOE Volatility Index (VIX), often dubbed Wall Street’s ‘fear gauge’, spiked to its highest level since April, signalling a sharp uptick in investor anxiety.

The panic quickly spread across the Atlantic. UK lenders bore the brunt of the fallout, with Barclays tumbling 6.2%, Standard Chartered down 5.4%, and NatWest shedding 4.8%.

£13 billion loss to UK banks

In total, nearly £13 billion was reportedly wiped off the value of British banks in a single trading session. The FTSE 100 closed down 1.5%, its worst performance in over a month.

At the heart of the crisis lies commercial real estate—a sector battered by high interest rates, remote working trends, and declining occupancy. U.S. regional banks, which often hold concentrated portfolios of property loans, are particularly vulnerable.

Analysts warn that rising defaults could trigger a domino effect, undermining confidence in institutions previously deemed stable.

The Bank of England’s Financial Stability Report had already flagged elevated risks from global fragmentation and sovereign debt pressures. As did the IMF Financial Stability Report.

Credit outlook review

The events of Friday 17th October 2025 appear to validate those concerns, with Moody’s and other agencies now reviewing credit outlooks for multiple institutions.

While some commentators view the sell-off as a temporary overreaction, others see it as a harbinger of deeper trouble.

The symbolic resonance is hard to ignore: vaults cracking, balance sheets buckling, and trust—once again—on the brink. Why?

For editorial observers, the moment invites reflection. Is this merely a cyclical tremor, or the start of a structural reckoning?

Either way, the illusion of resilience has been punctured. And as markets brace for further disclosures, the spectre of contagion looms large.

Remember the sub-prime loans fiasco?

I thought banks were ‘funded and ring-fenced’ more now to prevent this from happening again.