Nasdaq hits record high as AI rally returns

New Nasdaq high!

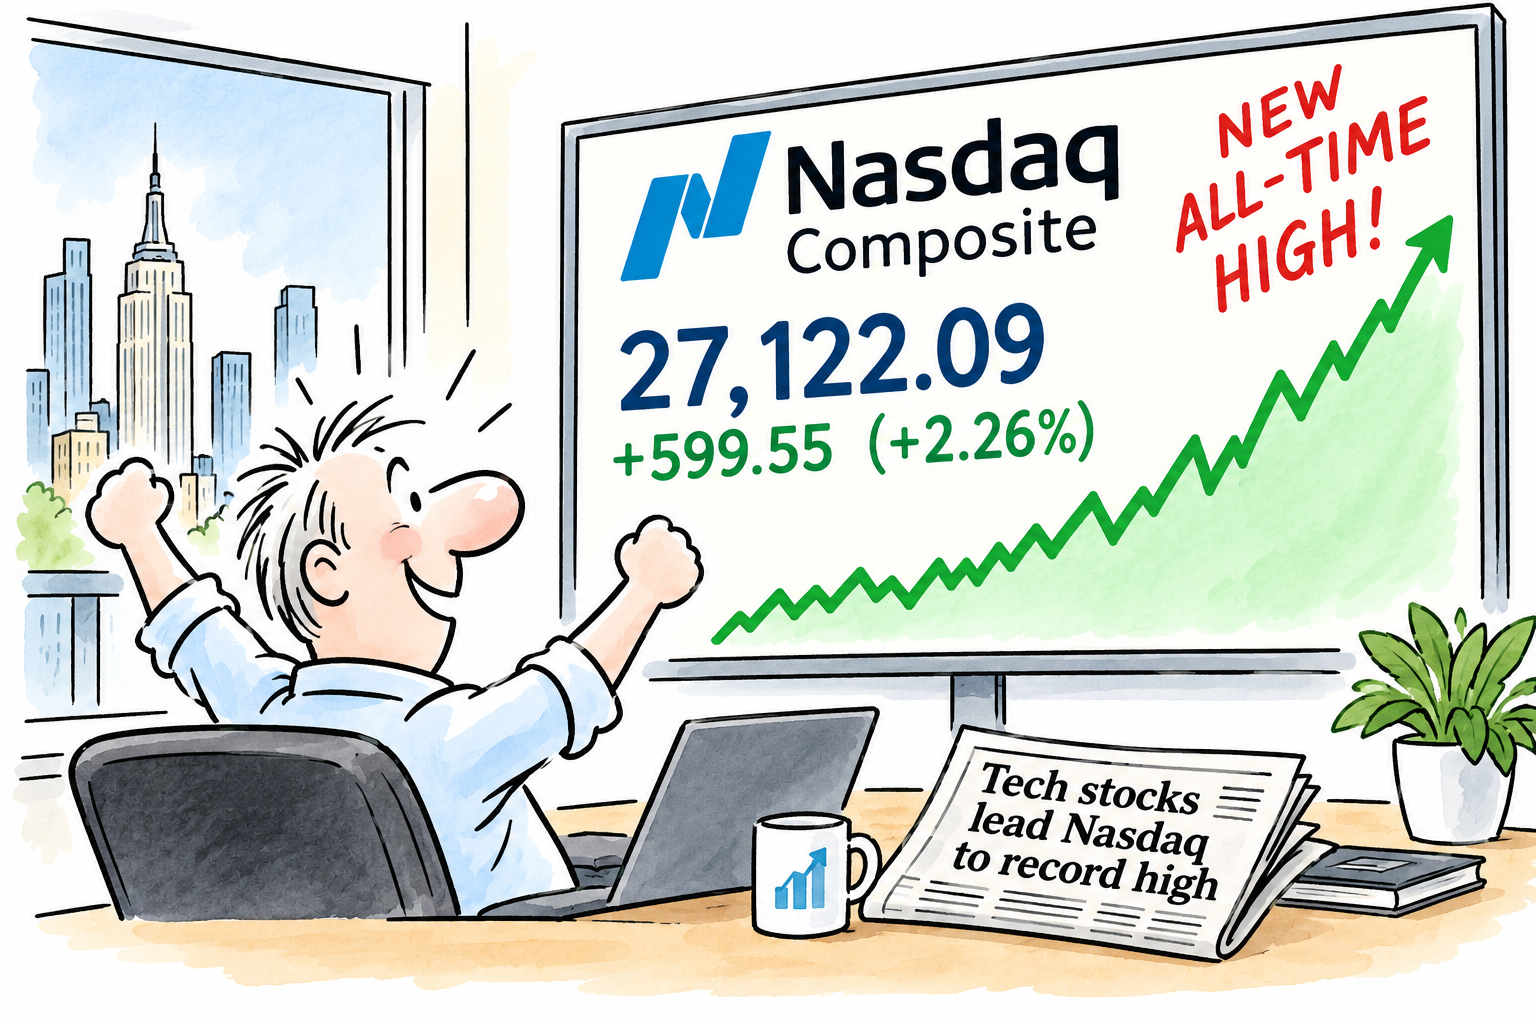
The Nasdaq Composite surged to a fresh all-time closing high on Monday 21st September 2026, as renewed enthusiasm for artificial intelligence helped drive a powerful rally in technology stocks.

The index jumped 2.26% to 27,122.09, surpassing its previous record close set in June 2026. It also reached an intraday high of 27,183.93.

Chipmakers were among the biggest beneficiaries. AMD soared almost 10%, taking its market value above $1 trillion, while Intel gained more than 12% and Arm Holdings also posted a double-digit rise.

AI Frenzy

The renewed appetite for AI stocks came despite recent concerns over the sector’s lofty valuations and potential risks surrounding rapid AI development.

Falling oil prices and a retreat in U.S. Treasury yields also helped improve investor sentiment. The Nasdaq’s record finish marked its first since 2nd June 2026, highlighting the strength of Monday’s technology-led rebound.

Uncertain Backdrop

Yet the record comes against an unusually uncertain backdrop. Investors are navigating concerns over AI valuations and the huge borrowing by some AI hyperscalers, while much of the AI boom is also linked through a web of interconnected investments, partnerships and business deals between major technology companies.

Alongside this are wars in Ukraine and the Middle East, oil-supply concerns, elevated energy and fuel costs, tariffs, higher bond yields and already substantial levels of government and corporate debt.

Subdued

Consumer confidence also remains subdued in many economies. The Nasdaq’s strength therefore presents a striking contrast with the economic, financial and geopolitical uncertainties surrounding markets.

So much of the AI boom is ‘linked’ through big, interconnected AI business deals.

Will this unravel as the AI convoy continues its journey?

Why Won’t the Stock Market Correct – Especially with all the Issues Facing it?

Stock Market Correction Soon?

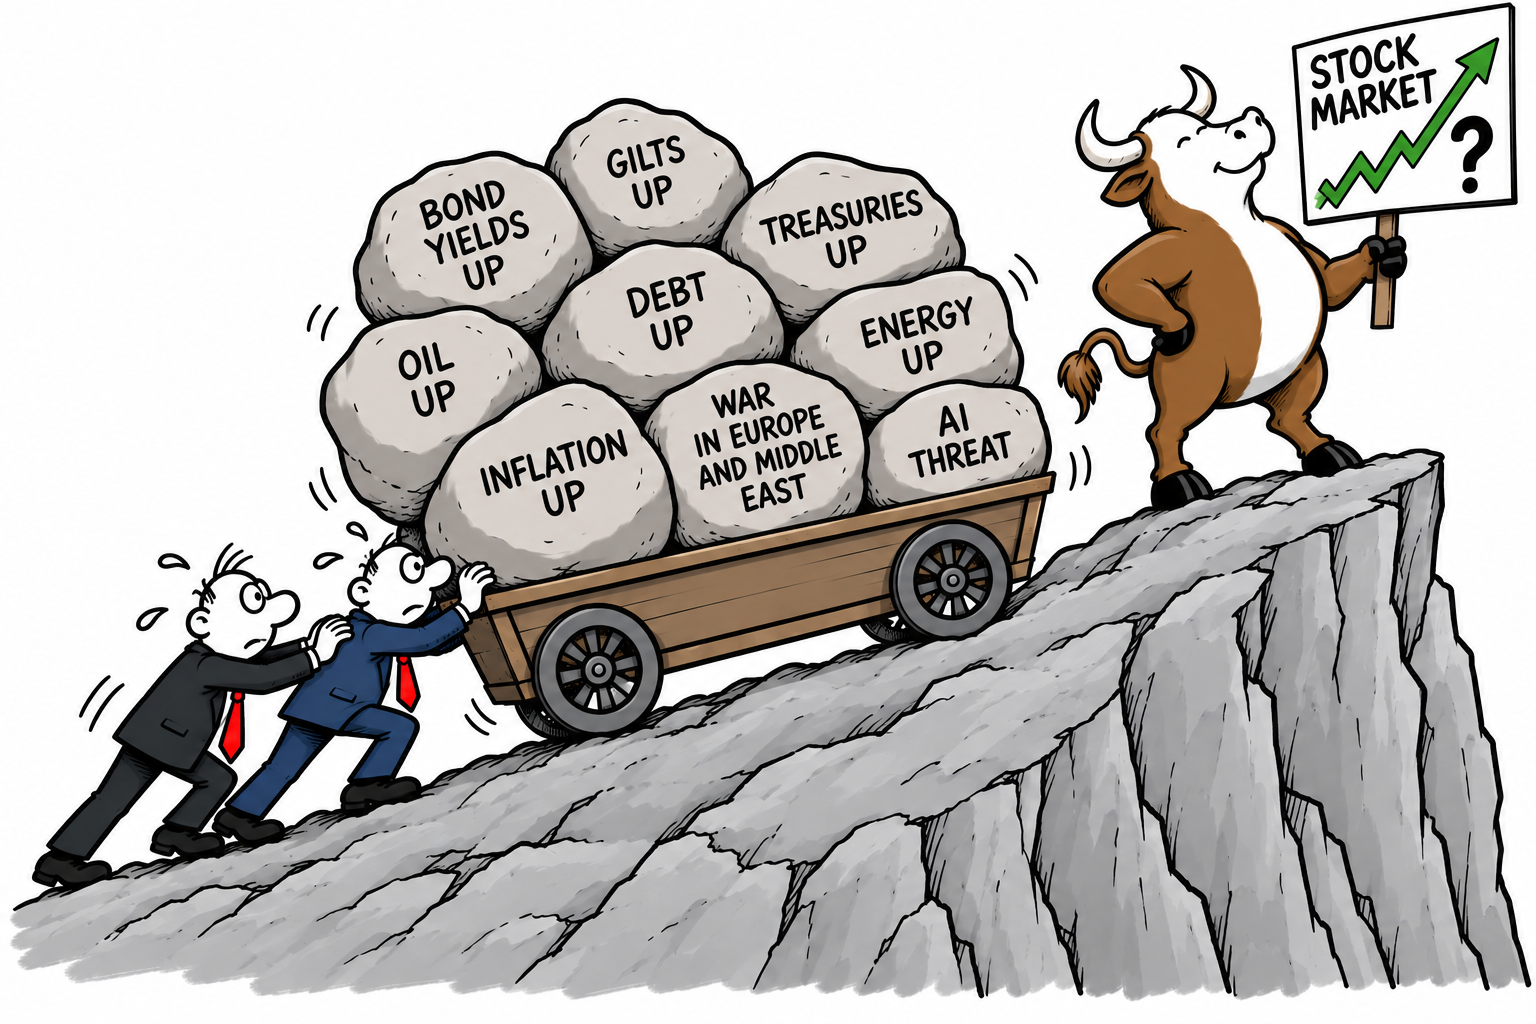
There was a time when any one of these developments would have been enough to frighten investors: rising government bond yields, higher borrowing costs, stubborn inflation, soaring oil and energy prices, mounting government debt, war in Europe and the Middle East and tariff wars.

And now with the growing threat of AI safety and concerns about whether the enormous investment in artificial intelligence can continue at its current pace.

Put them all together and, logically, the stock market should be facing a serious test.

Yet it continues to demonstrate remarkable resilience.

Irony

The irony is that many of these pressures are already showing up in financial markets. U.S. Treasury yields have moved above 5%, their highest levels since 2007, while oil has climbed above $100 a barrel.

Rising energy prices are feeding inflation concerns, while higher yields are increasing the cost of borrowing. Reuters reported on Tuesday that the Dow, S&P 500 and Nasdaq all fell, but the declines remained relatively contained.

So why hasn’t this combination produced a much larger correction?

One explanation is that markets are not simply pricing today’s problems. They are pricing what investors believe the world will look like several months or years from now – or so we are told.

Corporate earnings remain a powerful counterweight. If profits continue to grow rapidly, investors can tolerate higher interest rates and higher valuations for longer.

Reuters notes that continued earnings growth and enthusiasm surrounding AI have helped keep U.S. equities relatively resilient despite the rise in Treasury yields.

There is also an extraordinary amount of money invested in equities. Pension funds, investment funds, corporations and individual investors cannot simply abandon shares every time the economic outlook deteriorates.

There are relatively few places capable of absorbing enormous amounts of capital.

Don’t sell – carry on regardless

And perhaps most importantly, investors have repeatedly learned that selling during every crisis can be expensive.

Inflation? The market survived it.

War? Markets have survived wars before – but markets did correct.

Tariffs – markets have shrugged there off!

Higher interest rates? Markets can rise during tightening cycles if the economy and corporate profits remain strong.

Oil shocks? They can damage consumers and businesses, but they can simultaneously boost the profits of energy companies.

Even the AI problem is complicated. A slowdown in AI investment could hurt some enormously valued technology companies, but it would not necessarily destroy the entire economy.

Indeed, markets have already shown that AI concerns can cause sector-specific selling without automatically triggering a broad collapse.

The real question, therefore, may not be why the market hasn’t fallen.

It is what would finally make investors collectively stop believing that the next problem can be absorbed?

Because markets rarely collapse simply because there are lots of problems.

They collapse when investors suddenly decide that those problems can no longer be ignored.

Stock market offers ‘easy money’?

It certainly sounds like easy money — if only markets worked that way. The danger is assuming that resilience means invincibility: a market can shrug off one problem, then another, and even several simultaneously, right up until investors collectively decide that earnings, valuations, interest rates or economic growth no longer justify the prices they are paying.

Until that moment arrives, bad news can simply be absorbed, explained away or declared temporary; when it does arrive, however, the same market that seemed capable of ignoring everything can suddenly discover that everything matters after all.

Difficulty


The difficult part is that there is no reliable way to say when it will happen — markets can remain expensive and resilient for considerably longer than economic logic might suggest.

The eventual correction is more likely to come when several pressures stop being viewed as temporary or manageable and begin to undermine the assumptions supporting corporate earnings and valuations: persistently high inflation, materially higher borrowing costs, weaker growth, falling profits, an AI investment slowdown, or an unexpected financial shock could each become the catalyst.

Until investors collectively change their expectations, the market can continue climbing despite an increasingly uncomfortable list of warning signs — but resilience should not be confused with immunity.
Fed Raises Rates – And Markets Now Face a New Question

U.S. inflation

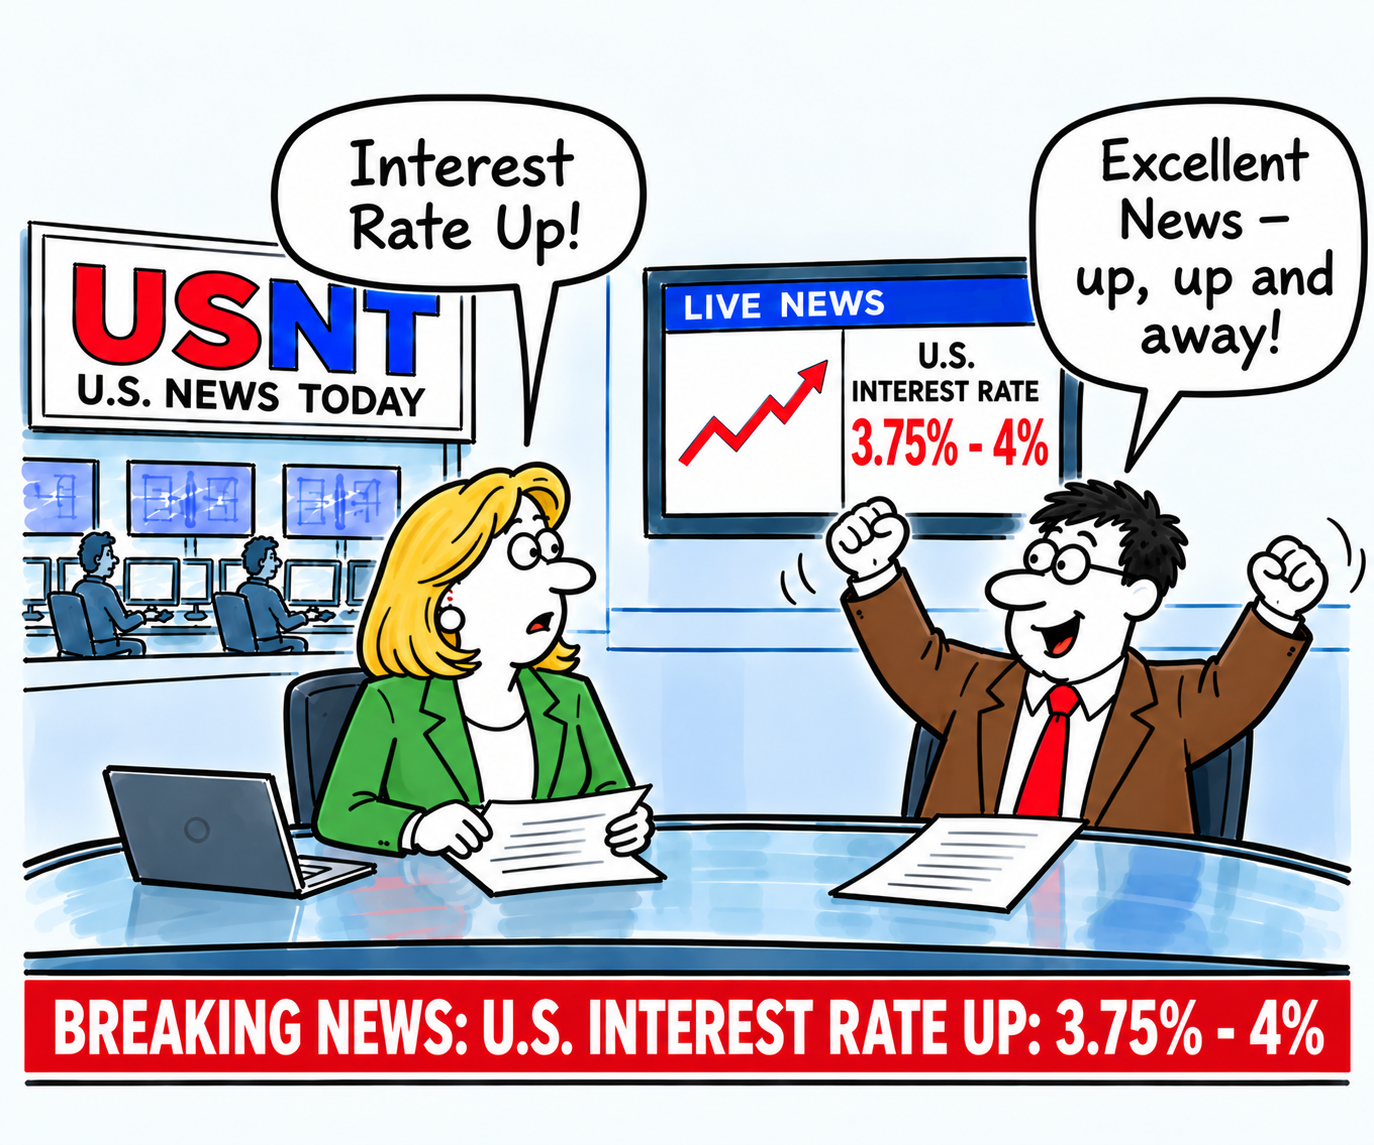
The Federal Reserve raised US interest rates by 25 basis points yesterday, taking its benchmark rate to 3.75%-4% and delivering the first increase since 2023.

The move puts U.S. inflation firmly back at the centre of the market conversation. Despite months of speculation about the direction of monetary policy, the Fed has signalled that persistent price pressures remain enough of a concern to warrant tighter financial conditions.

For investors, however, yesterday’s increase may be less important than what comes next

Markets must now decide whether the move represents a relatively modest adjustment to policy or the beginning of another tightening phase.

Any suggestion that further increases are coming could push U.S. Treasury yields and the dollar higher while placing renewed pressure on highly valued equities.

That matters particularly for a U.S. stock market already trading at elevated levels, with enthusiasm surrounding artificial intelligence continuing to support many of its largest companies.

Balancing act

The Fed therefore faces a difficult balancing act. It wants to bring U.S. inflation under control without unnecessarily damaging economic growth or employment.

For Wall Street, the question has changed.

It is no longer simply when will rates fall?

It is now how high might they have to go?

America’s $40 Trillion Debt Problem

The United States has crossed a remarkable financial milestone, with federal debt now standing at more than $40 trillion.

The figure is difficult to comprehend, but the bigger concern is the speed at which the debt burden is continuing to grow.

Debt increased $3 Trillion in one year

America’s debt has increased by roughly $3 trillion over the past year alone. The federal government is still running substantial annual deficits, meaning it is spending considerably more than it collects in tax revenue.

As a result, more borrowing is required simply to keep government finances operating.

The consequences are becoming increasingly visible in the bond market. Investors expect to be compensated for lending money to the U.S. government, and rising Treasury yields mean that borrowing is becoming more expensive.

The yield on the 30-year Treasury has recently climbed above 5%, placing further pressure on government finances.

Interest at $1.2 Trillion per year

Interest payments are becoming one of Washington’s largest financial burdens, approaching $1.2 trillion a year.

That money does not build infrastructure, fund new programmes or reduce the deficit. It is largely the cost of servicing debt accumulated over many years.

The Treasury has also increased its bond-buying operations in an effort to improve market liquidity, highlighting concerns about conditions in the government bond market.

While such measures can help stabilise trading, they do not address the underlying problem: America continues to borrow heavily.

How high can it go?

The $40 trillion milestone therefore represents more than a headline figure. It raises difficult questions about how long the current trajectory can continue and whether politicians will eventually have to confront spending, taxation and entitlement reform.

For years, America’s ability to borrow has been treated as almost unlimited. But the combination of enormous debt, persistent deficits, rising interest costs and higher bond yields is changing that calculation.

The world’s largest economy is not facing an immediate debt crisis, but $40 trillion is a warning that the cost of delaying difficult decisions is becoming increasingly expensive.

U.S. inflation up 0.1% in May – but less than expected

U.S. inflation

In May 2025, U.S. inflation rose by 0.1% from the previous month, bringing the annual inflation rate to 2.4%, slightly below economists’ predictions of 2.5%.

Core U.S. inflation, which excludes food and energy, increased by 0.1% month-on-month, with a year-on-year rate of 2.8%.

The modest rise was largely offset by falling energy prices, particularly a 2.6% drop in petrol, which helped keep overall inflation in check.

Prices for new and used vehicles, as well as apparel, also declined. Meanwhile, food and housing (shelter) costs each rose by 0.3%, with housing (shelter) being the primary contributor to the monthly increase.

Despite President Trump’s sweeping tariffs introduced in April 2025, their inflationary impact has yet to fully materialise. Analysts suggest that many companies are still working through pre-tariff inventories, delaying price hikes for consumers.

However, economists caution that the effects may become more pronounced in the coming months.

The Federal Reserve is expected to hold interest rates steady for now, as U.S. policymakers monitor whether inflation remains contained or begins to accelerate due to trade-related pressures.

Markets responded positively to the data, with stock futures rising and Treasury yields falling.

So, while inflation remains above the Fed’s 2% target, May’s figures suggest a temporary reprieve.

The summer could yet tell a different story.

Why are investors taking up positions in short term treasury bets?

Short-term Treasury Yields

Investors are increasingly favouring short-term U.S. Treasury securities, with notable figures like Warren Buffett taking sizeable positions.

This shift is driven by concerns over economic instability, fluctuating bond yields, and government spending.

Short-term Treasuries, such as T-bills with maturities under a year, offer a safer haven compared to longer-term bonds, which are more vulnerable to interest rate changes.

As central banks navigate monetary policy adjustments, many investors prefer the flexibility of short-duration assets that minimise exposure to prolonged economic uncertainty.

One of the biggest influences in this trend is Berkshire Hathaway’s substantial stake in T-bills, which has reinforced confidence in these instruments.

Additionally, ultra-short bond ETFs like SGOV and BIL have seen significant inflows, highlighting the growing demand for liquid, low-risk investments.

Another key factor driving this strategy is concern over U.S. fiscal policy. Investors are wary of rising deficits and potential tax hikes, which could impact long-term bond stability.

By allocating funds to short-term Treasuries, they can mitigate risks while maintaining liquidity.

This surge in short-term Treasury investments reflects a broader shift in market sentiment-favouring stability and flexibility over long-term speculation.

As economic uncertainty persists, investors are likely to continue this defensive strategy.

SGOV & BIL ETFs explained

SGOV and BIL are both exchange-traded funds (ETFs) that invest in U.S. Treasury bills, offering a low-risk way to earn interest on short-term government debt.

SGOV (iShares 0-3 Month Treasury Bond ETF) tracks the ICE 0-3 Month U.S. Treasury Securities Index, investing in Treasury bonds with maturities of three months or less. It launched in 2020 and is known for its low expense ratio.

BIL (SPDR Bloomberg 1-3 Month T-Bill ETF) follows the Bloomberg 1-3 Month U.S. Treasury Bill Index, focusing on Treasury bills with maturities between one and three months.

It has been around since 2007 and is one of the largest T-bill ETFs.

Both ETFs provide exposure to ultra-short-term government securities, making them attractive options for investors seeking stability and liquidity in uncertain markets.

What’s going on in the U.S. bond market?

Treasury yields

The U.S. bond market is experiencing some turbulence due to rising Treasury yields and concerns over government debt.

Investors are demanding higher yields because they’re worried about the GOP’s tax-cut plans, which could lead to increased borrowing and a larger deficit.

Additionally, the recent Trump tax bill has caused Treasury bond yields to surge, as investors anticipate more government debt issuance. Moody’s has also downgraded the U.S. credit rating, adding to market jitters.

The bond market’s reaction is significant because higher yields can lead to increased borrowing costs across the economy, affecting everything from mortgages to corporate financing.

Japan

Japan’s bond market is facing significant turbulence, with yields on 40-year government bonds hitting an all-time high. This surge in yields is causing concerns about capital repatriation, as Japanese investors may start pulling funds from the U.S. and other foreign markets.

The Bank of Japan’s reduced bond purchases have contributed to this trend, leading to weaker demand for long-term government debt. Analysts warn that if Japanese investors begin moving their capital back home, it could trigger a global financial market shake-up.

Additionally, Japan’s Finance Ministry is considering reducing the issuance of super-long bonds to stabilise the market. However, recent auctions have shown weak demand, raising concerns about the effectiveness of this strategy.

Europe

The European bond market is experiencing some shifts due to falling government bond yields and easing U.S. – EU trade tensions.

German 10-year bund yields dropped by 4 basis points, reflecting increased investor confidence.

UK and French 10-year bond yields also declined by 4 basis points, while Italian bonds saw a 2 basis point dip.

Long-term UK gilts experienced the biggest movement, with 20 and 30-year yields falling by 7 basis points.

This decline in yields suggests higher demand for European government debt, possibly due to investors shifting away from U.S. assets amid concerns over U.S. fiscal health.

UK

The UK bond market is facing some challenges, with the IMF warning that it is vulnerable to sudden shocks due to a growing reliance on hedge funds and foreign investors.

30-year gilt yields have hit 5.5%, the highest in over three decades.

The Bank of England’s quantitative tightening and increased bond issuance are putting pressure on the market.

The Debt Management Office (DMO) is shifting towards short-dated debt to reduce long-term interest costs.

Additionally, the UK government has launched a new 30-year gilt offering 5.375% interest, which is attracting investor attention.

Federal Reserve’s preferred recession indicator is flashing red again!

U.S. inverted yield curve

The Federal Reserve’s favourite recession indicator, the inverted yield curve, is flashing a danger sign once again.

This occurs when the U.S. yield on the 10-year Treasury note falls below that of the 3-month note. Historically, this has been a reliable predictor of economic downturns, with a strong track record over a 12-18-month timeframe.

The New York Fed closely monitors this indicator and provides monthly updates on the probability of a recession occurring within the next 12 months.

As of January 2025, the probability was just 23%, but this is expected to change significantly due to the recent inversion in the coming months.

The inversion suggests that investors are becoming more risk-averse and are anticipating a slowdown in economic activity.

While the yield curve inversion has a strong forecasting history, it is not perfect, and there is no certainty that growth will turn negative this time around

Has ‘Rachel from accounts’ messed up the UK economy?

UK budget

The pound has continued to fall after UK government borrowing costs rose and concerns grew about public finances

Sterling dropped as UK 10-year borrowing costs surged to their highest level since the 2008 financial crisis when bank borrowing virtually ground to a halt.

Economists have warned the rising costs could lead to further tax rises or cuts to spending plans as the government tries to meet its self-imposed borrowing target.

The UK government creates its own financial crisis as it messes up its ‘go for growth’ policy

The UK economy is currently grappling with a series of financial challenges that have led to a significant fall in the value of the pound, soaring treasury yields, and high borrowing costs.

These developments have been largely influenced by the recent budget announced by Chancellor Rachel Reeves, which has sparked concerns among investors and economists alike.

Downward trajectory

The pound has been on a downward trajectory, recently hitting its lowest level since November 2023. Traders are betting on further declines, with some predicting the pound could fall as low as $1.12

This decline is partly due to the rising cost of government borrowing, which has surged to levels not seen since the 2008 financial crisis. The yield on 10-year gilts has climbed to 4.8%, while the yield on 30-year gilts has reached 5.34%, the highest in 27 years.

Recent UK budget

The recent budget has played a crucial role in these developments. Announced in October 2024, the budget included significant tax hikes and increased spending, leading to a substantial rise in government borrowing.

The budget deficit is expected to reach 4.5% of GDP this fiscal year, pushing the overall government debt close to 100% of GDP. This increase in borrowing has led to a higher supply of government debt, which in turn has driven down the price of bonds and pushed up yields.

Higher yields

Higher yields mean that the government has to pay more to borrow money, which has significant implications for its fiscal policy. The rising cost of servicing government debt could force the government to either raise taxes further or cut spending to meet its fiscal rules.

This situation is reminiscent of the market turmoil following Liz Truss’s mini budget in 2022, which also led to a sharp rise in borrowing costs and a fall in the value of the pound.

The impact of these developments extends beyond the government. Higher borrowing costs are likely to affect households and businesses as well.

Economic growth at risk

Mortgage rates, which are influenced by government bond yields, are expected to remain high, putting additional pressure on homeowners. Businesses, on the other hand, may face higher costs of borrowing, which could lead to reduced investment and slower economic growth.

The UK is facing a challenging economic environment characterized by a falling pound, high treasury yields, and rising borrowing costs.

The recent budget has exacerbated these issues, leading to increased government borrowing and higher debt levels. As the government navigates these challenges, it will need to carefully balance its fiscal policies to avoid further economic instability and ensure sustainable growth and not more ‘unfunded’ debt.

10-year Treasury yield at 4.25% – highest since July 2024

Treasury yields U.S.

On Wednesday 23rd October 2024, the U.S. 10-year Treasury yield climbed again as traders considered recent remarks from Federal Reserve officials regarding the direction of interest rate reductions

The U.S. 10-year Treasury yield increased by over 0.030% to approximately 4.24%. The benchmark rate peaked at 4.26% during the session, its highest since July 2024. This surge followed a 12-basis point leap on Monday 21st and a rise above 4.2% on Tuesday 22nd.

The U.S. 2-year Treasury yield also rose, reaching 4.06%, up by roughly 0.030%. Earlier in the day, it achieved a high of 4.072%.

Yields and equity prices have an inverse relationship. A single basis point is equivalent to 0.01%

Elevated Treasury yields are exerting pressure on the equity market, causing U.S. stock futures to drop. This downturn follows the S&P 500‘s first consecutive loss since the beginning of September.

Despite a half-point reduction by the Federal Reserve in September 2024, strong economic indicators and concerns about the deficit have contributed to the increase in the 10-year Treasury yield.

Traders are worried that the central bank might be reluctant to lower rates further, even though the Fed predicted additional cuts amounting to half a point by the end of the year.

The jury is out.

U.S. stocks recovery attempt fizzles out

Fizzle

Stocks closed lower on Wednesday 7th August 2024, failing to fully recover from Monday’s sell-off.

The Dow Jones Industrial Average dropped 234 points to 38763.45. The S&P 500 fell to 5199.50, while the Nasdaq Composite closed at 16195.81.

During the day, the Dow had surged around 480 points, the S&P 500 had climbed 1.73%, and the Nasdaq had risen over 2%.

Dow Jones one day chart 7th August 2024

Dow Jones one day chart 7th August 2024

S&P 500 one day chart 7th August 2024

S&P 500 one day chart 7th August 2024

Nasdaq Composite one day chart 7th August 2024

Nasdaq Composite one day chart 7th August 2024

However, a downturn in Nvidia and other major tech stocks, after an initial rise, led to a significant drop in the afternoon. Nvidia retracted by 5.1%, Super Micro Computer plummeted 20.1% following its fiscal Q4 earnings missing analyst predictions, Tesla fell 4.4%, and Meta Platforms decreased by 1%.

Nvidia one day chart 7th August 2024

Nvidia one day chart 7th August 2024

One month chart Super Micro Computer 7th August 2024

One month chart Super Micro Computer 7th August 2024

Nvidia one day chart 7th August 2024

Nvidia one day chart 7th August 2024

The U.S.10-year Treasury yield continued to rise, increasing by about six basis points to 3.95%, returning to its level before the disappointing job figures last Friday, which had sparked concerns of an economic slowdown.

The Volatility Index (CBOE), the so called ‘fear gauge‘ was trading at around 29, having dropped to as low as 22 earlier in the day. This sharp decrease from Monday 5th August 2024 suggests that investor fears are subsiding, however, they remain higher than at the beginning of the month.

The Volatility Index (CBOE) on 7th August 2024

The Volatility Index (CBOE) on 7th August 2024

Early Christmas present as the U.S. 10-year Treasury yield pullback after Fed’s ‘shift’

Christmas gift

The 10-year Treasury yield slipped further on Monday 18th December 2023, as the final full trading week of 2023 gets underway.

Traders are attempting to digest the ‘dovish’ tone of the U.S. Federal Reserve. The central bank held its key interest rate at 5.5% and revealed that policymakers were pencilling in at least three rate cuts in 2024 marking a more aggressive series of cuts than what was previously expected.

The yield on the 10-year Treasury was marginally lower at 3.913%. Last Thursday, the yield fell below the 4% level, hitting its lowest since July this year.

Bank strategists described the Fed’s move as a ‘big shift’

Guessing game starts

The question now is when will these rate cuts happen, and on Friday we had some mild pushback from Fed officials against the market excitement.

Latest U.S. job data indicates that job growth accelerated by 199,000

Work

The latest U.S. job data indicates that job growth accelerated in November 2023, with seasonally adjusted non-farm payrolls increasing by 199,000. 

The unemployment rate has dropped to 3.7%, even as more workers entered the labour market. This points to underlying strength in the labour market and is a positive sign for the U.S. economy. 

U.S. job creation chart January 2022 – November 2023

U.S. job creation chart January 2022 – November 2023

Stocks had risen as investors awaited these latest employment figures, which are closely watched as an indicator of potential moves by the central bank on interest rates.

Mixed reaction

Markets showed a mixed reaction to the report, with stock market futures modestly negative while Treasury yields surged. Job creation showed little signs of slowing as payrolls grew even faster than expected and the unemployment rate fell despite signs of a weakening economy.

Good news for the U.S. economy but Treasury yields are on the up again.

Nasdaq stumbles, descending further into correction

Nasdaq

The Nasdaq is a stock market index that tracks the performance of over 3,000 companies, mostly in the technology sector.

Correction

A correction is a term used to describe a decline of 10% or more from a recent peak in the price of an asset. The Nasdaq entered correction territory on Wednesday 25th October 2023, as it closed at 12,922, which was 10% lower than its previous high of 14,358 on 19th July 2023.

The main reason for the Nasdaq’s correction is believed to be the rise in long-term Treasury yields, which increased the borrowing costs for companies and reduced the attractiveness of growth stocks. The 10-year Treasury yield rose to 4.95% on Wednesday 25th October 2023, the highest level since June 2021. Higher interest rates also make future earnings for tech companies much more difficult.

Disappointing Q3 results

Another factor that contributed to the Nasdaq’s correction was the disappointing third-quarter earnings reports from some of the biggest tech companies, such as Alphabet (Google), Amazon, and Meta (Facebook fame). 

These companies reported lower-than-expected revenue growth, profit margins, and cloud computing performance, which weighed on their stock prices and dragged down the Nasdaq. Investors expect more, especially with AI – now the new kid-on-the-block.

Concerns

The Nasdaq’s correction has raised concerns among investors about the outlook for the tech sector and the broader stock market. However, some analysts have argued that the correction could be a healthy and temporary adjustment that creates buying opportunities for long-term investors. 

They have pointed out that the Nasdaq is still up 22.5% year-to-date as of Wednesday 25th October 2023, and that the fundamentals of the tech industry remain strong despite the challenges posed by inflation, regulation, yields and competition.

U.S. ten-year treasury yield breaches 5% for the first time since 2007

Treasury yield

The U.S. Treasury yields are the interest rates that the U.S. government pays to borrow money for different periods of time.

The 10-year Treasury yield is one of the most important indicators of the state of the economy and the expectations of inflation and growth. On 23rd October 2023, the 10-year Treasury yield rose above 5% for the first time since 2007, as investors increasingly accepted that interest rates will stay higher for longer and that the U.S. government will further increase its borrowing to cover its deficits.

Significant

This is a significant milestone, as it reflects the market’s view that the Federal Reserve will maintain elevated interest rates to control inflation and that the U.S. economy will remain resilient despite the challenges posed by the Covid-19 pandemic, geopolitical tensions and environmental issues.

The higher yield also means that the government will have to pay more to service its debt, which could affect its fiscal policy and spending priorities. The higher yield also affects other borrowing costs, such as mortgages, student loans, and corporate bonds, which could have implications for consumers and businesses.

10 Year Yield

The 10-year Treasury yield is influenced by many factors, such as supply and demand, inflation expectations, economic growth, monetary policy, and global events. The yield has been rising steadily since it hit a record low of 0.5% in March 2020, when the pandemic triggered a flight to safety and a massive stimulus from the Fed. Since then, the yield has been driven by the recovery of the economy, the surge in inflation, the reversal of the Fed’s bond-buying program, and the increase in the government’s borrowing needs.

Yield curve

The ten-year yield is closely watched by investors, analysts and policymakers as it provides a benchmark for valuing other assets and assessing the outlook for the economy. The yield is also used to calculate the yield curve, which is the difference between short-term and long-term Treasury yields.

The shape of the yield curve can indicate the market’s expectations of future interest rates and economic activity.

Artwork impression of computer screen: U.S. ten-year treasury yield breaches 5% for the first time since 2007

A steep yield curve means that long-term yields are much higher than short-term yields, which suggests that investors expect higher inflation and growth in the future. A flat or inverted yield curve means that long-term yields are lower than or equal to short-term yields, which implies that investors expect lower inflation and growth or even a recession.

The current yield curve is steepening, as long-term yields are rising faster than short-term yields. This indicates that investors are anticipating higher inflation and growth in the long run, but also that they are concerned about the sustainability of the government’s fiscal position and the impact of higher interest rates on the economy.

Indicators

The 10-year Treasury yield is an important indicator of the state of the economy and the expectations of inflation and growth. It has reached a level that has not been seen since before the global financial crisis of 2008-2009. This reflects the market’s view that interest rates will stay higher for longer and that the government will increase its borrowing to cover its deficits. The higher yield also affects other borrowing costs and asset prices, which could have implications for consumers and businesses.

The yield is influenced by many factors and is closely watched by investors, policymakers, and analysts. A 5% yield is a worry for the market, inflation, interest rates, geo-political risks and recession are the others, that’s enough!