Bitcoin’s Bear Market and Its Impact on Crypto in General

Bitcoin in a bear market

Bitcoin has officially entered a bear market, having fallen more than 25% from its October peak of $126,000.

This downturn is rippling across the wider crypto sector, dragging Ethereum, Solana, and other altcoins into steep declines as investor sentiment turns risk-off.

Bitcoin’s recent plunge below $95,000 marks a decisive shift into bear market territory. After reaching an all-time high of $126,000 in early October, the cryptocurrency has shed over a quarter of its value in just six weeks.

Analysts point to a combination of factors: fading hopes of Federal Reserve rate cuts, heavy outflows from Bitcoin ETFs, and broader weakness in technology. The sell-off has erased all of Bitcoin’s 2025 gains, leaving traders cautious and fearful.

This downturn is not isolated. Ethereum has dropped more than 30% from its highs, while Solana and Cardano have suffered double-digit losses.

The total crypto market capitalisation has fallen by approximately $1 trillion since October, underscoring how tightly correlated altcoins remain to Bitcoin’s trajectory.

When the flagship asset falters, liquidity drains across the sector, amplifying volatility.

Investor psychology has shifted dramatically. The ‘buy the dip’ mentality that defined earlier rallies is giving way to defensive strategies, with many now selling into strength rather than accumulating.

Long-term holders have reportedly offloaded hundreds of thousands of BTC in recent weeks, intensifying downward momentum. Meanwhile, ETF outflows — exceeding $1.6 billion in just three days — highlight waning institutional confidence.
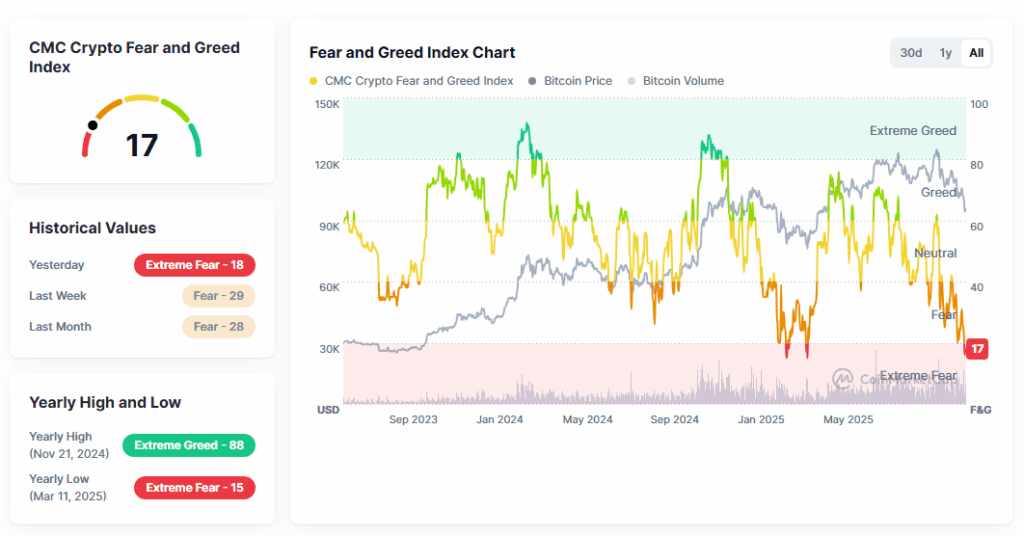
Snapshot of CoinMarketCap Fear Gauge

For the broader crypto ecosystem, Bitcoin’s bear market signals a period of consolidation and caution. Altcoins, often more volatile, are likely to experience sharper swings.

Yet history suggests that such downturns can reset valuations, paving the way for healthier growth once macroeconomic conditions stabilise.

For now, however, the market remains firmly in risk-off mode, with Bitcoin leading the retreat.

The crypto sector faces nearing a $1 trillion wipeout, with investor sentiment shifting from optimism to fear.
Even AI Firms Voice Concern Over Bubble Fears

AI bubble

For some time now, talk of an ‘AI bubble‘ has largely come from investors and financial analysts. Now, strikingly, some of the loudest warnings are coming from inside the industry itself.

At the Web Summit in Lisbon, senior executives from companies such as DeepL and Picsart reportedly admitted they were uneasy about the soaring valuations attached to artificial intelligence ventures. Sam Altman of OpenAI has also sounded warnings of AI overvaluation.

DeepL’s chief executive Jarek Kutylowski reportedly described current market conditions as ‘pretty exaggerated’ and suggested that signs of a bubble are already visible.

Picsart’s Hovhannes Avoyan reportedly echoed the sentiment, criticising the way start‑ups are being valued despite having little or no revenue. He reportedly coined the phrase ‘vibe revenue’ to describe firms being backed on hype rather than substance.

These remarks highlight a paradox. On one hand, demand for AI services remains strong, with enterprises expected to increase adoption in 2026.

On the other, the financial side of the sector looks overheated. Investors such as Michael Burry have accused major cloud providers of overstating profits, while banks including Goldman Sachs and Morgan Stanley have warned of potential corrections.

The tension reflects a broader question: can the industry sustain its rapid expansion without a painful reset?

Venture capital forecasts suggest trillions will be poured into AI data centres over the next five years, yet some insiders argue that the scale of spending is unnecessary.

Even optimists concede that businesses are struggling to integrate AI effectively, meaning the promised returns may take longer to materialise.

For now, the AI sector stands at a crossroads. The technology’s transformative potential is undeniable, but the financial exuberance surrounding it may prove unsustainable.

If the warnings from within the industry are correct, the next chapter of the AI story could be less about innovation and more about value correction.

Private equity is increasingly burdened by ‘zombie companies’

Zombie Companies

Private equity is increasingly burdened by ‘zombie companies‘ – firms that neither grow nor collapse, but linger in portfolios, draining resources and blocking exits.

In recent years, private equity has faced a troubling phenomenon: the rise of the zombie company.

These are businesses that generate just enough cash to service their debt but fail to deliver meaningful growth or attract buyers, even at discounted valuations.

They remain trapped on balance sheets long after the intended investment horizon, creating a drag on both investors and the wider economy.

The roots of this problem lie in shifting market conditions. Rising interest rates have made debt-heavy buyouts harder to sustain, while a slowdown in dealmaking has reduced opportunities for profitable exits.

Offloading?

In the past, firms could rely on buoyant markets to offload underperforming assets, but today’s cautious buyers are unwilling to take on companies with weak fundamentals.

As noted by a financial educationalist, Oliver GOTTSCHALG – ‘the machine is stuck’ – private equity firms cannot recycle capital efficiently.

For investors, the implications are stark. Capital is locked in funds that cannot distribute returns, potentially undermining confidence in the asset class.

Some firms have resorted to continuation vehicles or fee-generating strategies to keep operations afloat, but these are stopgaps rather than solutions.

The longer companies remain in this half-alive state, the more they consume scarce managerial attention and financial resources.

The persistence of zombie companies also raises broader concerns. They tie up capital that could otherwise support innovation and growth, while their stagnation risks eroding trust in private equity’s promise of dynamic value creation.

Unless market conditions improve or restructuring strategies succeed, the industry may face a decade defined not by bold exits, but by portfolios haunted by the undead.

In short, zombie companies symbolise private equity’s struggle to adapt, neither thriving nor dying but stubbornly refusing to leave

Zombie companies in private equity trap capital, reducing liquidity and investor confidence, which indirectly pressures public markets—especially high‑valuation sectors like AI.

When private equity funds are clogged with underperforming assets, institutional investors face tighter cash flows and may rebalance away from riskier equities.

This creates capital shortages and amplifies volatility in growth stocks. AI firms, already under scrutiny for sky‑high valuations, are particularly vulnerable: investors pull back when liquidity is constrained, leading to sharper corrections.

Recent sell‑offs saw AI stocks lose over $820 billion in value as confidence faltered, reflecting how private equity stagnation can ripple into tech markets.

Beware the Zombie!

Dow hits fresh all-time high!

Dow hits new high!

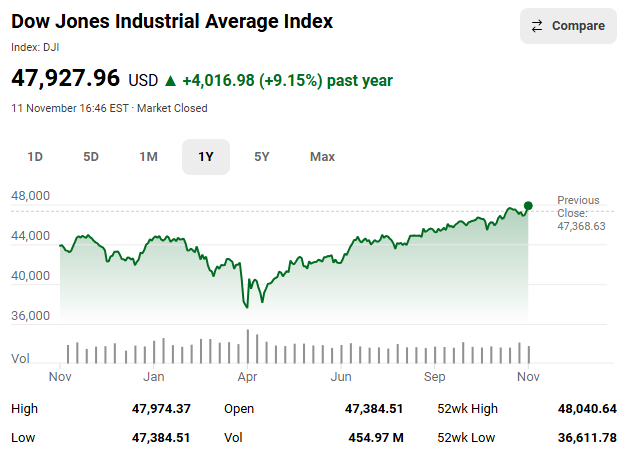
On 11th November 2025, the Dow Jones Industrial Average closed at a record high of 47,927.96, underscoring investor confidence despite broader market volatility.

The index briefly touched an intraday peak of 48,040 before settling lower, marking its strongest official finish to date.

Analysts attributed the surge to optimism around fiscal negotiations in Washington and renewed appetite for industrial and financial stocks, as investors rotated away from technology shares, albeit a temporary rotation.

Dow Jones one-year chart showing new high as of 11th November 2025

The milestone reflects resilience in traditional sectors, even as global uncertainties persist.

For many, the Dow’s achievement symbolises a paradox of optimism amid caution, setting the stage for year‑end market narratives.

SoftBank exits Nvidia with $5.83 billion stake sale to fund AI ambitions

Softbank sells Nvidia stock

SoftBank Group has reportedly sold its entire holding of Nvidia shares, cashing in approximately $5.83 billion to fuel its expanding investments in artificial intelligence

The Japanese tech conglomerate offloaded 32.1 million shares in October 2025, marking a strategic pivot away from the chipmaker that once anchored its Vision Fund portfolio.

The sale coincided with SoftBank’s announcement of a ¥2.5 trillion net profit for the July–September 2025 quarter, buoyed by gains from both Nvidia and a partial divestment of its T-Mobile stake.

AI ventures

Founder, Masayoshi Son is now redirecting capital towards ambitious AI ventures, including the Stargate data centre project and robotics manufacturing in the U.S.

While SoftBank remains entangled with Nvidia’s ecosystem through its AI-linked ventures, this exit signals a broader monetisation strategy amid growing scrutiny over tech sector valuations.

The move underscores Son’s intent to reshape SoftBank as a dominant force in next-generation AI infrastructure.

Tesla’s China Sales Plunge to Three-Year Low Amid Fierce Competition

Tesla sales fall in China

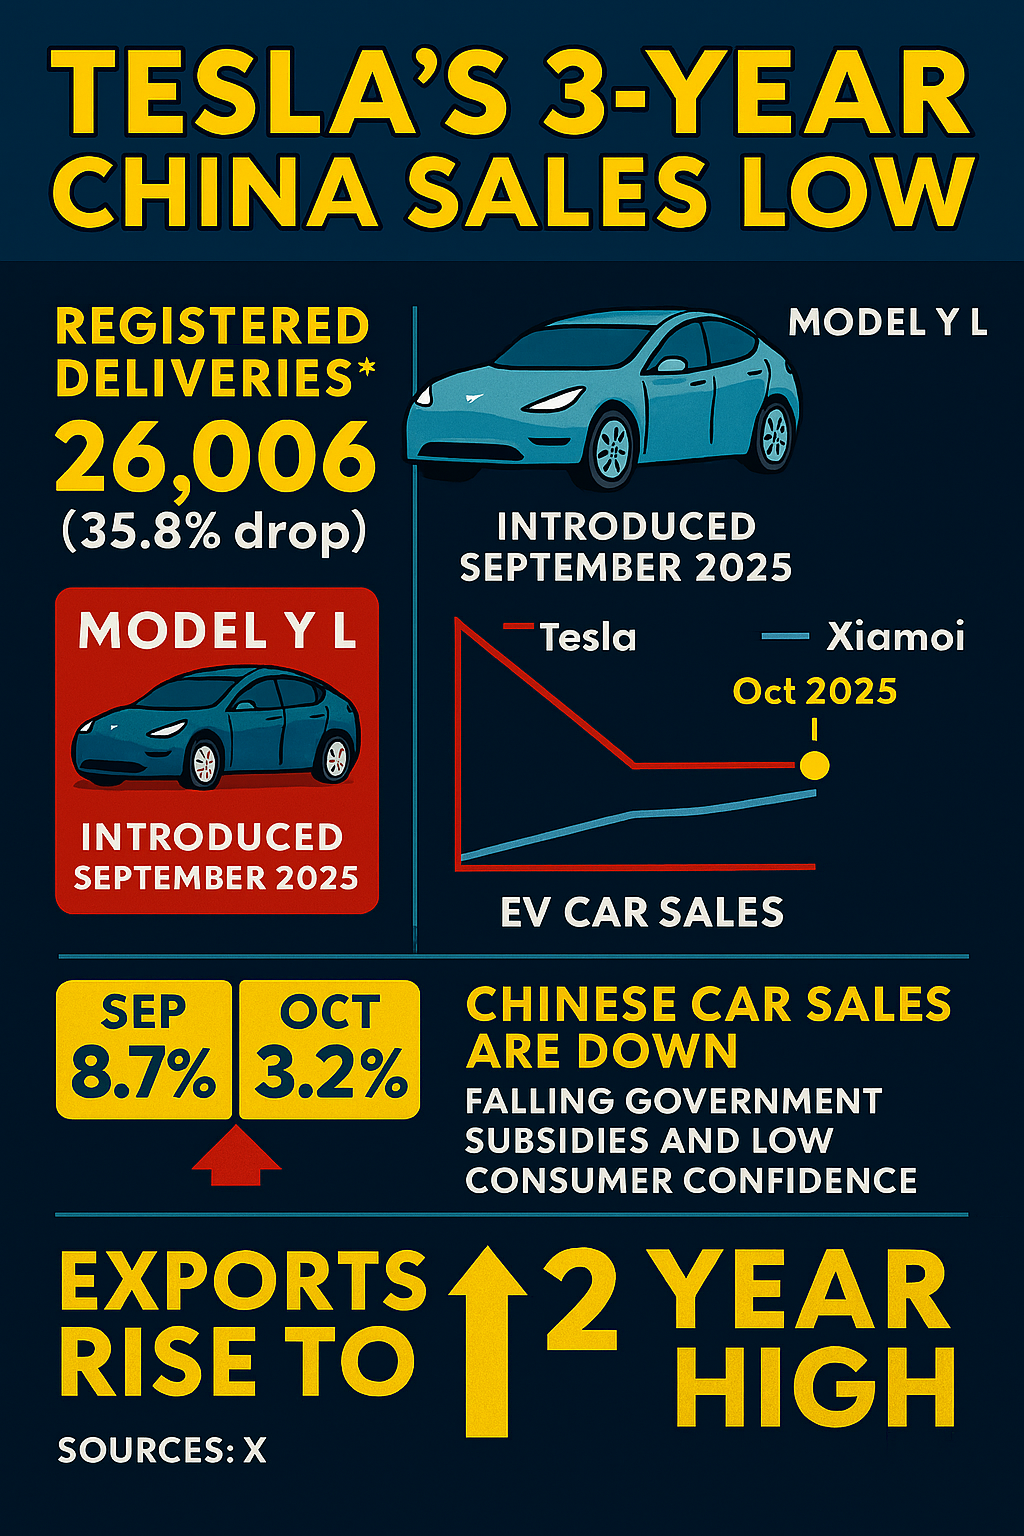
Tesla has hit a troubling milestone in China, with October 2025 marking its lowest monthly sales in three years.

The American electric vehicle giant sold just 26,006 units, a staggering 35.8% (approx’) drop compared to the same month last year.
This slump follows a brief surge in September 2025, when Tesla launched the Model Y L—a longer-wheelbase, six-seat version tailored for Chinese consumers.

Despite initial enthusiasm, the momentum quickly faded as domestic rivals ramped up their offerings. Xiaomi, for instance, recorded 48,654 EV sales in October 2025, outpacing Tesla and highlighting the growing strength of local brands.

Tesla’s market share in China’s EV sector shrank to around 3.2%, down from 8.7% the previous month, underscoring the brand’s struggle to maintain relevance in the world’s most competitive electric vehicle market.

Broader economic factors also played a role, with overall car sales in China declining amid reduced government subsidies and waning consumer confidence.

While Tesla’s exports from China rose to a two-year high, the domestic downturn signals a strategic challenge.

As local manufacturers innovate rapidly and offer aggressive pricing, Tesla will likely rethink its approach to regain traction in a market that once promised boundless growth.

Tesla’s $1 Trillion Bet on Elon Musk

$1 trillion Elon pay deal

In a move that has stunned financial analysts, corporate governance experts, and the broader public alike, Tesla Inc. has approved a record-breaking $1 trillion (£761 billion) compensation package for its CEO, Elon Musk.

In a landmark decision, Tesla shareholders have approved a staggering $1 trillion (£761 billion) compensation package for CEO Elon Musk, marking the largest executive pay deal in corporate history.

The vote, held at Tesla’s annual meeting in Austin, Texas, reportedly saw over 75% of investors back the plan, reaffirming their confidence in Musk’s leadership and long-term vision.

Share deal

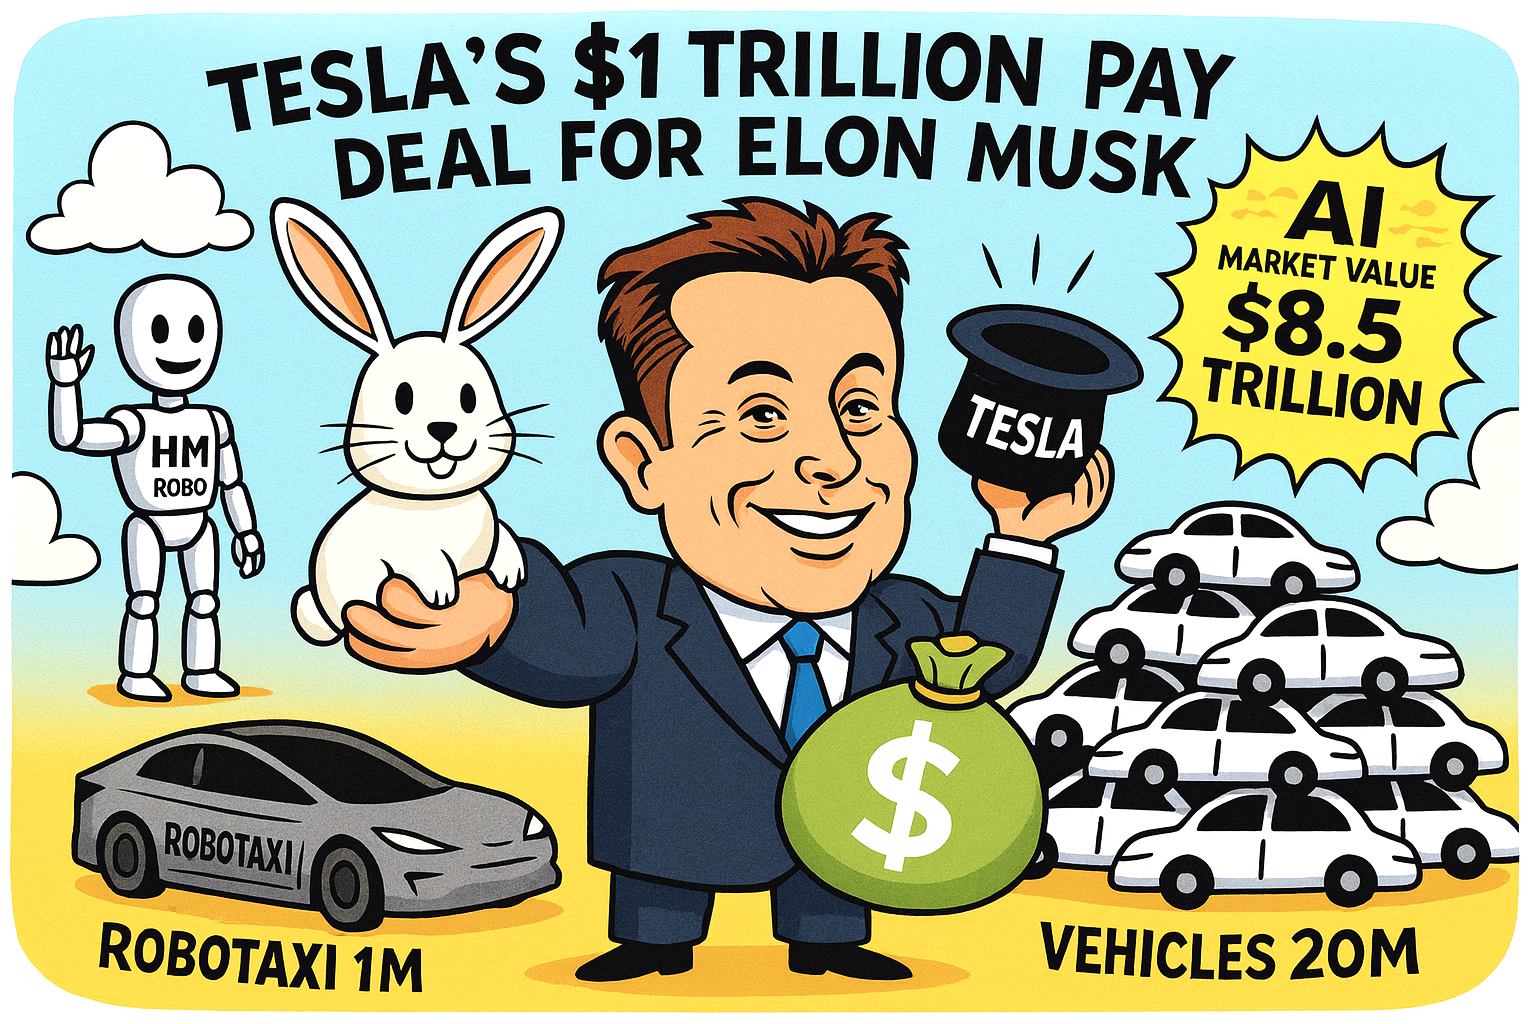
The deal is entirely performance-based, with Musk eligible to receive up to 423 million Tesla shares if the company meets a series of ambitious milestones.

These include producing 20 million vehicles annually, deploying one million robotaxis and humanoid robots, and reaching a market valuation of $8.5 trillion.

Reportedly there is no salary or cash bonus—Musk’s payout depends solely on Tesla’s success.

Supporters argue the package aligns Musk’s incentives with shareholder interests, encouraging innovation and growth.

Critics, however, warn of governance risks and the unprecedented concentration of wealth and power.

Musk, already the world’s richest person, could become the first trillionaire if Tesla achieves its targets.

The vote signals Tesla’s intent to evolve beyond electric vehicles into a broader tech powerhouse, betting on AI, robotics, and autonomy—with Musk at the helm.

AI hype collides with economic reality, and signs suggest the mania may be slowing

AI momentum slowing

Artificial Intelligence: The Hype, The Hangover, and What Comes Next…

For the past two years, artificial intelligence has dominated headlines, boardrooms, and investor portfolios.

From generative models that write poetry to chips that promise to revolutionise data processing, AI has been hailed as the engine of a new industrial age. But as 2025 unfolds, the sheen is beginning to dull.

Beneath the surface of record-breaking valuations and breathless media coverage, a more sobering narrative is taking shape: the AI boom may be running out of steam.

Slowing down

Recent market activity paints a cautionary tale. Despite strong earnings from AI stalwarts like Palantir and AMD, stock prices have faltered a little.

Palantir plunged nearly 8% after a blowout quarter, and even Nvidia—long considered the crown jewel of AI hardware—has seen pullbacks.

Analysts warn that Wall Street’s tunnel vision on AI is creating distortions, with capital flooding into a narrow set of companies while broader market fundamentals weaken.

One major concern is overcapacity in data centres. Billions have been poured into infrastructure to support AI workloads, but growth in consumer-facing applications—particularly chatbots and virtual assistants—appears to be plateauing.

Businesses are also grappling with the reality that integrating AI into operations is far more complex than anticipated. From regulatory hurdles to ethical dilemmas, the promise of seamless automation is proving elusive.

Bubble?

The spectre of an ‘AI bubble‘ looms large. Comparisons to the dot-com crash are no longer whispered—they’re openly debated by investors and tech executives alike.

While AI is undoubtedly transformative, the pace of investment may be outstripping the technology’s current utility. As OpenAI’s CEO Sam Altman noted, ‘When bubbles happen, smart people get overexcited about a kernel of truth’.

That kernel remains potent. AI will continue to reshape industries, but the narrative is shifting from euphoric disruption to measured integration. The mania is not over—but it’s maturing.

Investors, developers, and policymakers must now navigate a more nuanced landscape, where realism replaces hype, and long-term value trumps short-term spectacle.

In short, the AI revolution isn’t collapsing—it’s sobering up. And that may be the best thing for its future.

AI optimism fuels October’s stock surge, with tech leading the charge

AI driven stock market

October 2025 saw a notable upswing in global equity markets, with artificial intelligence (AI) emerging as a key driver of investor enthusiasm.

In the United States, major indices closed the month firmly in the green, buoyed by strong third-quarter earnings and renewed confidence in AI’s transformative potential.

Tech giants such as Nvidia, Amazon, and Palantir posted robust results, reinforcing the narrative that AI is not just hype—it’s reshaping business fundamentals.

Nvidia’s leadership in AI chips and Amazon’s expanding AI-driven logistics were particularly well received, while Palantir’s government contracts underscored AI’s strategic reach.

The Federal Reserve’s decision to cut interest rates by 0.25% added further momentum, making growth stocks more attractive and amplifying the rally in AI-heavy portfolios.

Analysts noted that investor sentiment was bolstered by easing trade tensions and a cooling inflation outlook, but it was AI’s ‘secular tailwind of extreme innovation’ that truly captured market imagination.

While some caution that valuations may be running hot, the October 2025 rally suggests that AI is now central to market dynamics. A pullback is likely soon.

As 2025 draws to a close, investors are watching closely to see whether the optimism translates into durable gains—or signals the start of an AI bubble.

Cathie Wood Warns of AI Market Top-Heavy Risks Amid Strategic Portfolio Shifts

AI stock warning

Cathie Wood, CEO of ARK Invest, has once again stirred debate in financial circles by cautioning that the artificial intelligence (AI) sector may be growing top-heavy.

While she remains bullish on the long-term potential of AI technologies, Wood has signalled concern over the concentration of capital in a handful of dominant players—particularly those driving the S&P 500’s recent surge.

Speaking during a recent investor forum in Saudi Arabia, Wood dismissed fears of an outright AI bubble but acknowledged the risk of valuation corrections as interest rates climb and market exuberance outpaces fundamentals.

Her remarks come as ARK Invest continues to rebalance its portfolio, trimming exposure to overvalued tech giants while increasing stakes in emerging AI innovators such as Baidu and Robinhood.

Wood’s flagship ARK Innovation ETF (ARKK) has rebounded sharply in 2025, up over 87% year-on-year, largely fuelled by AI-related holdings.

Yet she reportedly remains wary of the ‘Mag 7’ effect—where a small cluster of mega-cap stocks like Nvidia, Microsoft, and Alphabet dominate investor attention and index weightings.

Strategy

This concentration, she argues, distorts broader market signals and risks sidelining promising mid-cap disruptors.

In response, ARK has shed positions in AMD and Shopify while doubling down on Baidu, a move that reflects Wood’s belief in underappreciated AI plays beyond Silicon Valley.

Her strategy underscores a broader thesis: that the next wave of AI growth will come from decentralised platforms, edge computing, and global innovators—not just the usual suspects.

While critics remain divided on her timing and tactics, Wood’s portfolio adjustments suggest a nuanced approach—one that embraces AI’s transformative power while resisting the gravitational pull of overhyped valuations.

For investors watching the sector’s evolution, her message is clear: beware the weight of giants.

Nvidia has become the first company in history to surpass a $5 trillion market valuation, marking a seismic shift in global tech leadership

Nvidia at $5 trillion Valuation

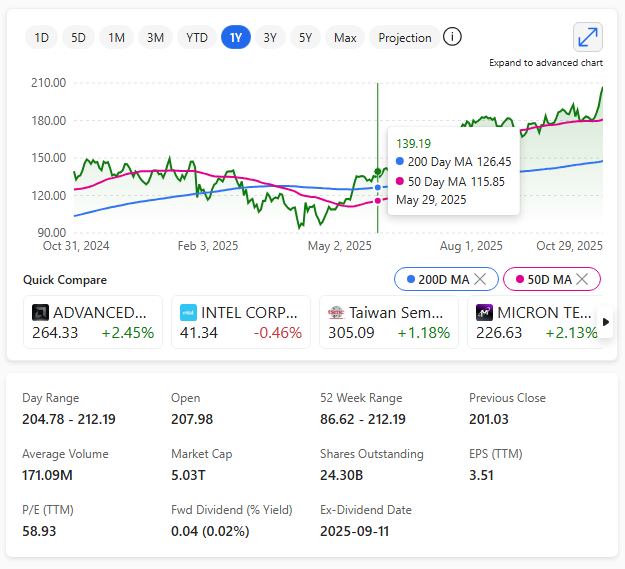
In October 2025, Nvidia’s stock surged past $207 per share, lifting its market capitalisation to $5.06 trillion. Once a niche graphics chip maker, Nvidia now powers the backbone of artificial intelligence worldwide.

CEO Jensen Huang confirmed over $500 billion in chip orders and plans for seven U.S. supercomputers.

This milestone, reached just three months after crossing $4 trillion, places Nvidia ahead of Microsoft and Apple, cementing its dominance in the AI era and redefining the future of computing.

Nvidia one-year chart as of October 2025

Nvidia one-year chart as of October 2025 passes $5 trillion Market Cap

Gold goes cold – but it’s not a melt-down

Gold pulls back

Gold has entered a correction phase as of late October 2025, following a record-breaking rally earlier this year.
The Correction in Context

  • Gold surged over 55% in 2025, reaching an all-time high of nearly $4,400 per ounce before sharply reversing course.
  • On 21st October 2025, gold experienced its steepest intraday drop in 12 years, falling over 6% in a single day.
  • This pullback followed nine consecutive weeks of gains, marking a classic technical correction after an overheated rally.

What’s Driving the Pullback?

  • Profit-taking: Many institutional investors began locking in gains after the massive run-up.
  • Stronger U.S. dollar: A rising dollar has historically pressured gold prices lower.
  • Easing geopolitical tensions: Particularly between the U.S. and China, which reduced safe-haven demand.
  • Technical overbought signals: Analysts flagged a ‘blow-off top’ pattern, similar to 2006, suggesting a short-term peak.

What’s Next?

Some analysts believe this is a healthy reset, not the end of the gold bull run.

Others warn of a further $300–$400 downside risk, especially if profit-taking accelerates.

Despite the correction, long-term fundamentals—like inflation concerns and geopolitical uncertainty—remain supportive of gold.

Gold is still up, and its safe haven status is still very much intact.

Stock market roundup of latest all-time highs! October 2025

Stocks hit all-time high

Scaling the Summit: Markets Hit Record Highs Amid Global Uncertainty led by the Nasdaq and S&P 500 reflecting the AI race

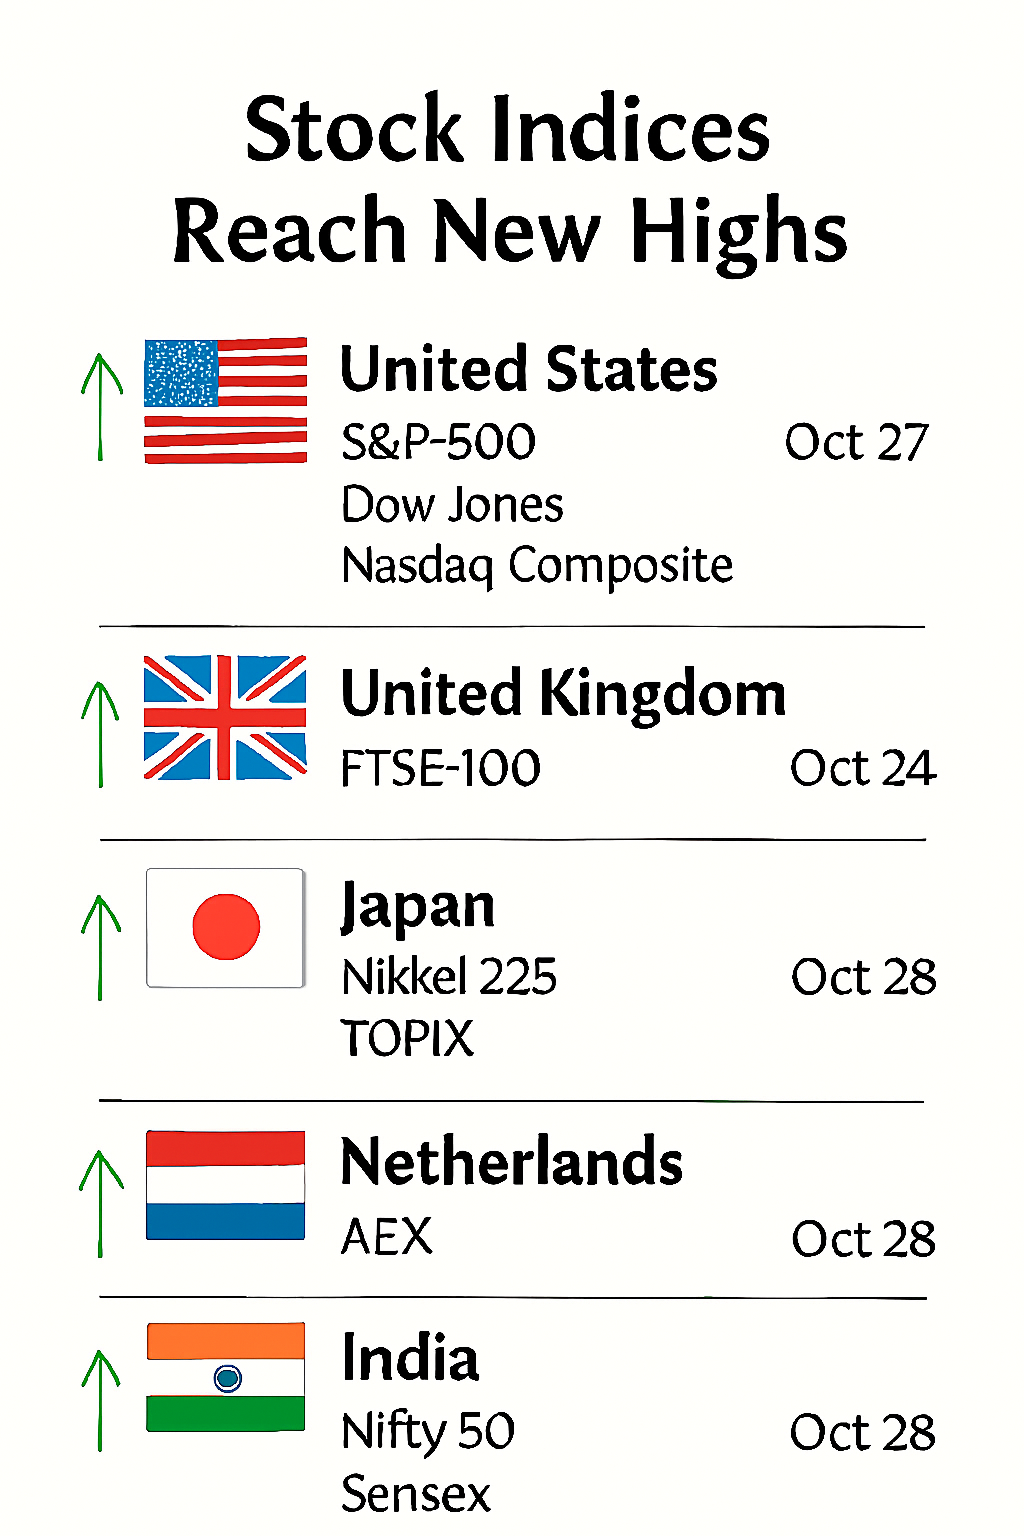
Global stock hit new highs October 2025

🌍 Country📈 Index Name🗓️ Date🔝 Closing Value
🇺🇸 United StatesS&P 500Oct 276,875.16
🇺🇸 United StatesDow JonesOct 2747,544.59
🇺🇸 United StatesNasdaq CompositeOct 2723,637.46
🇬🇧 United KingdomFTSE 100Oct 249,662.00
🇳🇱 NetherlandsAEX IndexOct 28966.82
🇮🇳 IndiaNifty 50Oct 2825,966
🇮🇳 IndiaSensexOct 2884,778.84
🇯🇵 JapanNikkei 225Oct 2850,342.25
🇯🇵 JapanTOPIXOct 283,285.87

These rallies were largely fueled by optimism over a potential U.S.–China trade deal, cooler inflation data, and expectations of interest rate cuts from the Fed.

Is there a market crash, correction or a pullback coming to a stock market near you soon?

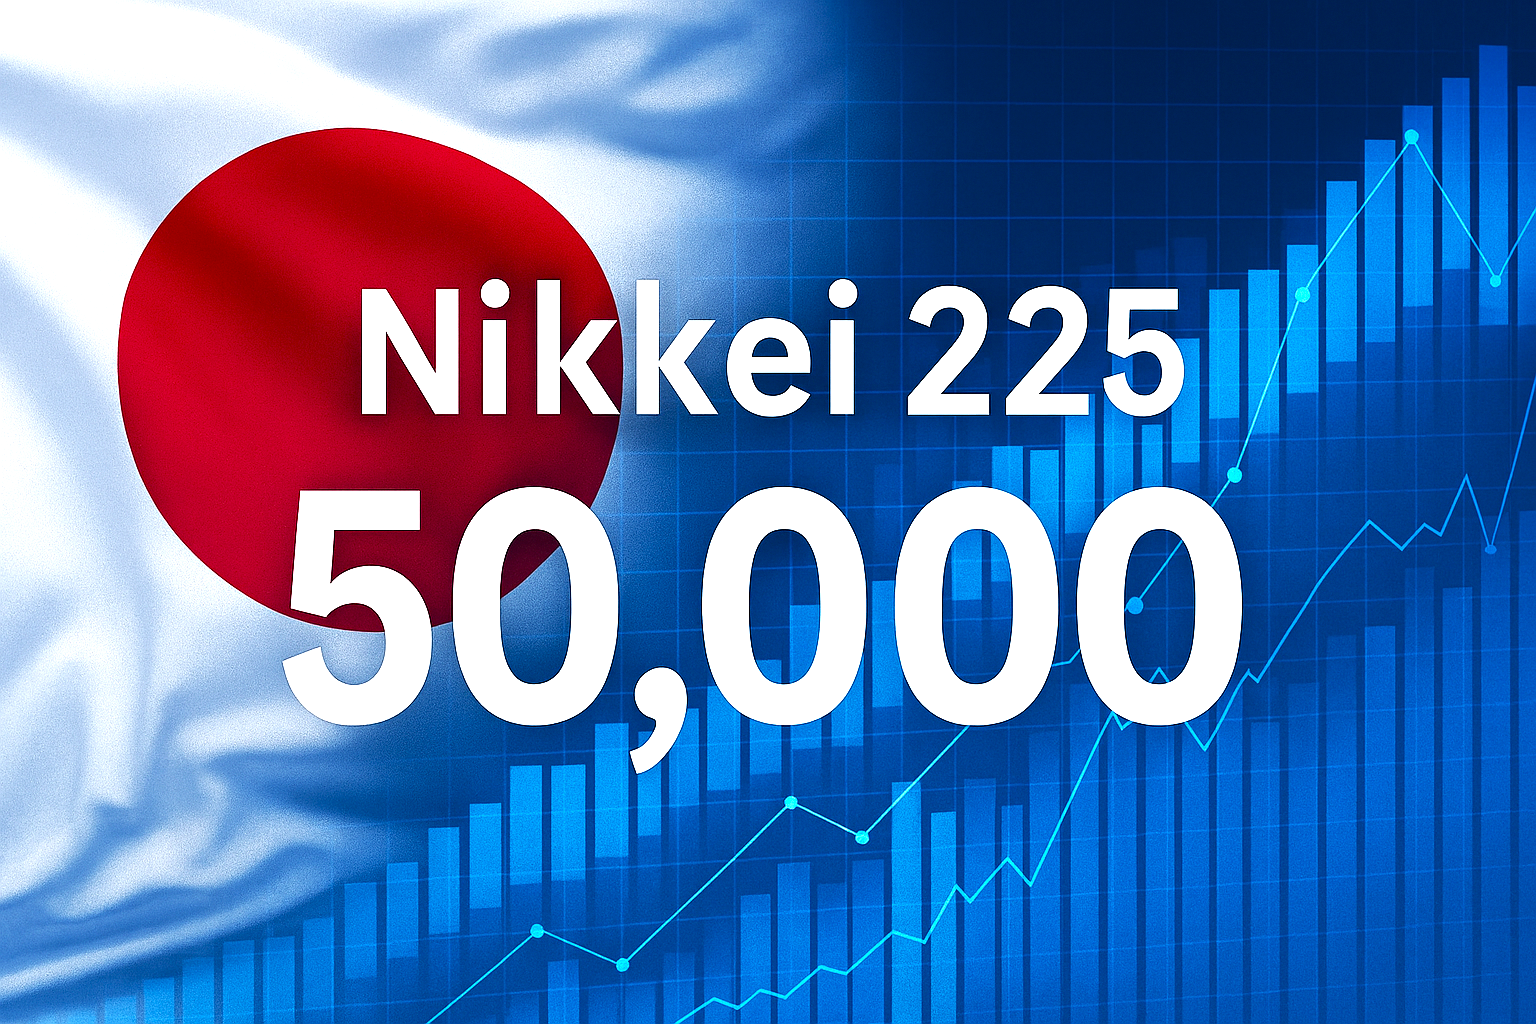
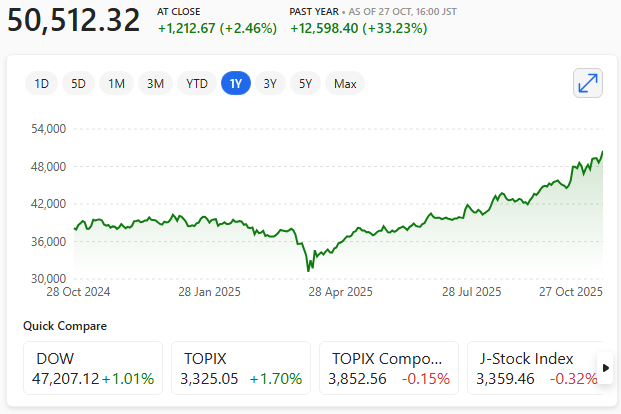
Nikkei 225 Breaks 50,000: A Milestone Fueled by Tech Trade and Policy Optimism

Nikkei at new all-time high!

Japan’s benchmark Nikkei 225 index surged past the 50,000 mark for the first time in history, marking a symbolic milestone for Asia’s second-largest economy.

The rally reflects a potent mix of domestic resilience, global investor appetite, and strategic policy shifts that have redefined Japan’s market narrative.

The breakthrough comes amid renewed optimism surrounding U.S.-China trade negotiations, with President Trump signalling progress ahead of a key meeting with Japan’s Sanae Takaichi.

Investors are betting on a thaw in geopolitical tensions, which could unlock export growth for Japan’s tech-heavy industrial base.

Driving the rally are heavyweight stocks in semiconductors, robotics, and AI infrastructure—sectors buoyed by global demand and Japan’s push to become a regional data hub.

Nikkei 225 Index at new history high above 50,000

Companies like Tokyo Electron and SoftBank have seen double-digit gains, fuelled by bullish earnings and strategic pivots toward AI and automation.

Domestically, the Bank of Japan’s continued accommodative stance has kept borrowing costs low, while corporate governance reforms have attracted foreign capital.

The weaker yen has also boosted exporters, making Japanese goods more competitive abroad.

Symbolically, the 50,000 threshold represents more than just market exuberance—it’s a vote of confidence in Japan’s ability to adapt, innovate, and lead in a shifting global landscape.

While risks remain—from demographic headwinds to geopolitical flashpoints—the Nikkei’s ascent signals a new era of investor engagement with Japan’s evolving economic story.

Has the S&P 500 Become an AI Index?

S&P 500 becoming an AI index

In recent months, the S&P 500 has shown signs of evolving from a broad economic barometer into something far more concentrated: a proxy for artificial intelligence optimism.

While traditionally viewed as a diversified snapshot of American corporate health, the index’s current composition and market behaviour suggest it’s increasingly tethered to the fortunes of a handful of AI-driven giants.

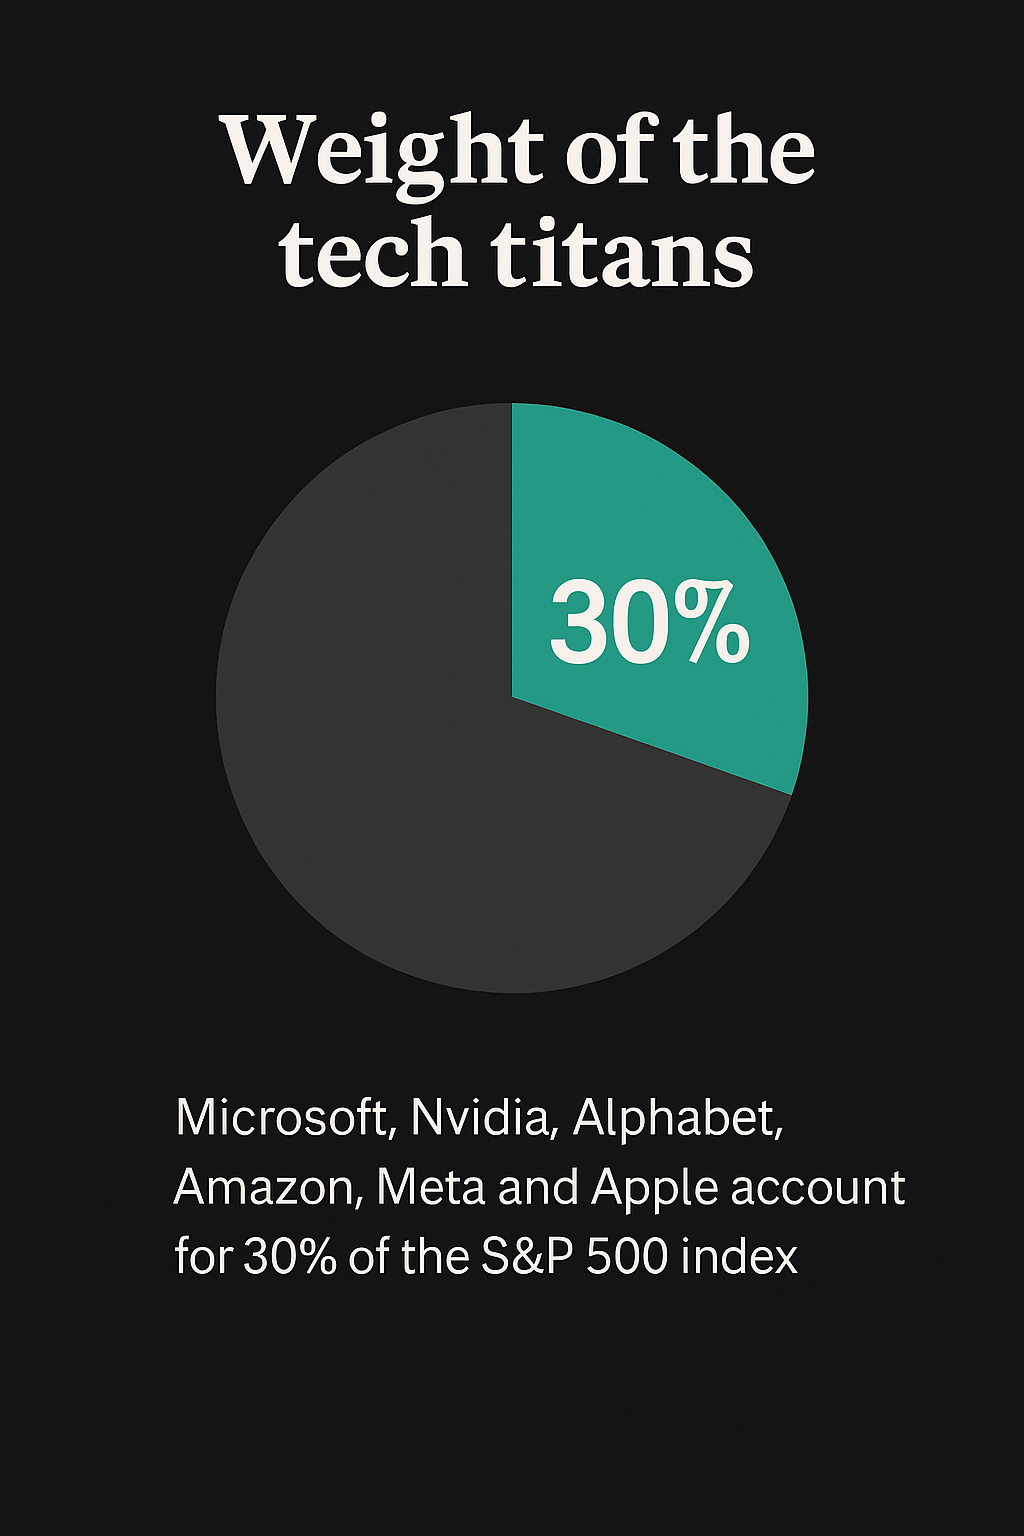
At the heart of this transformation is the dominance of mega-cap tech firms. Microsoft, Nvidia, Alphabet, Amazon, Meta, and Apple now account for a disproportionate share of the index’s total market capitalisation.

As of late 2025 that heady combination of AI led tech represents just over 30% of the S&P 500.

AI in S&P 500
Six AI related companies represent 30% of the S&P 500

These companies aren’t merely adjacent to AI—they’re building its infrastructure, shaping its software ecosystems, and embedding it into consumer and enterprise products.

Nvidia, for instance, has become synonymous with AI hardware, its valuation soaring on the back of demand for high-performance chips powering generative models and data centres.

Recent analysis reveals that roughly 8% of the S&P 500’s weight is directly tied to AI-related revenue.

An additional 25 companies within the index are actively developing AI technologies, even if those efforts haven’t yet translated into standalone revenue streams. This includes sectors as varied as autonomous vehicles, quantum computing, and predictive analytics.

Investor behaviour has only amplified this shift. The index’s recent rally has been fuelled largely by enthusiasm for AI breakthroughs, with capital flowing into stocks perceived as future beneficiaries of machine learning and automation.

This momentum has led some analysts to warn of valuation bubbles, urging diversification away from AI-heavy names in case of a sector-wide correction.

Narrower narrative

Symbolically, the S&P 500’s identity is shifting. Once a mirror of industrial and consumer strength, it now reflects a narrower narrative—one of technological acceleration and speculative belief in artificial intelligence.

This raises philosophical questions about what the index truly represents: is it still a measure of economic breadth, or has it become a momentum gauge for a single transformative theme?

For editorial observers, this evolution offers fertile ground. The index’s transformation can be read not just as a financial trend, but as a cultural signal—suggesting that AI is no longer a niche innovation, but the dominant lens through which investors, executives, and policymakers interpret the future.

Whether this concentration proves visionary or vulnerable remains to be seen.

But one thing is clear: the S&P 500 is no longer just a mirror of the American economy—it’s increasingly a reflection of our collective bet on intelligent machines.

30% of S&P 500

As of 2025, Microsoft, Nvidia, Alphabet, Amazon, Meta, and Apple—often grouped as part of the ‘Magnificent Seven’—collectively represent approximately 30% of the S&P 500’s total market capitalisation.

That’s a staggering concentration for just six companies in an index meant to reflect the broader U.S. economy.

For context, their combined performance was responsible for roughly two-thirds of the S&P 500’s total gains in 2024—a clear signal that the index’s movement is increasingly tethered to the fortunes of a few dominant tech giants.

Concerns about credit contagion are back as troubles in U.S. regional banks shake global markets

U.S. Bank Credit Woes!

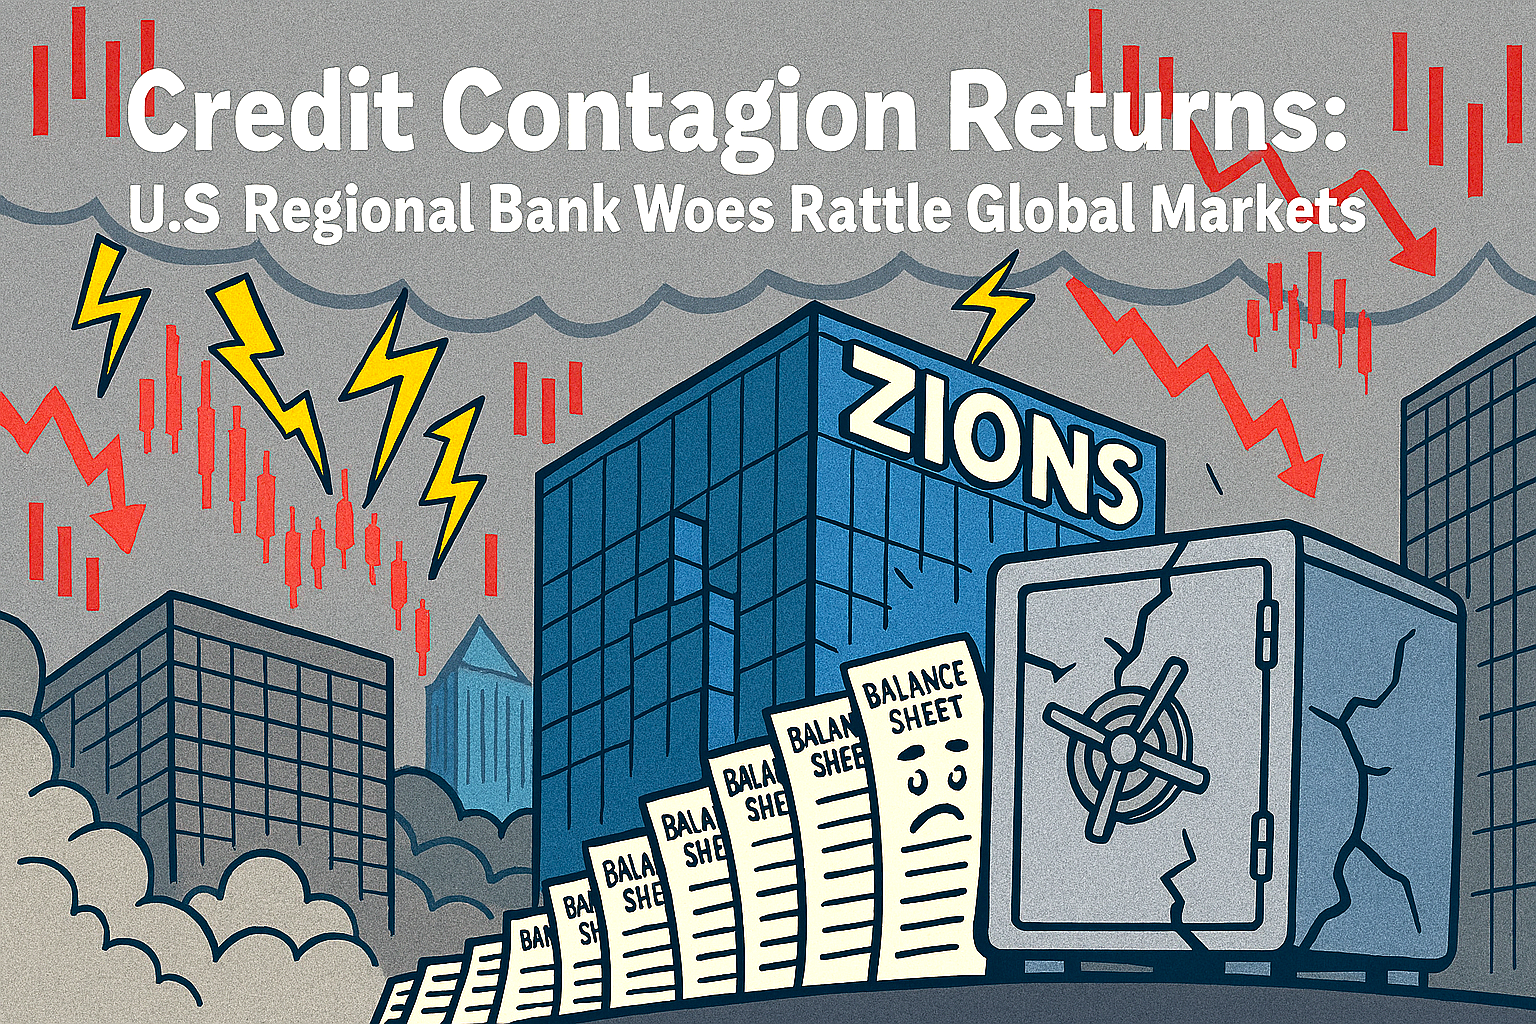
On Friday 17th October 2025, a fresh wave of credit concerns erupted across financial markets, triggered by troubling disclosures from U.S. regional lenders Zions Bancorporation and Western Alliance.

Both banks revealed significant exposure to deteriorating commercial real estate loans, reigniting fears of systemic fragility just months after the collapse of Silicon Valley Bank and Signature Bank.

The revelations sent shockwaves through Wall Street. Shares in Zions plunged over 11% in early trading, while Western Alliance dropped nearly 9%.

Larger institutions weren’t spared either—JP Morgan, Bank of America, and Citigroup all saw declines, as investors reassessed the health of the broader banking sector.

Volatile

The CBOE Volatility Index (VIX), often dubbed Wall Street’s ‘fear gauge’, spiked to its highest level since April, signalling a sharp uptick in investor anxiety.

The panic quickly spread across the Atlantic. UK lenders bore the brunt of the fallout, with Barclays tumbling 6.2%, Standard Chartered down 5.4%, and NatWest shedding 4.8%.

£13 billion loss to UK banks

In total, nearly £13 billion was reportedly wiped off the value of British banks in a single trading session. The FTSE 100 closed down 1.5%, its worst performance in over a month.

At the heart of the crisis lies commercial real estate—a sector battered by high interest rates, remote working trends, and declining occupancy. U.S. regional banks, which often hold concentrated portfolios of property loans, are particularly vulnerable.

Analysts warn that rising defaults could trigger a domino effect, undermining confidence in institutions previously deemed stable.

The Bank of England’s Financial Stability Report had already flagged elevated risks from global fragmentation and sovereign debt pressures. As did the IMF Financial Stability Report.

Credit outlook review

The events of Friday 17th October 2025 appear to validate those concerns, with Moody’s and other agencies now reviewing credit outlooks for multiple institutions.

While some commentators view the sell-off as a temporary overreaction, others see it as a harbinger of deeper trouble.

The symbolic resonance is hard to ignore: vaults cracking, balance sheets buckling, and trust—once again—on the brink. Why?

For editorial observers, the moment invites reflection. Is this merely a cyclical tremor, or the start of a structural reckoning?

Either way, the illusion of resilience has been punctured. And as markets brace for further disclosures, the spectre of contagion looms large.

Remember the sub-prime loans fiasco?

I thought banks were ‘funded and ring-fenced’ more now to prevent this from happening again.

TSMC’s Profit Soars 39% Amid AI Chip Boom!

Chip factory

Taiwan Semiconductor Manufacturing Company (TSMC) has posted a record-breaking 39% surge in third-quarter profit, underscoring its pivotal role in the global AI revolution.

The world’s largest contract chipmaker reported net income of NT$452.3 billion (£11.4 billion), far exceeding analyst expectations and marking a new high for the company.

Revenue climbed 30.3% year-on-year to NT$989.92 billion, driven by insatiable demand for high-performance chips powering artificial intelligence applications.

Tech giants including Nvidia, OpenAI, and Oracle have ramped up orders for TSMC’s cutting-edge processors, fuelling the company’s meteoric rise.

TSMC’s CEO, C.C. Wei, reportedly attributed the growth to ‘unprecedented investment in AI infrastructure’, noting that the company’s advanced nodes are now central to training large language models and deploying generative AI tools.

Despite global economic headwinds and ongoing trade tensions, TSMC’s strategic expansion—including a $165 billion global buildout across Arizona, Europe, and Japan—is positioning it as the backbone of next-gen computing.

The results also reflect a broader shift in the semiconductor landscape. As traditional consumer electronics plateau, AI-driven demand is reshaping supply chains and investment priorities.

Analysts suggest that AI chip spending could surpass $1 trillion in the coming years, with TSMC poised to capture a significant share.

For investors and industry observers, the message is clear: AI isn’t just a trend—it’s a fundamental shift. And TSMC, with its unparalleled fabrication expertise and global influence, is quietly shaping the future.

As the AI arms race accelerates, TSMC’s performance offers a glimpse into the future of tech: one where silicon, not software, defines the frontier.

The company’s latest earnings are not just a financial milestone—they’re a signal of where innovation is headed next.

Oracle Cloud reportedly to deploy 50,000 AMD AI chips, signalling direct competition with Nvidia

Oracle Cloud AI

Oracle Bets Big on AMD AI Chips, Challenging Nvidia’s Dominance

Oracle Cloud Infrastructure has announced plans to deploy 50,000 AMD Instinct MI450 graphics processors starting in the second half of 2026, marking a bold strategic shift in the AI hardware landscape.

The move signals a direct challenge to Nvidia’s long-standing dominance in the data centre GPU market, where it currently commands over 90% market share.

AMD’s MI450 chips, unveiled earlier this year, are designed for high-performance AI workloads and can be assembled into rack-sized systems that allow 72 chips to function as a unified engine.

This architecture is tailored for inferencing tasks—an area Oracle believes AMD will excel in. ‘We feel like customers are going to take up AMD very, very well’, reportedly said Karan Batta, Oracle Cloud’s senior vice president.

The announcement comes amid a broader realignment in the AI ecosystem. OpenAI, historically reliant on Nvidia hardware, has recently inked a multi-year deal with AMD involving processors requiring up to 6 gigawatts of power.

If successful, OpenAI could acquire up to 10% of AMD’s shares, further cementing the chipmaker’s role in next-generation AI infrastructure.

Oracle’s pivot also reflects its ambition to compete with cloud giants like Microsoft, Amazon, and Google. With a reported five-year cloud deal with OpenAI potentially worth $300 billion, Oracle is positioning itself not just as a capacity provider but as a strategic AI enabler.

While Nvidia remains a formidable force, Oracle’s investment in AMD chips underscores a growing appetite for alternatives.

As AI demands scale, diversity in chip supply could become a competitive advantage—especially for enterprises seeking flexibility, cost efficiency, and innovation beyond the Nvidia ecosystem.

The AI arms race is far from over, but Oracle’s latest move suggests it’s no longer content to play catch-up. It’s aiming to redefine the rules.

Wall Street’s Fear Gauge Surges: What the Spike in Volatility Signals

VIX Fear gauge

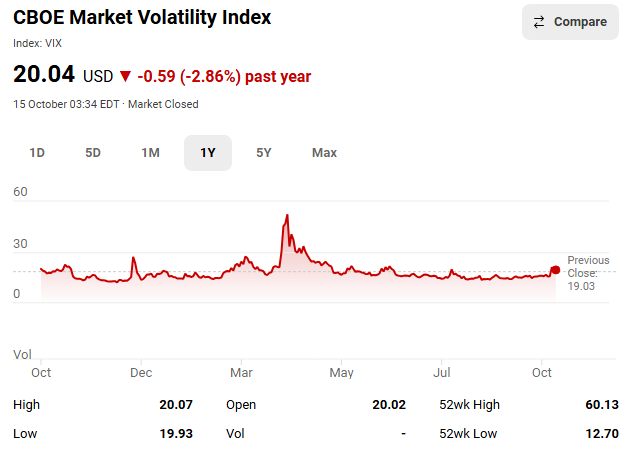
Wall Street’s so-called ‘fear gauge’—officially known as the CBOE Volatility Index (VIX)—has surged to its highest level since April 2025, jolting investors out of a months-long lull and reigniting concerns about market stability.

On 14th October 2025, the VIX briefly spiked above 22.9 before settling near 19.70, a sharp rise from recent lows that had hovered below 14.

The VIX is a real-time market index that reflects investors’ expectations for volatility over the next 30 days. Often dubbed the ‘fear gauge’, it’s derived from S&P 500 options pricing and tends to rise when traders seek protection against sharp market declines.

CBOE (VIX Index) slowly creeping up again October 2025 – So called Fear Index

A reading above 20 typically signals heightened anxiety and increased demand for hedging strategies.

This latest spike was triggered by renewed tensions between the U.S. and China, including Beijing’s announcement of sanctions against American subsidiaries of South Korean shipbuilder Hanwha Ocean.

The move, widely seen as retaliation for Washington’s export controls, sent shockwaves through tech-heavy indices. The Dow dropped over 500 points, while the Nasdaq slid nearly 2%.

For months, markets had basked in a rare stretch of calm, buoyed by AI-driven optimism and resilient earnings. But the VIX’s resurgence suggests that investors are now recalibrating their risk assessments.

It’s not just about trade wars—concerns over interest rates, geopolitical instability, and tech sector overvaluation are converging.

While a rising VIX doesn’t guarantee a crash, it often precedes periods of turbulence. For editorial observers, it’s a symbolic pulse check on investor psychology—a reminder that beneath euphoric rallies, fear never fully disappears.

As Wall Street braces for further shocks, the fear gauge is once again flashing caution. Whether it’s a tremor or a tremor before the quake remains to be seen.

Markets on a Hair Trigger: Trump’s Tariff Whiplash and the AI Bubble That Won’t Pop

Markets move as Trump tweets

U.S. stock markets are behaving like a mood ring in a thunderstorm—volatile, reactive, and oddly sentimental.

One moment, President Trump threatens a ‘massive increase’ in tariffs on Chinese imports, and nearly $2 trillion in market value evaporates.

The next, he posts that: ‘all will be fine‘, and futures rebound overnight. It’s not just policy—it’s theatre, and Wall Street is watching every act with bated breath.

This hypersensitivity isn’t new, but it’s been amplified by the precarious state of global trade and the towering expectations placed on artificial intelligence.

Trump’s recent comments about China’s rare earth export controls triggered a sell-off that saw the Nasdaq drop 3.6% and the S&P 500 fall 2.7%—the worst single-day performance since April.

Tech stocks, especially those reliant on semiconductors and AI infrastructure, were hit hardest. Nvidia alone lost nearly 5%.

Why so fickle? Because the market’s current rally is built on a foundation of hope and hype. AI has been the engine driving valuations to record highs, with companies like OpenAI and Anthropic reaching eye-watering valuations despite uncertain profitability.

The IMF and Bank of England have both warned that we may be in stage three of a classic bubble cycle6. Circular investment deals—where AI startups use funding to buy chips from their investors—have raised eyebrows and comparisons to the dot-com era.

Yet, the bubble hasn’t burst. Not yet. The ‘Buffett Indicator‘ sits at a historic 220%, and the S&P 500 trades at 188% of U.S. GDP. These are not numbers grounded in sober fundamentals—they’re fuelled by speculative fervour and a fear of missing out (FOMO).

But unlike the dot-com crash, today’s AI surge is backed by real infrastructure: data centres, chip fabrication, and enterprise adoption. Whether that’s enough to justify the valuations remains to be seen.

In the meantime, markets remain twitchy. Trump’s tariff threats are more than political posturing—they’re economic tremors that ripple through supply chains and investor sentiment.

And with AI valuations stretched to breaking point, even a modest correction could trigger a cascade.

So yes, the market is fickle. But it’s not irrational—it’s just balancing on a knife’s edge between technological optimism and geopolitical anxiety.

One tweet can tip the scales.

Fickle!

China’s rare Earth clampdown continues to send shockwaves through global markets

Rare Earth Materials

China’s latest tightening of rare earth exports has reignited global concerns over supply chain fragility and strategic resource dependence.

With Beijing now requiring special permits for the export of key rare earth elements—used in everything from electric vehicles to missile guidance systems—the move is widely seen as a geopolitical lever in an increasingly fractured global trade landscape.

Rare earths, despite their name, are not scarce—but China controls over 60% of global production and an even larger share of refining capacity. The new restrictions, framed as national security measures, have already begun to ripple through equity markets.

Shares of Western mining firms such as Albemarle and MP Materials surged on the news, as investors bet on alternative sources gaining traction. Meanwhile, defence and tech stocks in Europe dipped, reflecting fears of supply bottlenecks and rising input costs1.

This isn’t China’s first foray into rare earth brinkmanship. Similar curbs in 2010 triggered a scramble for diversification, but progress has been slow.

The current squeeze coincides with rising tensions over semiconductor access and military technology, suggesting a broader strategy of resource weaponisation.

For investors, the message is clear: rare earths are no longer just a niche commodity—they’re a geopolitical flashpoint. Expect increased volatility in sectors reliant on high-performance magnets, batteries, and advanced optics.

Countries like the US, Australia, and Canada are accelerating domestic mining initiatives, but scaling up remains a long-term play.

In the short term, China’s grip on rare earths is tightening—and markets are reacting accordingly.

As the global economy pivots toward electrification and AI-driven infrastructure, the battle over these elemental building blocks is only just beginning. The stocks may rise and fall, but the strategic stakes are climbing ever higher.

China’s sweeping export restrictions on rare earths have triggered a sharp rally in related stocks, especially among U.S.-based producers and processors.

The market is interpreting Beijing’s move as both a supply threat and a strategic opportunity for non-Chinese firms to gain ground.

📈 Some companies in the spotlight

  • USA Rare Earth surged nearly 15% in a single day and is up 94% over the past five weeks, buoyed by speculation of a potential U.S. government investment and its vertically integrated magnet production pipeline.
  • NioCorp Developments, Ramaco Resources, and Energy Fuels all posted gains of approximately between 9–12%.
  • MP Materials, the largest U.S. rare earth miner, rose over 6% following news of tighter Chinese controls. The company recently secured a strategic equity deal with the U.S. Department of Defence.
  • Albemarle, Lithium Americas, and Trilogy Metals also saw modest gains, reflecting broader investor interest in critical mineral plays.
Company / SectorStock MovementStrategic Note
MP Materials (US)↑ +6%DoD-backed, key US supplier
USA Rare Earth↑ +15%Magnet pipeline, gov’t investment buzz
NioCorp / Ramaco / Energy Fuels↑ +9–12%Domestic mining surge
European Defence Stocks↓ 2–4%Supply chain fears
Chinese Magnet Producers↔ / ↓Export permit uncertainty

China’s new rules, effective December 1st, require export licences for any product containing more than 0.1% rare earths or using Chinese refining or magnet recycling tech. This has intensified scrutiny on global supply chains and elevated the strategic value of domestic alternatives.

🧭 Investor sentiment is shifting toward companies that can offer secure, non-Chinese sources of rare earths—especially those with downstream capabilities like magnet manufacturing. The rally suggests markets are pricing in long-term geopolitical risk and potential government backing.

Weekend update

Is President Trump in control of the stock market? A comment on TruthSocial suggesting that more China tariffs might be introduced in response to China’s restrictions on rare earth materials reportedly wipes out around $2 trillion from U.S. stocks.

Then it reverses as Trump says, ‘All will be fine’. Stocks climb back up. What’s going on?

It’s just a game.

But who is the game master?

Is Bitcoin truly an asset class investment?

Is Bitcoin truly an asset class investment?

Bitcoin’s status as an asset class remains fiercely debated—its classification hinges on whether one prioritises institutional frameworks or symbolic disruption.

✅ Arguments for Bitcoin as an asset class

Many investors treat Bitcoin as a distinct asset class due to its unique characteristics:

  • Scarcity: With a capped supply of 21 million coins, Bitcoin mirrors commodities like gold.
  • Divisibility & Fungibility: It can be split into smaller units, and each unit is interchangeable.
  • Liquidity: It’s widely traded and easily converted into fiat currencies.
  • Store of Value: Often dubbed ‘digital gold’, especially in inflationary climates.
  • Low correlation: Bitcoin’s behaviour diverges from traditional assets, offering potential diversification.

❌ Arguments against Bitcoin as an asset class

Institutions such as Hargreaves Lansdown argue Bitcoin lacks the stability and intrinsic value required for formal classification:

  • Volatility: Its dramatic price swings make it riskier than equities or bonds.
  • No intrinsic value: Unlike shares or debt instruments, Bitcoin doesn’t generate income or cash flow.
  • Regulatory ambiguity: Its decentralised nature and evolving legal status complicate analysis.
  • Speculative behaviour: Critics liken it more to a speculative punt than a foundational portfolio component.

So…

Bitcoin’s contested identity as an asset class reflects a deeper philosophical divide: is it a legitimate store of value shaped by digital innovation, or a speculative mirage challenging financial orthodoxy?

While its traits—scarcity, liquidity, and decentralised architecture—suggest asset-like behaviour, its volatility and lack of intrinsic value leave its classification unresolved.

For investors and thinkers alike, Bitcoin invites not just financial analysis but existential reflection on what we trust, value, and rebel against in the evolving economy.

AI Crash! Correction or pullback? Something is coming…

AI Bubble concerns

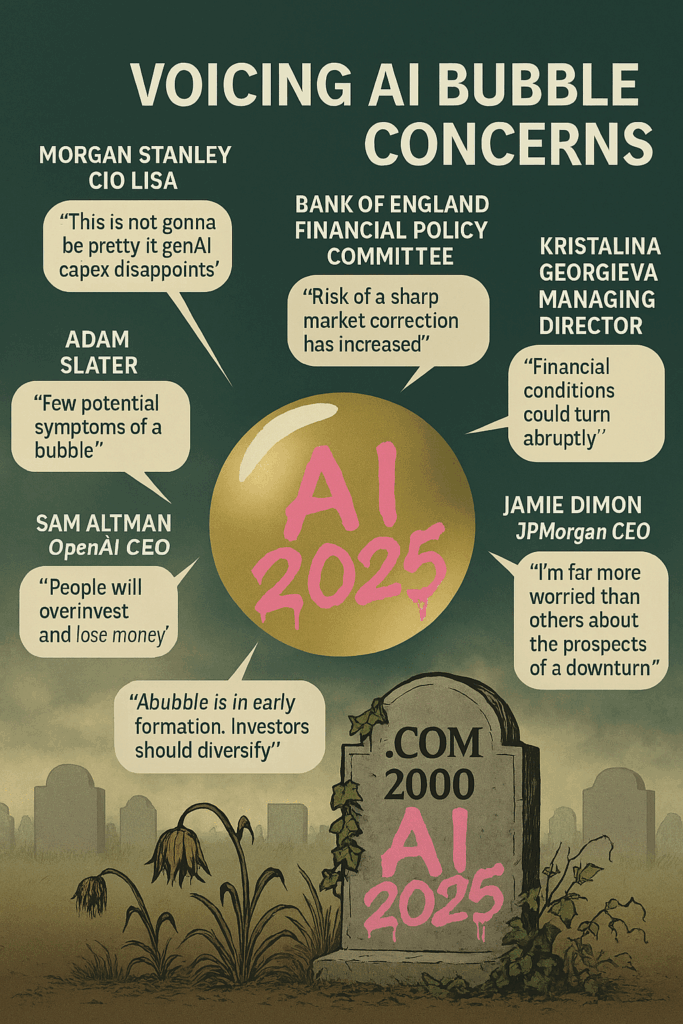
Influential figures and institutions are sounding the AI alarm—or at least raising eyebrows—about the frothy valuations and speculative fervour surrounding artificial intelligence.

Who’s Warning About the AI Bubble?

🏛️ Bank of England – Financial Policy Committee

  • View: Stark warning.
  • Quote: “The risk of a sharp market correction has increased.”
  • Why it matters: The BoE compares current AI stock valuations to the dotcom bubble, noting that the top five S&P 500 firms now command nearly 30% of market cap—the highest concentration in 50 years.

🏦 Jerome Powell – Chair, U.S. Federal Reserve

  • View: Cautiously sceptical.
  • Quote: Assets are “fairly highly valued.”
  • Why it matters: While not naming AI directly, Powell’s remarks echo broader concerns about tech valuations and investor exuberance.

🧮 Lisa Shalett – Chief Investment Officer, Morgan Stanley Wealth Management

  • View: Deeply concerned.
  • Quote: “This is not going to be pretty” if AI capital expenditure disappoints.
  • Why it matters: Shalett warns that 75% of S&P 500 returns are tied to AI hype, likening the moment to the “Cisco cliff” of the early 2000s.

🌍 Kristalina Georgieva – Managing Director, IMF

  • View: Watchful.
  • Quote: Financial conditions could “turn abruptly.”
  • Why it matters: Georgieva highlights the fragility of markets despite AI’s productivity promise, warning of sudden sentiment shifts.

🧨 Sam Altman – CEO, OpenAI

  • View: Self-aware caution.
  • Quote: “People will overinvest and lose money.”
  • Why it matters: Altman’s admission from inside the AI gold rush adds credibility to bubble concerns—even as his company fuels the hype.

📦 Jeff Bezos – Founder, Amazon

  • View: Bubble-aware.
  • Quote: Described the current environment as “kind of an industrial bubble.”
  • Why it matters: Bezos sees parallels with past tech manias, suggesting that infrastructure spending may be overextended.

🧠 Adam Slater – Lead Economist, Oxford Economics

  • View: Analytical.
  • Quote: “There are a few potential symptoms of a bubble.”
  • Why it matters: Slater points to stretched valuations and extreme optimism, noting that productivity projections vary wildly.

🏛️ Goldman Sachs – Investment Strategy Division

  • View: Cautiously optimistic.
  • Quote: “A bubble has not yet formed,” but investors should “diversify.”
  • Why it matters: Goldman acknowledges the risks while maintaining that fundamentals may still justify valuations—though they advise caution.
AI Bubble voices infographic October 2025

🧠 Julius Černiauskas and the Oxylabs AI/ML Advisory Board

🔍 View: The AI hype is nearing its peak—and may soon deflate.

  • Černiauskas warns that AI development is straining environmental resources and public trust. He’s pushing for responsible and sustainable AI practices, noting that transparency is lacking in how many models operate.
  • Ali Chaudhry, research fellow at UCL and founder of ResearchPal, adds that scaling laws are showing their limits. He predicts diminishing returns from simply making models bigger, and expects tightened regulations around generative AI in 2025.
  • Adi Andrei, cofounder of Technosophics, goes further: he believes the Gen AI bubble is on the verge of bursting, citing overinvestment and unmet expectations

🧠 Jamie Dimon on the AI Bubble

🔥 View: Sharply concerned—more than most as widely reported

  • Quote: “I’m far more worried than others about the prospects of a downturn.”
  • Context: Dimon believes AI stock valuations are “stretched” and compares the current surge to the dotcom bubble of the late 1990s.

📉 Key Warnings from Dimon

  • “Sharp correction” risk: He sees a real danger of a sudden market pullback, especially given how AI-related stocks have surged disproportionately—like AMD jumping 24% in a single day after an OpenAI deal.
  • “Most people involved won’t do well”: Dimon told the BBC that while AI will ultimately pay off—like cars and TVs did—many investors will lose money along the way.
  • “Governments are distracted”: He criticised policymakers for focusing on crypto and ignoring real security threats, saying: “We should be stockpiling bullets, guns and bombs”.
  • “AI will disrupt jobs and companies”: At a trade event in Dublin, he warned that AI’s ubiquity will shake up industries and employment across the board.

And so…

The AI boom of 2025 has ignited a speculative frenzy across global markets, with tech stocks soaring and investors piling into anything labelled “AI-adjacent.”

But beneath the euphoria, a chorus of high-profile warnings is growing louder. From the Bank of England and IMF to JPMorgan’s Jamie Dimon and OpenAI’s Sam Altman, concerns are mounting that valuations are dangerously stretched, capital is overconcentrated, and the narrative is outpacing reality.

Dimon likens the moment to the dotcom bubble, while Altman admits many will “lose money” chasing the hype. Analysts point to classic bubble signals: retail mania, corporate FOMO, and earnings divorced from fundamentals.

Even as AI’s long-term utility remains promising, the short-term exuberance may be setting the stage for a sharp correction.

Whether it’s a pullback or a full-blown crash, the mood is shifting—from uncritical optimism to wary anticipation.

The question now is not whether AI will change the world, but whether markets have priced in too much, too soon.

We have been warned!

The AI bubble will pop – it’s just a matter of when and not if.

Go lock up your investments!

Gold rockets through $4,000 for the first time ever amid global uncertainty

Gold at highest level ever!

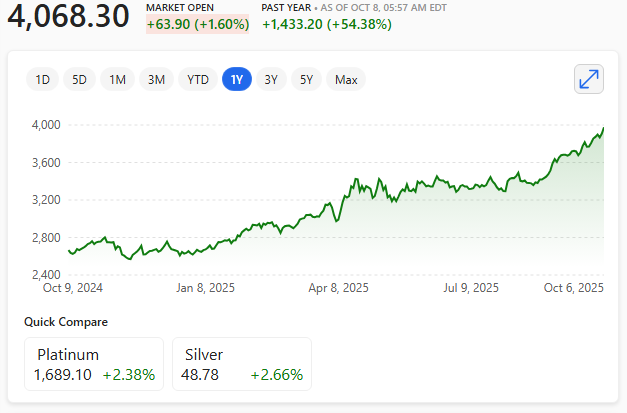
Gold has surged to an unprecedented high, crossing the $4,000 per ounce mark for the first time on 7th October 2025.

The precious metal peaked at $4,014.60, driven by a potent mix of geopolitical instability, expectations of U.S. interest rate cuts, and sustained central bank buying. This marks a 52% rise since January 2025, making it the strongest annual rally since 1979.

It continued its ascent into the 8th October 2025 touching $4,045 in early trade, likely with more to come. That’s over £3,000 per troy ounce.

The rally reflects a flight to safety as investors seek refuge from volatile bond markets, a weakening dollar, and the ongoing U.S. government shutdown.

One-year gold price chart – looking at December 2025 futures

With key economic data delayed and the Federal Reserve expected to cut rates twice before year-end, gold’s appeal as a non-yielding asset has intensified.

Physical demand remains robust, particularly in India, where festive buying and a weaker Rupee have pushed domestic prices to ₹1,30,300 per 10 grams in Delhi.

Meanwhile, institutional investors and sovereign funds continue to accumulate gold, signalling long-term strategic shifts away from traditional reserve currencies.

While technical indicators suggest the market may be overbought in the short term, analysts expect any correction to be modest.

For now, gold’s glittering ascent underscores a broader loss of confidence in conventional assets—and a renewed faith in timeless value.

Bulls and Bubbles: The stock market euphoria

Bubbles and Bulls

In the world of stock markets, few phenomena are as captivating—or as perilous—as bull runs and speculative bubbles.

Though often conflated, these two forces represent distinct psychological and financial dynamics that shape investor behaviour and market outcomes.

Bull Markets: Confidence with Momentum

A bull market is defined by sustained price increases across major indices. Typically driven by strong economic fundamentals, corporate earnings growth, and investor optimism.

In the U.S., iconic bull runs include the post-World War II expansion. The 1980s Reagan-era boom, and the tech-fuelled rally of the 2010s. The Dot-Com bull run, and subsequesnt crash is probably the most famous.

Bull markets feed on confidence: low interest rates, rising employment, and technological innovation often act as catalysts. Investors pile in, believing the upward trajectory will continue—sometimes for years.

But even bulls can lose their footing. When valuations stretch beyond reasonable earnings expectations, the line between bullish enthusiasm and irrational exuberance begins to blur.

Bubbles: Euphoria Untethered from Reality

A bubble occurs when asset prices inflate far beyond their intrinsic value. This is fuelled not by fundamentals but by speculation and herd mentality.

The dot-com bubble of the late 1990s is a textbook example. Companies with no profits—or even products—saw their valuations soar simply for having ‘.com’ in their name.

Similarly, the U.S. housing bubble of the mid-2000s was driven by easy credit and the belief that property prices could only go up.

Bubbles often follow a predictable arc: stealth accumulation, media attention, public enthusiasm, and finally, a euphoric peak.

When reality sets in—be it through disappointing earnings, regulatory shifts, or macroeconomic shocks—the bubble bursts! Leaving behind financial wreckage and a trail of disillusioned investors.

Spotting the Difference

While bull markets can be healthy and sustainable, bubbles are inherently unstable. The key distinction lies in valuation discipline.

Bulls are supported by earnings and growth; bubbles are driven by hype and fear of missing out (FOMO).

Tools like the cyclically adjusted price-to-earnings (CAPE) ratio and historical trend analysis can help investors discern whether they’re riding a bull or inflating a bubble.

📉 The Aftermath and Opportunity Ironically, the collapse of a bubble often sows the seeds for the next bull market. As excesses are purged and valuations reset, long-term investors find opportunities in the rubble.

The challenge lies in resisting the emotional extremes—greed during the rise, panic during the fall—and maintaining a clear-eyed view of value.

In markets, as in life, not every rise is rational, and not every fall is fatal

As of October 2025, many analysts argue that the U.S. stock market is exhibiting classic signs of a bubble. Valuations stretched across major indices and speculative behaviour intensifying—particularly in mega-cap tech stocks and passive index funds.

The S&P 500 recently hit record highs despite a backdrop of political gridlock and a government shutdown. This suggests a disconnect between price momentum and underlying economic risks.

Indicators like Market Cap to Gross Value Added (GVA) and excessive investor sentiment point to a speculative mania. Some experts are calling it the largest asset bubble in U.S. history.

While a full-blown crash hasn’t materialised yet, the market’s frothy conditions and historical October volatility have many bracing for a potential correction.

Nikkei hit another new all-time high!

Nikkei 225 hits new high!

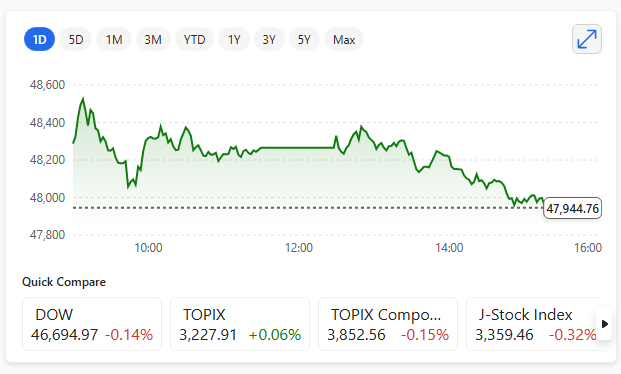
Japan’s Nikkei 225 hit another record high on October 7th 2025 for the second consecutive session. Intraday trading saw the Nikkei rip through 40,500.

The rally was driven by a tech-fueled surge, especially after a landmark deal between OpenAI and AMD sent shockwaves through global markets.

Nikkei 225 one-day chart 7th October 2025

AMD’s stock soared nearly 24%, challenging Nvidia’s dominance and lifting chip-related stocks in Tokyo like Advantest, Tokyo Electron, and Renesas Electronics.

The backdrop’s fascinating too: this optimism comes amid political upheaval in Japan, with Sanae Takaichi’s recent rise to LDP leadership sparking hopes of fresh fiscal stimulus.

However, on a cautionary note: Japan’s bond market is flashing warning signs—yields are spiking to levels not seen since 2008