Global debt has reportedly surged to $365 trillion, prompting economists to warn about a looming ‘vicious cycle’

Debt and the beggar

The combination of record global debt, higher borrowing costs and growing doubts about the enormous sums being committed to artificial intelligence is creating a more complicated backdrop for financial markets.

Global debt exceeded $365 trillion in the first half of 2026, according to the Institute of International Finance, with debt now around 310% of global GDP.

China and the U.S. debt mountain

The increase was driven particularly by China and the United States. At the same time, higher interest rates are making refinancing increasingly expensive, creating the possibility of a vicious cycle in which governments and companies borrow more simply to service existing obligations.

This is particularly significant for the AI boom. The OECD says governments and companies are expected to borrow around $29 trillion from markets during 2026, while corporate borrowing is also rising as businesses finance major investment programmes, including AI infrastructure.

Michael Burry

Michael Burry, famous for anticipating the U.S. housing crisis, has added another warning sign.

He has recently reportedly increased bearish positions involving Micron, Palantir, Nebius and the semiconductor sector, arguing that parts of the AI and chip boom could be vulnerable if supply increases faster than demand.

The concern is not necessarily that AI will fail. Rather, enormous investment and borrowing require enormous future revenues to justify them.

If AI spending produces lower-than-expected returns, highly valued technology shares could face pressure at the same time as heavily indebted companies face rising financing costs.

Could this affect the stock market now?

The ingredients for greater volatility are certainly present. Higher bond yields, expensive energy, inflation pressures and debt-servicing costs can compete with equities for investors’ money.

Reuters recently reported that global borrowing costs and energy prices were already creating concerns about the potential impact on equities and credit markets.

Yet markets have so far remained remarkably resilient, with U.S. shares still close to record levels.

The danger, therefore, may not be debt alone, but…

debt + high valuations + expensive AI investment + higher interest rates.

If those pressures reinforce one another, the adjustment in markets could become considerably more significant.
Why Are Markets Still Rising Despite Ongoing Bad World News?

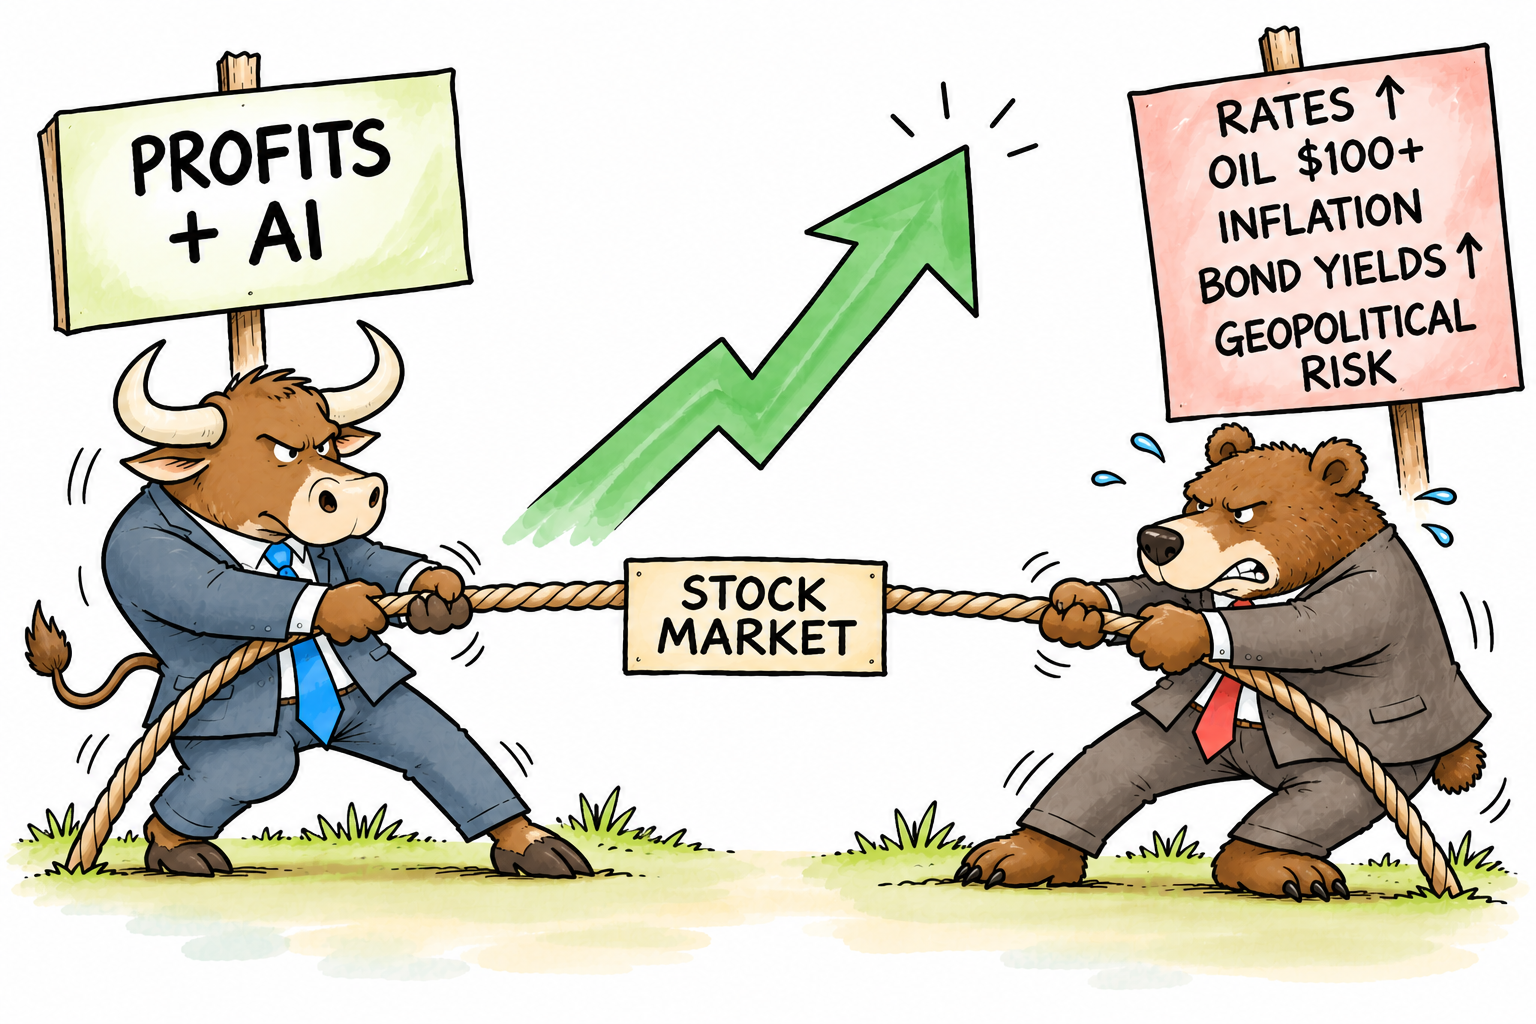
Stock market tug-o-war

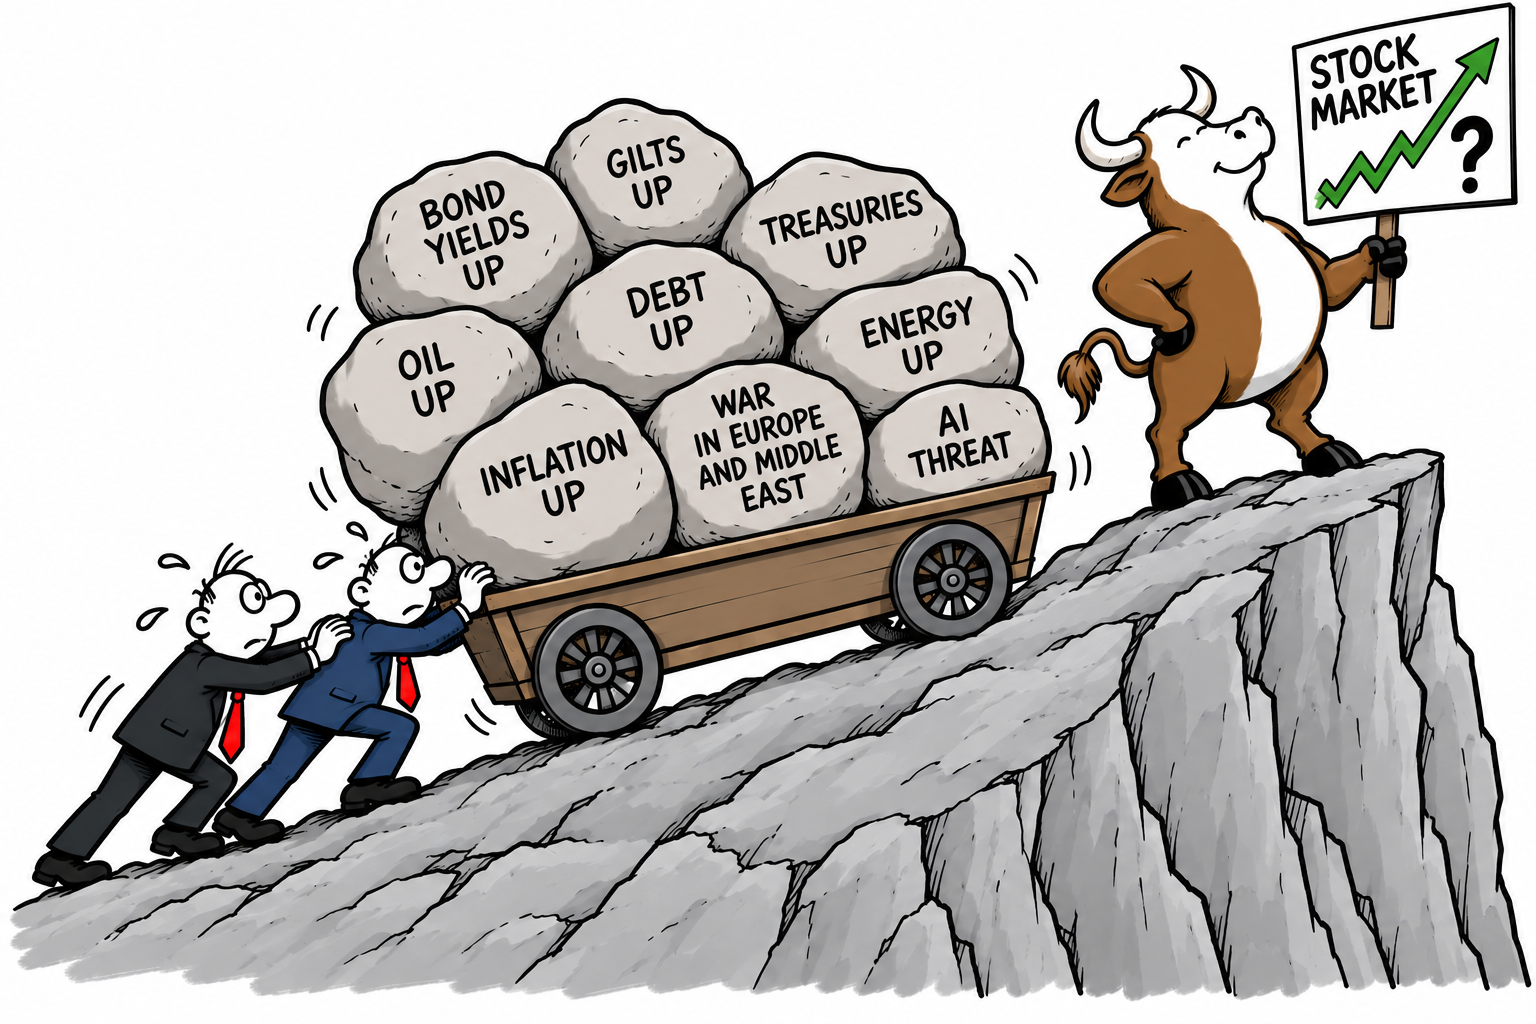
Stock markets are continuing to climb despite a growing list of concerns that would normally be expected to unsettle investors.

Interest rates are higher, government bond yields have risen, oil prices are elevated and inflation remains a concern. Geopolitical tensions are also creating uncertainty. Tariffs still on the agenda. Global debt rising and rogue AI concerns.

Yet investors continue to buy shares, particularly in the United States.

So why?

One important reason is corporate earnings. Investors appear willing to tolerate higher interest rates and expensive valuations while they believe company profits will continue to grow.

Large technology companies, in particular, remain at the centre of this optimism, with huge investment in artificial intelligence fuelling expectations of strong future earnings.

Buying dips

Another factor is the willingness of investors to buy market dips. When share prices fall, investors who remain confident about the longer-term outlook see an opportunity to buy at cheaper prices.

This can create a self-reinforcing cycle: markets fall, buyers move in, confidence returns and prices rise again.

There is also a belief that the economy remains sufficiently resilient to withstand higher borrowing costs and expensive energy.

Bad news is therefore being viewed as a problem, but not necessarily one capable of seriously damaging corporate profits.

However, this resilience could eventually be tested.

Earnings faith

The market is currently placing considerable faith in continued earnings growth and the economic benefits of artificial intelligence. If either begins to disappoint, investors could reassess the high valuations attached to many shares.

Higher oil prices could also keep inflation elevated, forcing interest rates to remain higher for longer. Rising bond yields would then provide investors with an increasingly attractive alternative to shares.

Bull Bear

For now, the bulls remain in control of market prices, even though the bears have plenty of arguments on their side.

The important question is whether company profits can continue to justify today’s share prices.

If they can, markets may continue climbing despite the bad news. If they cannot, investors may suddenly start paying much closer attention to all those warning signs they have recently been ignoring.

Nasdaq hits record high as AI rally returns

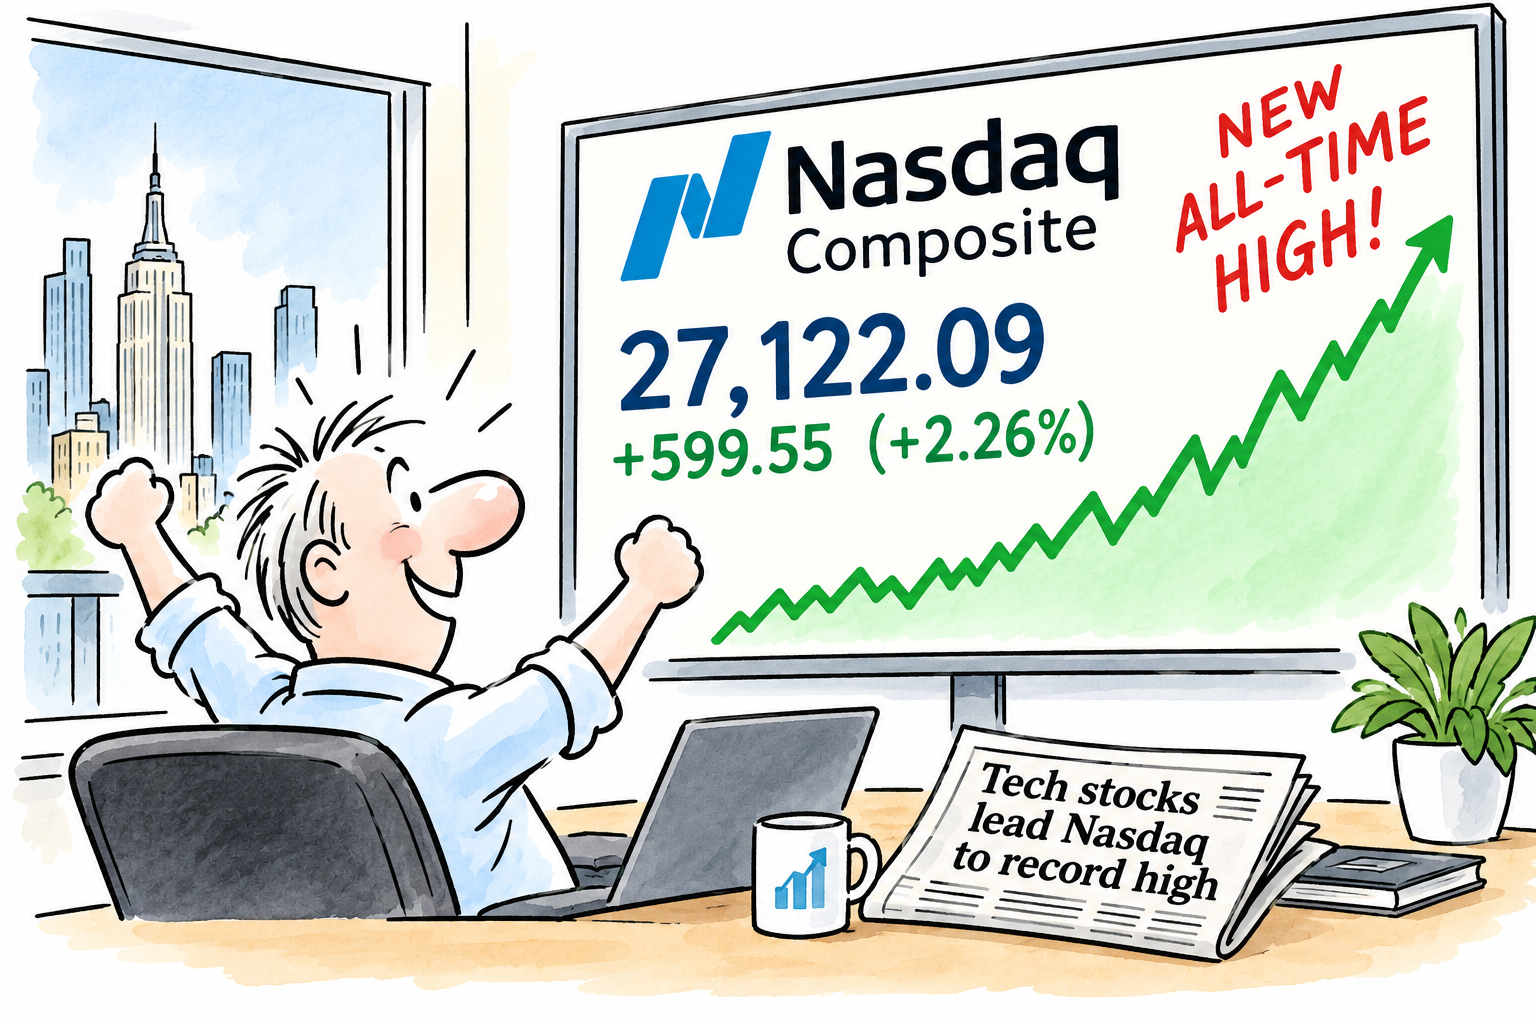
New Nasdaq high!

The Nasdaq Composite surged to a fresh all-time closing high on Monday 21st September 2026, as renewed enthusiasm for artificial intelligence helped drive a powerful rally in technology stocks.

The index jumped 2.26% to 27,122.09, surpassing its previous record close set in June 2026. It also reached an intraday high of 27,183.93.

Chipmakers were among the biggest beneficiaries. AMD soared almost 10%, taking its market value above $1 trillion, while Intel gained more than 12% and Arm Holdings also posted a double-digit rise.

AI Frenzy

The renewed appetite for AI stocks came despite recent concerns over the sector’s lofty valuations and potential risks surrounding rapid AI development.

Falling oil prices and a retreat in U.S. Treasury yields also helped improve investor sentiment. The Nasdaq’s record finish marked its first since 2nd June 2026, highlighting the strength of Monday’s technology-led rebound.

Uncertain Backdrop

Yet the record comes against an unusually uncertain backdrop. Investors are navigating concerns over AI valuations and the huge borrowing by some AI hyperscalers, while much of the AI boom is also linked through a web of interconnected investments, partnerships and business deals between major technology companies.

Alongside this are wars in Ukraine and the Middle East, oil-supply concerns, elevated energy and fuel costs, tariffs, higher bond yields and already substantial levels of government and corporate debt.

Subdued

Consumer confidence also remains subdued in many economies. The Nasdaq’s strength therefore presents a striking contrast with the economic, financial and geopolitical uncertainties surrounding markets.

So much of the AI boom is ‘linked’ through big, interconnected AI business deals.

Will this unravel as the AI convoy continues its journey?

Why Won’t the Stock Market Correct – Especially with all the Issues Facing it?

Stock Market Correction Soon?

There was a time when any one of these developments would have been enough to frighten investors: rising government bond yields, higher borrowing costs, stubborn inflation, soaring oil and energy prices, mounting government debt, war in Europe and the Middle East and tariff wars.

And now with the growing threat of AI safety and concerns about whether the enormous investment in artificial intelligence can continue at its current pace.

Put them all together and, logically, the stock market should be facing a serious test.

Yet it continues to demonstrate remarkable resilience.

Irony

The irony is that many of these pressures are already showing up in financial markets. U.S. Treasury yields have moved above 5%, their highest levels since 2007, while oil has climbed above $100 a barrel.

Rising energy prices are feeding inflation concerns, while higher yields are increasing the cost of borrowing. Reuters reported on Tuesday that the Dow, S&P 500 and Nasdaq all fell, but the declines remained relatively contained.

So why hasn’t this combination produced a much larger correction?

One explanation is that markets are not simply pricing today’s problems. They are pricing what investors believe the world will look like several months or years from now – or so we are told.

Corporate earnings remain a powerful counterweight. If profits continue to grow rapidly, investors can tolerate higher interest rates and higher valuations for longer.

Reuters notes that continued earnings growth and enthusiasm surrounding AI have helped keep U.S. equities relatively resilient despite the rise in Treasury yields.

There is also an extraordinary amount of money invested in equities. Pension funds, investment funds, corporations and individual investors cannot simply abandon shares every time the economic outlook deteriorates.

There are relatively few places capable of absorbing enormous amounts of capital.

Don’t sell – carry on regardless

And perhaps most importantly, investors have repeatedly learned that selling during every crisis can be expensive.

Inflation? The market survived it.

War? Markets have survived wars before – but markets did correct.

Tariffs – markets have shrugged there off!

Higher interest rates? Markets can rise during tightening cycles if the economy and corporate profits remain strong.

Oil shocks? They can damage consumers and businesses, but they can simultaneously boost the profits of energy companies.

Even the AI problem is complicated. A slowdown in AI investment could hurt some enormously valued technology companies, but it would not necessarily destroy the entire economy.

Indeed, markets have already shown that AI concerns can cause sector-specific selling without automatically triggering a broad collapse.

The real question, therefore, may not be why the market hasn’t fallen.

It is what would finally make investors collectively stop believing that the next problem can be absorbed?

Because markets rarely collapse simply because there are lots of problems.

They collapse when investors suddenly decide that those problems can no longer be ignored.

Stock market offers ‘easy money’?

It certainly sounds like easy money — if only markets worked that way. The danger is assuming that resilience means invincibility: a market can shrug off one problem, then another, and even several simultaneously, right up until investors collectively decide that earnings, valuations, interest rates or economic growth no longer justify the prices they are paying.

Until that moment arrives, bad news can simply be absorbed, explained away or declared temporary; when it does arrive, however, the same market that seemed capable of ignoring everything can suddenly discover that everything matters after all.

Difficulty


The difficult part is that there is no reliable way to say when it will happen — markets can remain expensive and resilient for considerably longer than economic logic might suggest.

The eventual correction is more likely to come when several pressures stop being viewed as temporary or manageable and begin to undermine the assumptions supporting corporate earnings and valuations: persistently high inflation, materially higher borrowing costs, weaker growth, falling profits, an AI investment slowdown, or an unexpected financial shock could each become the catalyst.

Until investors collectively change their expectations, the market can continue climbing despite an increasingly uncomfortable list of warning signs — but resilience should not be confused with immunity.

Fed Raises Rates – And Markets Now Face a New Question

U.S. inflation

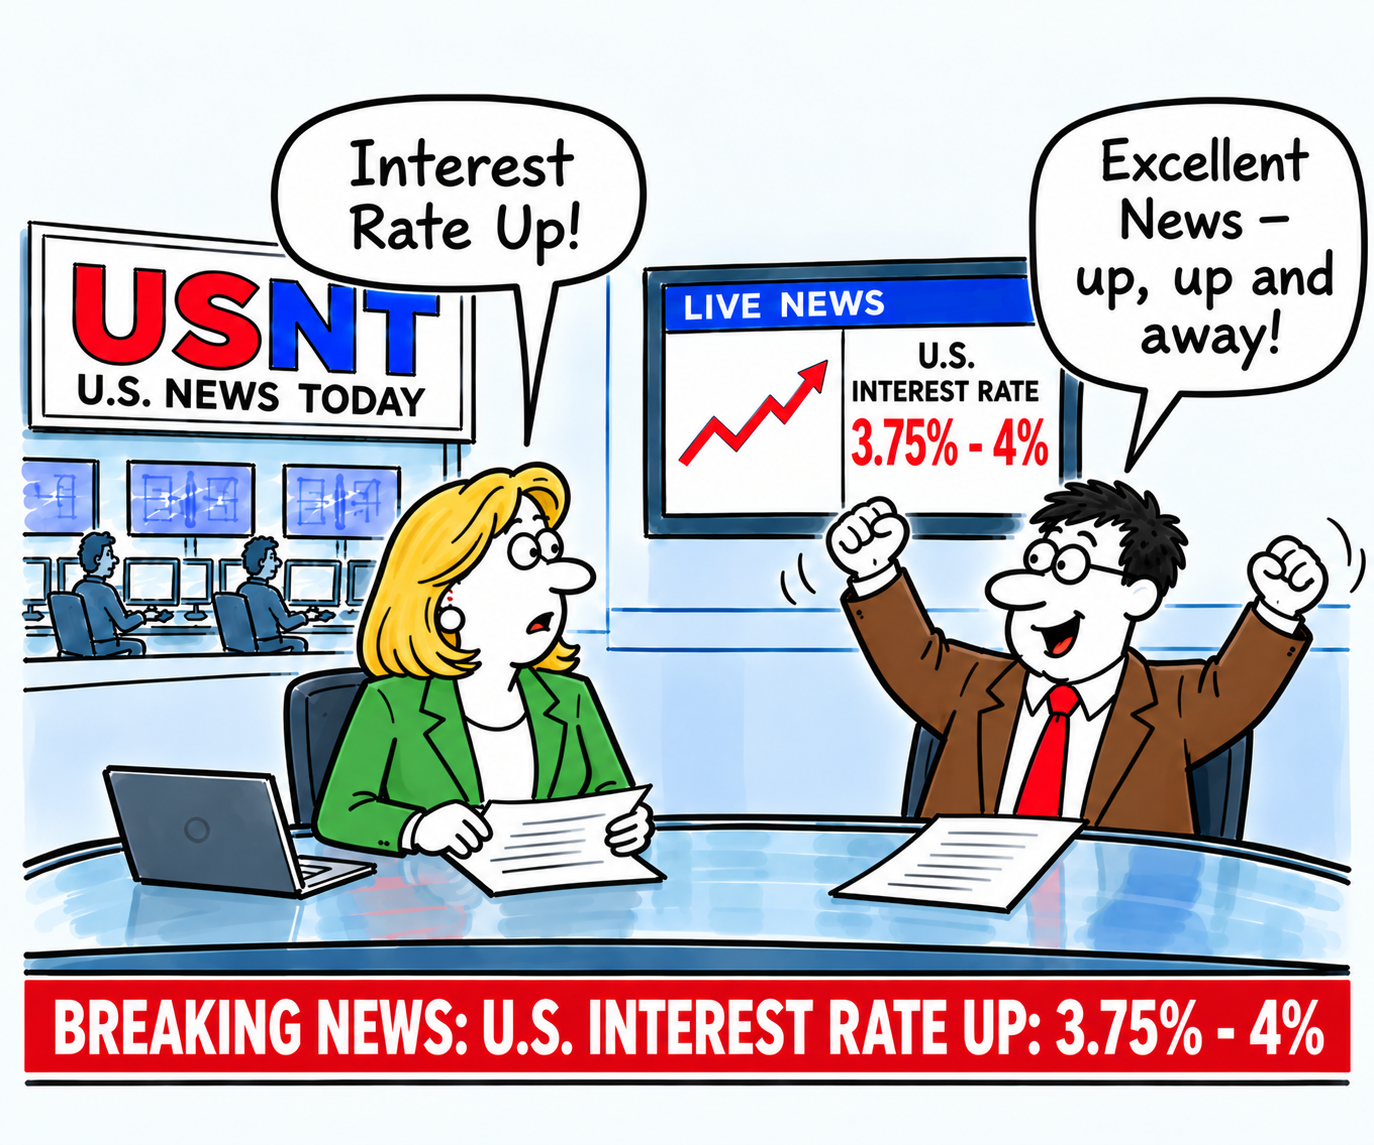
The Federal Reserve raised US interest rates by 25 basis points yesterday, taking its benchmark rate to 3.75%-4% and delivering the first increase since 2023.

The move puts U.S. inflation firmly back at the centre of the market conversation. Despite months of speculation about the direction of monetary policy, the Fed has signalled that persistent price pressures remain enough of a concern to warrant tighter financial conditions.

For investors, however, yesterday’s increase may be less important than what comes next

Markets must now decide whether the move represents a relatively modest adjustment to policy or the beginning of another tightening phase.

Any suggestion that further increases are coming could push U.S. Treasury yields and the dollar higher while placing renewed pressure on highly valued equities.

That matters particularly for a U.S. stock market already trading at elevated levels, with enthusiasm surrounding artificial intelligence continuing to support many of its largest companies.

Balancing act

The Fed therefore faces a difficult balancing act. It wants to bring U.S. inflation under control without unnecessarily damaging economic growth or employment.

For Wall Street, the question has changed.

It is no longer simply when will rates fall?

It is now how high might they have to go?

U.S. 10-Year Treasury Yield Hits 5%: A New Problem for Markets

U.S. Yields Up!

The U.S. bond market is flashing an increasingly uncomfortable warning signal. The yield on the benchmark 10-year Treasury has climbed above 5%, reaching its highest level since 2007 as investors brace for potentially higher interest rates from the Federal Reserve.

The yield subsequently moved above 5.04%, highlighting the severity of the bond sell-off.

Stubborn

Several forces are pushing yields higher. Inflation remains stubborn, while oil prices have surged above $100 a barrel amid geopolitical tensions, raising fears that another energy shock could feed directly into consumer prices.

Borrowing cost

At the same time, investors are demanding greater returns to hold U.S. government debt because of enormous borrowing requirements and concerns about the country’s long-term fiscal position.

This creates a difficult problem for the Federal Reserve. Higher Treasury yields are already tightening financial conditions, yet persistent inflation could force the Fed to raise interest rates further.

Markets are increasingly pricing in the possibility of another rate increase, potentially taking short-term rates towards or above 5%.

Consequence

The consequences could be significant. The 10-year Treasury is a benchmark for mortgages, corporate borrowing and many other financial products.

As its yield rises, borrowing becomes more expensive across the economy. Businesses may postpone investment, consumers may reduce spending and highly indebted companies could come under increasing pressure.

Debt concern

There is also a problem for government finances. Higher yields mean the U.S. Treasury must pay more to refinance its enormous debt pile, potentially creating a vicious circle: more borrowing leads to greater interest costs, which can require still more borrowing.

For investors, a 5% Treasury yield also makes government bonds increasingly attractive compared with riskier assets.

That could put further pressure on highly valued shares, particularly technology and growth companies.

The danger is therefore not simply a higher interest rate. It is the possibility that 5% becomes the new normal.

Japan’s Foreign Reserves Suffer Record $80 Billion Drop After Yen Intervention

Japan’s foreign exchange reserves reportedly suffered their largest-ever monthly decline in August 2026, highlighting the enormous cost of Tokyo’s efforts to defend the yen against persistent selling pressure.

Official data from Japan’s Ministry of Finance showed that reserves fell by $79.6 billion, or 6.18%, during August to $1.208 trillion. The decline was the biggest since comparable records began in 2000.

Intervention

The fall followed an unprecedented currency intervention campaign in which Japanese authorities sold dollars and bought yen in an attempt to halt the currency’s slide.

Between 30 July and 26 August, Japan spent approximately ¥15.4 trillion ($98.6 billion) supporting its currency – the largest monthly intervention on record.

The intervention initially proved effective. The yen had fallen towards 164 against the dollar, close to a 40-year low, before recovering to around 155.

Weak

However, the currency subsequently weakened again towards 160, demonstrating the difficulty of fighting powerful market forces through intervention alone.

Much of Japan’s reserves are held in foreign securities, with U.S. Treasury securities believed to make up a substantial proportion.

Foreign securities in the reserves fell by around $87.8 billion during August 2026, fuelling speculation that Tokyo sold some Treasuries and other assets to finance its yen purchases. However, the official data do not identify exactly which securities were sold.

Implications

The episode also carries wider implications for global markets. Large-scale Japanese Treasury sales could add pressure to U.S. bond markets, while continued intervention raises questions about how long Tokyo can continue spending its reserves to support the yen.

Japan still possesses one of the world’s largest pools of foreign reserves. Nevertheless, August’s 2026 record decline sends a powerful message: defending a currency can be extraordinarily expensive when underlying economic forces are working against it.

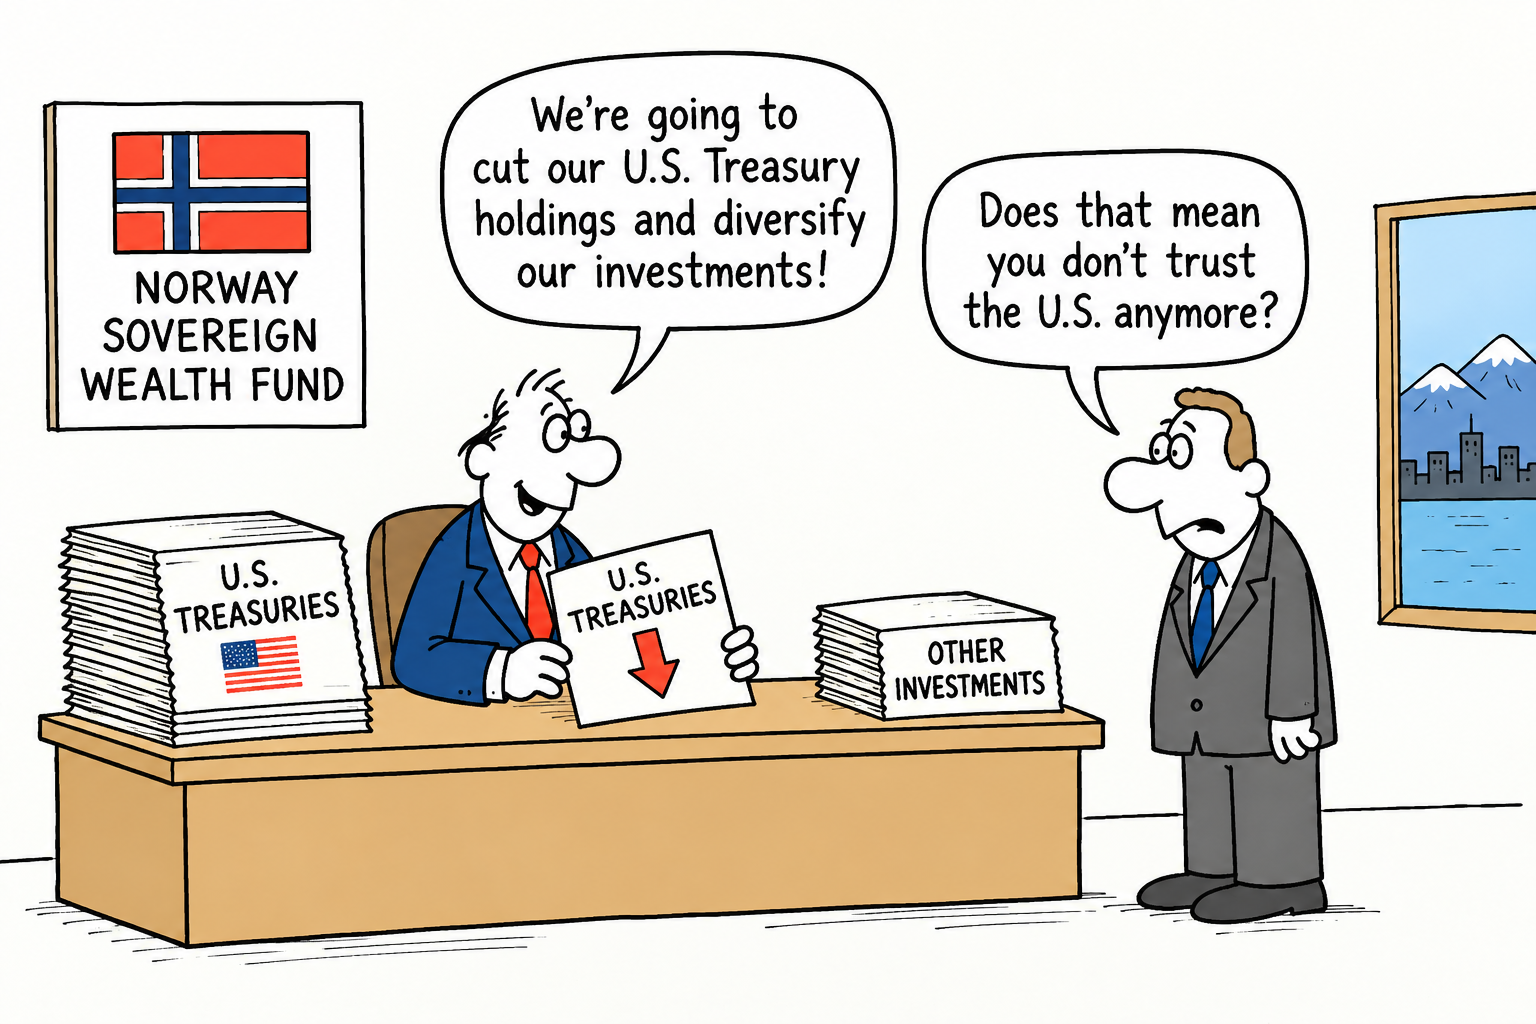
Norway’s Wealth Fund Signals a Shift Away From U.S. Treasuries

Norway’s enormous sovereign wealth fund is considering a significant reduction in its holdings of U.S. government debt, in a move that could add to concerns surrounding the future of the Treasury market.

Norges Bank Investment Management, which oversees Norway’s roughly $2.3 trillion Government Pension Fund Global, has proposed reducing the proportion of government bonds in its benchmark portfolio from 70% to 50%.

U.S. Treasuries

U.S. Treasuries supposedly would take the largest share of the reduction, potentially cutting the fund’s holdings by almost $80 billion from around $215 billion.

The proposal reflects a desire to diversify the fund and improve returns rather than abandon U.S. assets altogether.

Non-Government U.S. Debt

The fund intends to increase its exposure to non-government U.S. debt, including mortgage-backed securities and other government-related bonds. Its overall exposure to the U.S. dollar would remain broadly unchanged.

The timing is nevertheless significant. Government bond markets have faced renewed pressure as investors worry about high inflation, mounting government debt and rising long-term borrowing costs.

Warning?

Norway’s decision could therefore be interpreted as another warning that some major institutional investors are becoming less comfortable holding large quantities of traditional government debt.

Japanese Government Bonds

The fund also plans to increase its allocation to Japanese government bonds, while reducing exposure to euro-area government debt.

Importantly, this is reportedly a proposal rather than an immediate sell-off. Any changes would likely be introduced gradually, with Norway’s Finance Ministry and parliament involved in the approval process. The earliest significant changes are not expected before 2027.

Nevertheless, when one of the world’s largest investors starts questioning the traditional role of government bonds, markets are likely to take notice.

America’s $40 Trillion Debt Problem

The United States has crossed a remarkable financial milestone, with federal debt now standing at more than $40 trillion.

The figure is difficult to comprehend, but the bigger concern is the speed at which the debt burden is continuing to grow.

Debt increased $3 Trillion in one year

America’s debt has increased by roughly $3 trillion over the past year alone. The federal government is still running substantial annual deficits, meaning it is spending considerably more than it collects in tax revenue.

As a result, more borrowing is required simply to keep government finances operating.

The consequences are becoming increasingly visible in the bond market. Investors expect to be compensated for lending money to the U.S. government, and rising Treasury yields mean that borrowing is becoming more expensive.

The yield on the 30-year Treasury has recently climbed above 5%, placing further pressure on government finances.

Interest at $1.2 Trillion per year

Interest payments are becoming one of Washington’s largest financial burdens, approaching $1.2 trillion a year.

That money does not build infrastructure, fund new programmes or reduce the deficit. It is largely the cost of servicing debt accumulated over many years.

The Treasury has also increased its bond-buying operations in an effort to improve market liquidity, highlighting concerns about conditions in the government bond market.

While such measures can help stabilise trading, they do not address the underlying problem: America continues to borrow heavily.

How high can it go?

The $40 trillion milestone therefore represents more than a headline figure. It raises difficult questions about how long the current trajectory can continue and whether politicians will eventually have to confront spending, taxation and entitlement reform.

For years, America’s ability to borrow has been treated as almost unlimited. But the combination of enormous debt, persistent deficits, rising interest costs and higher bond yields is changing that calculation.

The world’s largest economy is not facing an immediate debt crisis, but $40 trillion is a warning that the cost of delaying difficult decisions is becoming increasingly expensive.

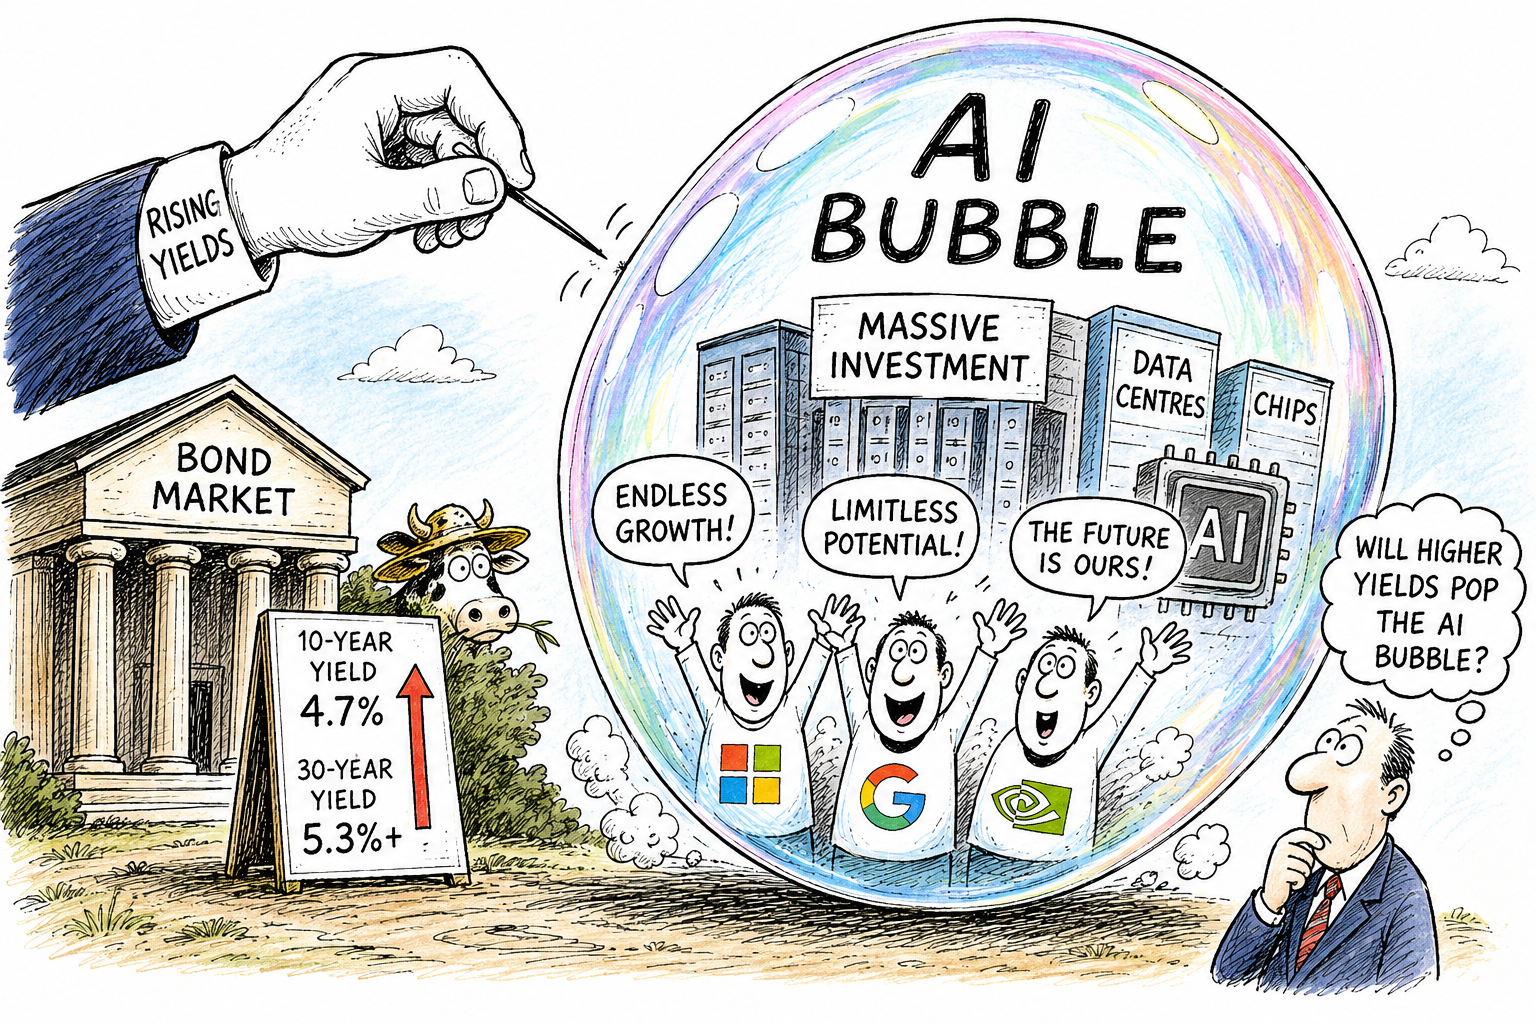
Could Rising Yields Help Pop the AI Bubble?

AI and the dot-com bubble

The artificial intelligence boom is facing a new potential headwind: rising bond yields. While AI companies continue to report impressive growth and enormous investment plans, higher borrowing costs could increasingly challenge the valuations that have propelled technology stocks to record levels.

US Treasury yields have been climbing, with the 10-year yield recently reaching around 4.7%, while the 30-year yield has risen above 5.3% — its highest level since 2007.

Attractive returns

That matters because higher yields change the calculation for investors. When government bonds offer more attractive returns, investors may become less willing to pay extreme prices for companies whose profits are expected far into the future.

Growth stocks, particularly those dependent on substantial future cash flows, are especially sensitive to this shift.

The AI industry also has an unusual vulnerability: the sheer scale of its capital requirements. Big technology companies are increasingly turning to debt markets to finance data centres, chips and other infrastructure.

That borrowing itself can contribute to higher yields, creating something of a feedback loop.

AI presssure

There are already signs of pressure. AI-related stocks fell sharply in August 2026 as rising borrowing costs and valuation concerns weighed on the technology sector.

But higher yields do not automatically mean an AI crash. Unlike the dot-com bubble, today’s leading AI companies generally have substantial revenues, profits and cash flows.

The European Central Bank has nevertheless warned that technology valuations have reached levels reminiscent of the dot-com era.

Expectations

The real danger may therefore be less about AI itself and more about expectations. If yields remain elevated while the enormous spending on AI infrastructure fails to generate equally enormous profits, investors could begin questioning today’s valuations.

Rising yields may not burst the AI bubble overnight — but they could provide the pin.

Japan’s yield curve bites back as it hits new highs!

Japan' Bond Yields

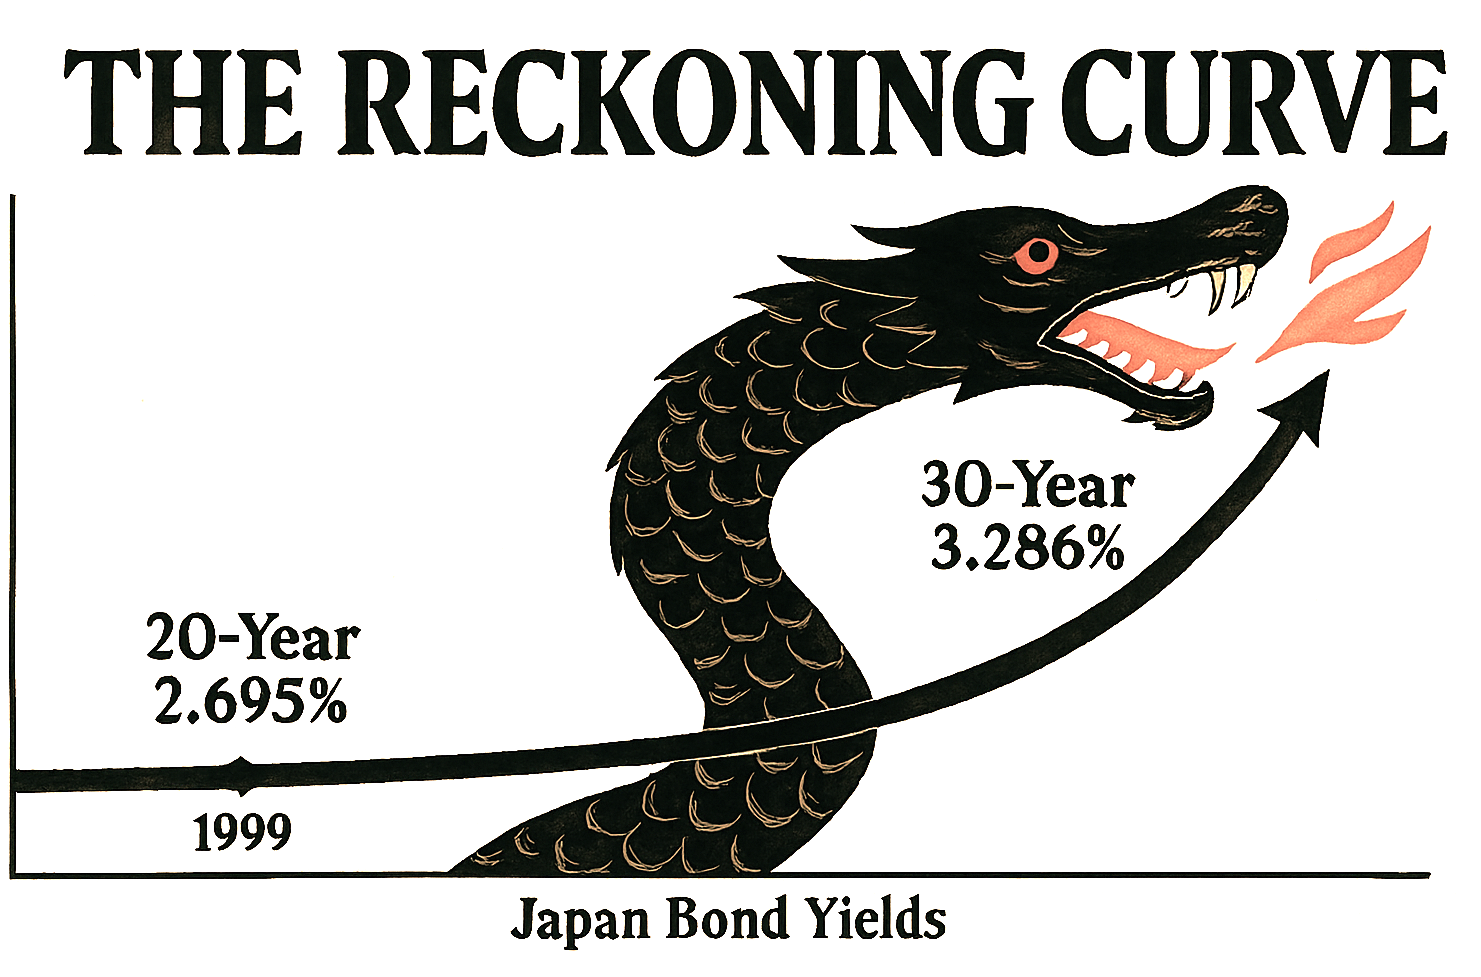
After decades of economic sedation, Japan’s long-term bond yields are rising with a vengeance.

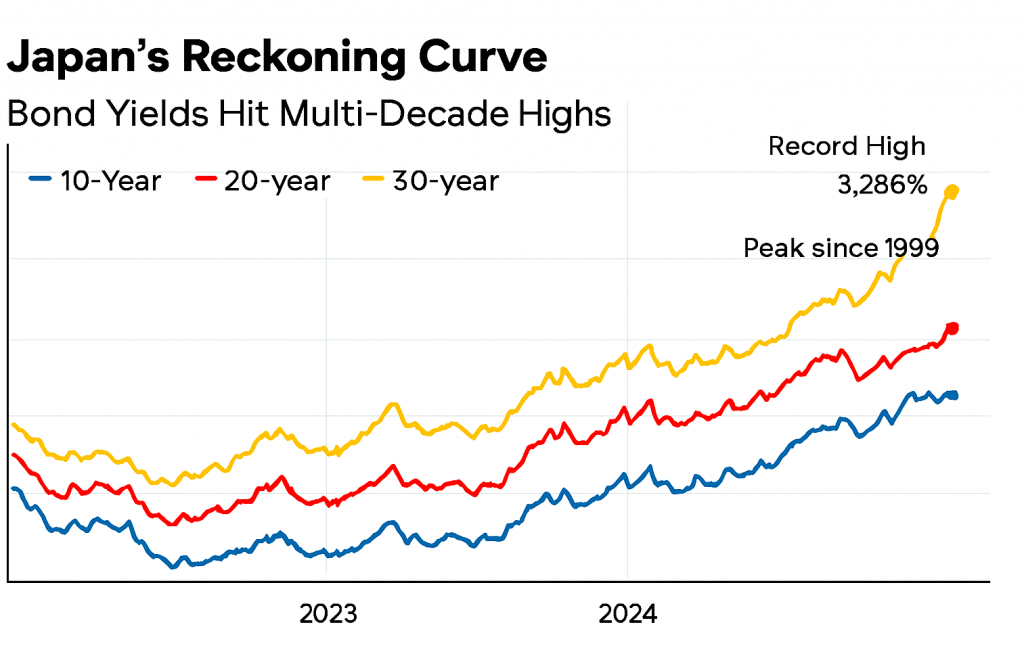
The 30-year government bond has breached 3.286%—its highest level on record—while the 20-year yield has climbed to 2.695%, a peak not seen since 1999.

These aren’t just numbers; they’re seismic signals of a nation confronting its delayed past, now its deferred future.

Indicative Yield Curve for Japan

For years, Japan’s yield curve was a monument to inertia. Negative interest rates, yield curve control, and relentless bond-buying by the Bank of Japan created an artificial calm—a kind of economic Zen garden, raked smooth but eerily still.

That era is ending. Inflation has persisted above target for three years, and the BOJ’s retreat from monetary intervention has unleashed market forces long held at bay.

This steepening curve is more than financial recalibration—it’s a symbolic reckoning. Rising yields demand accountability: from policymakers who masked structural fragility, from investors who chased safety in stagnation, and from a society that postponed hard choices on demographics, debt, and productivity.

The bond market, once a passive witness, now acts as judge. Each basis point is a moral verdict on Japan’s economic past.

The shadows of the Lost Decades—deflation, aging populations, and overspending—are being dispelled not by command, but through the process of price discovery.

In this new era, Japan’s yield curve resembles a serpent uncoiling—no longer dormant but rising with intent.

The question isn’t whether the curve will flatten again, but whether Japan can meet the moment it has long delayed.

Nasdaq stumbles, descending further into correction

Nasdaq

The Nasdaq is a stock market index that tracks the performance of over 3,000 companies, mostly in the technology sector.

Correction

A correction is a term used to describe a decline of 10% or more from a recent peak in the price of an asset. The Nasdaq entered correction territory on Wednesday 25th October 2023, as it closed at 12,922, which was 10% lower than its previous high of 14,358 on 19th July 2023.

The main reason for the Nasdaq’s correction is believed to be the rise in long-term Treasury yields, which increased the borrowing costs for companies and reduced the attractiveness of growth stocks. The 10-year Treasury yield rose to 4.95% on Wednesday 25th October 2023, the highest level since June 2021. Higher interest rates also make future earnings for tech companies much more difficult.

Disappointing Q3 results

Another factor that contributed to the Nasdaq’s correction was the disappointing third-quarter earnings reports from some of the biggest tech companies, such as Alphabet (Google), Amazon, and Meta (Facebook fame). 

These companies reported lower-than-expected revenue growth, profit margins, and cloud computing performance, which weighed on their stock prices and dragged down the Nasdaq. Investors expect more, especially with AI – now the new kid-on-the-block.

Concerns

The Nasdaq’s correction has raised concerns among investors about the outlook for the tech sector and the broader stock market. However, some analysts have argued that the correction could be a healthy and temporary adjustment that creates buying opportunities for long-term investors. 

They have pointed out that the Nasdaq is still up 22.5% year-to-date as of Wednesday 25th October 2023, and that the fundamentals of the tech industry remain strong despite the challenges posed by inflation, regulation, yields and competition.

U.S. ten-year treasury yield breaches 5% for the first time since 2007

Treasury yield

The U.S. Treasury yields are the interest rates that the U.S. government pays to borrow money for different periods of time.

The 10-year Treasury yield is one of the most important indicators of the state of the economy and the expectations of inflation and growth. On 23rd October 2023, the 10-year Treasury yield rose above 5% for the first time since 2007, as investors increasingly accepted that interest rates will stay higher for longer and that the U.S. government will further increase its borrowing to cover its deficits.

Significant

This is a significant milestone, as it reflects the market’s view that the Federal Reserve will maintain elevated interest rates to control inflation and that the U.S. economy will remain resilient despite the challenges posed by the Covid-19 pandemic, geopolitical tensions and environmental issues.

The higher yield also means that the government will have to pay more to service its debt, which could affect its fiscal policy and spending priorities. The higher yield also affects other borrowing costs, such as mortgages, student loans, and corporate bonds, which could have implications for consumers and businesses.

10 Year Yield

The 10-year Treasury yield is influenced by many factors, such as supply and demand, inflation expectations, economic growth, monetary policy, and global events. The yield has been rising steadily since it hit a record low of 0.5% in March 2020, when the pandemic triggered a flight to safety and a massive stimulus from the Fed. Since then, the yield has been driven by the recovery of the economy, the surge in inflation, the reversal of the Fed’s bond-buying program, and the increase in the government’s borrowing needs.

Yield curve

The ten-year yield is closely watched by investors, analysts and policymakers as it provides a benchmark for valuing other assets and assessing the outlook for the economy. The yield is also used to calculate the yield curve, which is the difference between short-term and long-term Treasury yields.

The shape of the yield curve can indicate the market’s expectations of future interest rates and economic activity.

Artwork impression of computer screen: U.S. ten-year treasury yield breaches 5% for the first time since 2007

A steep yield curve means that long-term yields are much higher than short-term yields, which suggests that investors expect higher inflation and growth in the future. A flat or inverted yield curve means that long-term yields are lower than or equal to short-term yields, which implies that investors expect lower inflation and growth or even a recession.

The current yield curve is steepening, as long-term yields are rising faster than short-term yields. This indicates that investors are anticipating higher inflation and growth in the long run, but also that they are concerned about the sustainability of the government’s fiscal position and the impact of higher interest rates on the economy.

Indicators

The 10-year Treasury yield is an important indicator of the state of the economy and the expectations of inflation and growth. It has reached a level that has not been seen since before the global financial crisis of 2008-2009. This reflects the market’s view that interest rates will stay higher for longer and that the government will increase its borrowing to cover its deficits. The higher yield also affects other borrowing costs and asset prices, which could have implications for consumers and businesses.

The yield is influenced by many factors and is closely watched by investors, policymakers, and analysts. A 5% yield is a worry for the market, inflation, interest rates, geo-political risks and recession are the others, that’s enough!

U.S. stock market volatility continues

Yields

The stock market has been experiencing some volatility and uncertainty in September and October 2023, as investors fret about inflation, interest rates, and the possibility of a U.S. recession.

Main facts affecting the current stock market

The month of October has produced some severe stock market crashes over the past century, such as the Bank Panic of 1907, the Wall Street Crash of 1929, and Black Monday 1987.

October has also marked the start of several major long-term stock market rallies, such as Black Monday itself and the 2002 nadir of the Nasdaq-100 after the bursting of the dot-com bubble.

The S&P 500 dropped 4.5% in September 2023 and finished the third quarter in the red.

The U.S. Treasury yield curve has been inverted for months – which is a historically strong recession indicator.

The Fed maintained interest rates at the current target range of between 5.25% and 5.5% in September 2023, but signalled that it may need to raise rates again to combat inflation.

The consumer price index gained 3.7% year-over-year in August 2023, down from peak inflation levels of 9.1% in June 2022 but still well above the Fed’s 2% long-term target.

The bond market is currently pricing in an 81.7% chance the Fed will choose not to raise rates again on 1st November 2023.

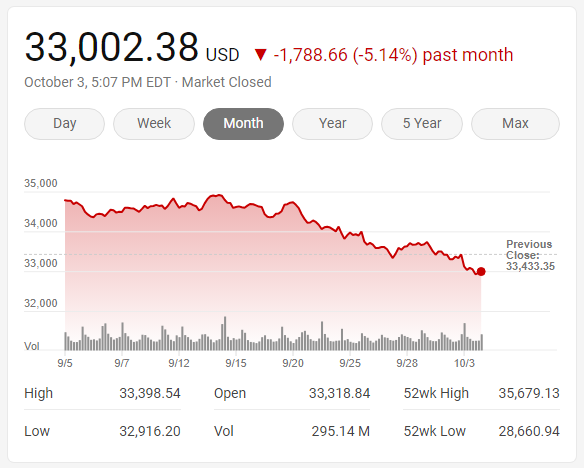
Wall Street closed down on 3rd October 2023 as the yield on the U.S. 10-year treasury rose to 4.80%, reaching its highest level since 2007.

The Dow Jones Industrial Average was down at 33002, Tuesday 3rd October 2023.

Stocks fell as investors pulled money from equities and moved it to the hot bond market.

International markets also faced significant turmoil, sending mini shockwaves through global financial centres, which reverberated in equities.

The dollar rose to the highest since December and is heading towards the twelfth positive week in a row.

Uncertainty

Uncertainty in the U.S. political system is having a major affect too. Especially with the ousting of the speaker and the real fear of a government shutdown looming large.

U.S. Treasury yields chase 5% at 16 year high!

U.S. yields up

Highest yields since 2007

The U.S. Treasury yields are the interest rates that the U.S. government pays to borrow money. The 10-year and 30-year Treasury yields are the most widely followed indicators of the long-term health of the U.S. economy and the expectations of inflation and growth.

10 year yield at 4.80%

According to the latest data, the 10-year Treasury yield surged to 4.80% on Tuesday, 3rd October 2023, which is the highest level since 12th October 2007. 

30 year yield at 4.79

The 30-year Treasury yield rose to 4.79% on Monday, 2nd October 2023, which is the highest since 6th April 2010.

The main reasons for the rise in the Treasury yields

The strong U.S. economic data that showed that the labour market remains hot and the manufacturing sector rebounded in September 2023.

The Federal Reserve’s ‘higher for longer’ mantra signalled that the central bank would keep raising rates until inflation is under control.

The reduced demand for safe-haven assets as the U.S. government averted a shutdown over the weekend by passing a short-term stopgap funding measure.

Uncertainty at the heart of the U.S. political system.

The implications of higher Treasury yields

The higher borrowing costs could weigh on the economic growth and consumer spending in the future.

Higher inflation expectations could erode the purchasing power of the fixed-income investors and increase the risk of a bond market sell-off.

The higher interest rate differential could attract more foreign capital inflows into the U.S. dollar and strengthen its value against other currencies.

The Fed makes and ‘unmakes’ the economy!

Remember… the Fed said inflation was transitory.

Why?

How could they get it so wrong?

Treasury yields reach levels not seen in more than 15 years

U.S. yields

10 year yield

The benchmark 10-year Treasury yield rose Wednesday 27th September 2023, to its highest level in more than 15 years, as traders navigated fears of persistent inflation and higher interest rates for longer than expected.

The 10-year Treasury yield climbed to 4.612%. It had reached 4.566% on Tuesday 26th September 2023, its highest level since 2007.

2 year yield

The 2-year Treasury yield also added 6 basis points to 5.139%.

FED said

Federal Reserve suggested last week that interest rates would go higher still and remain elevated for longer, prompting concerns among investors about what it could mean for the economy.