Global debt has reportedly surged to $365 trillion, prompting economists to warn about a looming ‘vicious cycle’

Debt and the beggar

The combination of record global debt, higher borrowing costs and growing doubts about the enormous sums being committed to artificial intelligence is creating a more complicated backdrop for financial markets.

Global debt exceeded $365 trillion in the first half of 2026, according to the Institute of International Finance, with debt now around 310% of global GDP.

China and the U.S. debt mountain

The increase was driven particularly by China and the United States. At the same time, higher interest rates are making refinancing increasingly expensive, creating the possibility of a vicious cycle in which governments and companies borrow more simply to service existing obligations.

This is particularly significant for the AI boom. The OECD says governments and companies are expected to borrow around $29 trillion from markets during 2026, while corporate borrowing is also rising as businesses finance major investment programmes, including AI infrastructure.

Michael Burry

Michael Burry, famous for anticipating the U.S. housing crisis, has added another warning sign.

He has recently reportedly increased bearish positions involving Micron, Palantir, Nebius and the semiconductor sector, arguing that parts of the AI and chip boom could be vulnerable if supply increases faster than demand.

The concern is not necessarily that AI will fail. Rather, enormous investment and borrowing require enormous future revenues to justify them.

If AI spending produces lower-than-expected returns, highly valued technology shares could face pressure at the same time as heavily indebted companies face rising financing costs.

Could this affect the stock market now?

The ingredients for greater volatility are certainly present. Higher bond yields, expensive energy, inflation pressures and debt-servicing costs can compete with equities for investors’ money.

Reuters recently reported that global borrowing costs and energy prices were already creating concerns about the potential impact on equities and credit markets.

Yet markets have so far remained remarkably resilient, with U.S. shares still close to record levels.

The danger, therefore, may not be debt alone, but…

debt + high valuations + expensive AI investment + higher interest rates.

If those pressures reinforce one another, the adjustment in markets could become considerably more significant.
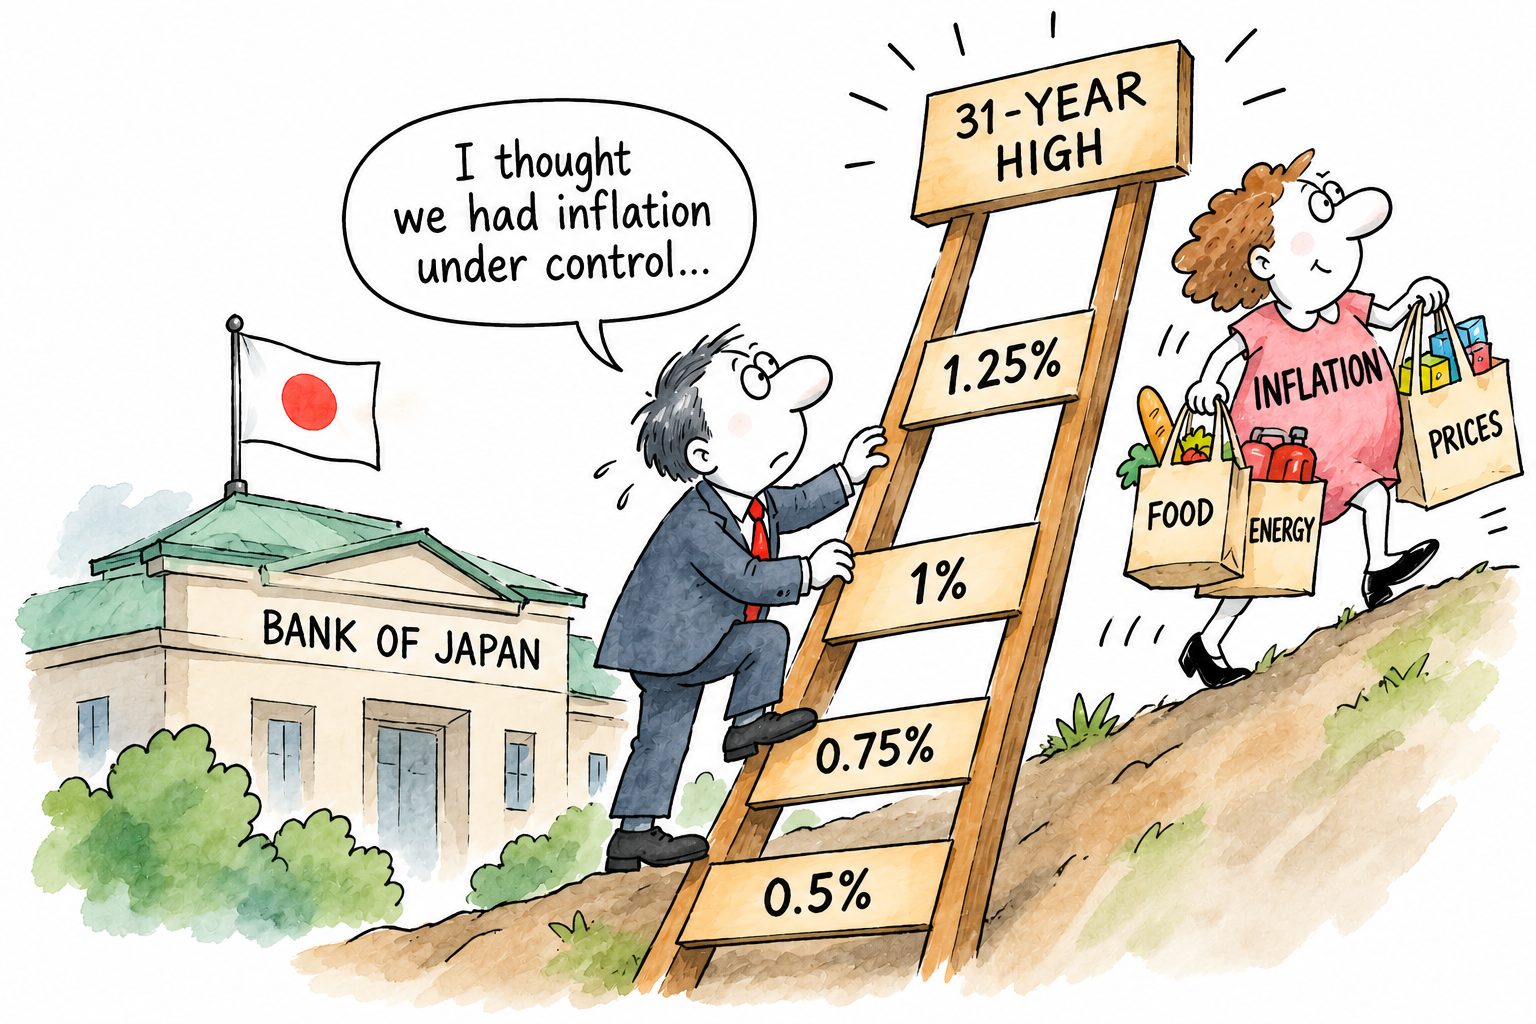
Bank of Japan hikes Interest rate by 0.25% to 1.25%

Japan raises interest rate

The Bank of Japan has raised its benchmark interest rate to 1.25%, its highest level in 31 years, as it steps up efforts to contain inflation.

The quarter-point increase from 1% was approved by a 7-2 vote and had been widely expected by financial markets.

A Familiar story of energy inflation

Governor Kazuo Ueda reportedly said the move reflected growing concerns that inflation could overshoot the Bank’s 2% target.

Higher energy costs, a weaker yen and rising prices linked to strong demand are adding to pressure on the Japanese economy.

The decision marks another step away from Japan’s decades of ultra-low and negative interest rates.

However, two policymakers opposed the increase, highlighting concerns about economic conditions and the pace of further tightening.

The yen weakened following the announcement, as investors assessed how quickly the Bank might raise rates again.

Nikkei 225 Breaks 50,000: A Milestone Fueled by Tech Trade and Policy Optimism

Nikkei at new all-time high!

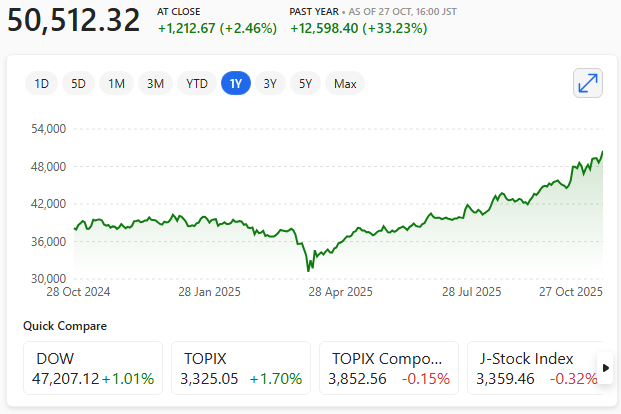
Japan’s benchmark Nikkei 225 index surged past the 50,000 mark for the first time in history, marking a symbolic milestone for Asia’s second-largest economy.

The rally reflects a potent mix of domestic resilience, global investor appetite, and strategic policy shifts that have redefined Japan’s market narrative.

The breakthrough comes amid renewed optimism surrounding U.S.-China trade negotiations, with President Trump signalling progress ahead of a key meeting with Japan’s Sanae Takaichi.

Investors are betting on a thaw in geopolitical tensions, which could unlock export growth for Japan’s tech-heavy industrial base.

Driving the rally are heavyweight stocks in semiconductors, robotics, and AI infrastructure—sectors buoyed by global demand and Japan’s push to become a regional data hub.

Nikkei 225 Index at new history high above 50,000

Companies like Tokyo Electron and SoftBank have seen double-digit gains, fuelled by bullish earnings and strategic pivots toward AI and automation.

Domestically, the Bank of Japan’s continued accommodative stance has kept borrowing costs low, while corporate governance reforms have attracted foreign capital.

The weaker yen has also boosted exporters, making Japanese goods more competitive abroad.

Symbolically, the 50,000 threshold represents more than just market exuberance—it’s a vote of confidence in Japan’s ability to adapt, innovate, and lead in a shifting global landscape.

While risks remain—from demographic headwinds to geopolitical flashpoints—the Nikkei’s ascent signals a new era of investor engagement with Japan’s evolving economic story.

Japan faces steepest export decline in four years

Japan exports drop

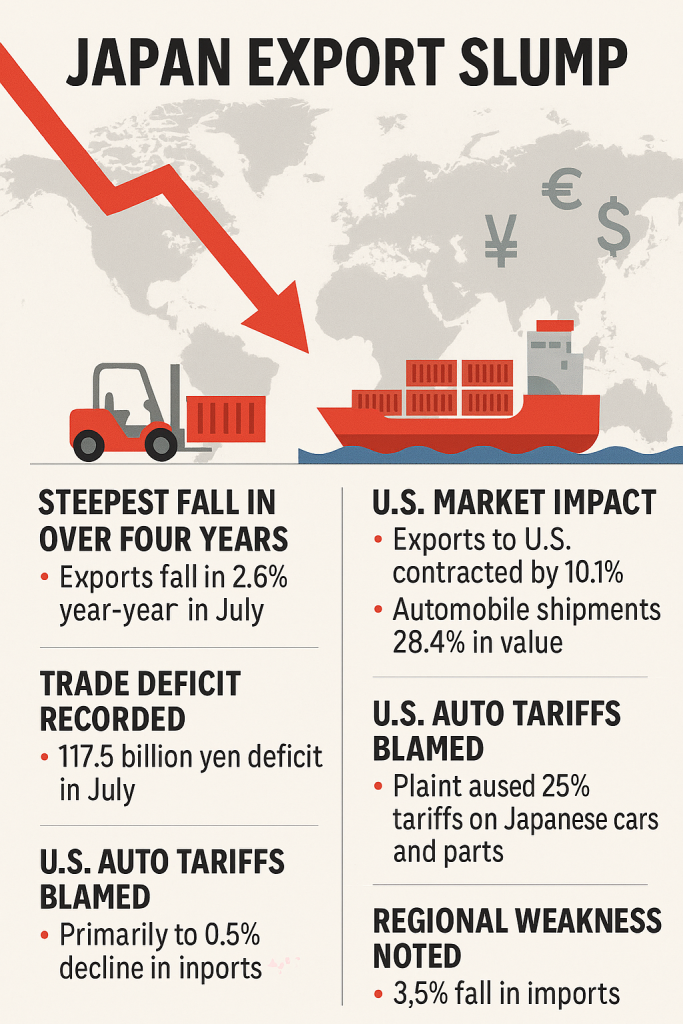
Japan’s economy has hit a troubling patch, with July 2025 marking its sharpest export contraction in over four years.

The Ministry of Finance reported a 2.6% year-on-year drop, driven largely by tariff led trade tensions and weakening global demand.

The most dramatic impact came from the United States, where exports fell 10.1%, led by a 28.4% plunge in automobile shipments.

This follows the U.S. administration’s decision to impose 25% tariffs on Japanese vehicles and auto parts in April—a move that has rattled Japan’s automotive sector, long a pillar of its export economy.

Despite a partial tariff rollback to 15% in July, the damage was already done. Japanese carmakers absorbed much of the cost to maintain shipment volumes, which only fell 3.2%, but the value loss was substantial.

Japan – July export data infographic

Exports to China also declined by 3.5%, underscoring broader regional weakness. Meanwhile, imports dropped 7.5%, signalling sluggish domestic consumption and further strain on Japan’s trade balance, which recorded a 117.5 billion yen deficit.

Economists warn that if the export downturn continues, Japan could face a recession. Although Q2 GDP showed modest growth of 0.3%, the July figures suggest that momentum may be fading.

The Bank of Japan is now expected to hold off on interest rate hikes, with its next policy meeting scheduled for 19th September 2025.

As global markets digest the implications, Japan’s export slump serves as a stark reminder of how vulnerable even advanced economies can be to shifting trade policies and geopolitical headwinds.

Japan rice price spikes by 101% – highest in 50 years and inflation jumps to highest level since 2023

Japan Rice up highest for 50 years

Japan has been jolted by a dramatic spike in rice prices, which surged by 101.7% year-on-year in May 2025 – the most significant increase in over fifty years.

This sharp rise in the cost of the country’s staple food has contributed heavily to Japan’s inflation, which jumped to 3.7%, marking its highest point since January 2023.

The Bank of Japan (BOJ) now faces mounting pressure, as this marks the 38th consecutive month inflation has surpassed the Bank’s 2% target.

Notably, the ‘core-core’ inflation rate, excluding fresh food and energy rose to 3.30%, an indication that broader cost pressures are sticking.

The government has begun releasing emergency rice stockpiles in an attempt to dampen prices, but analysts remain cautious.

With rice accounting for nearly half of Japan’s core inflation, its influence stretches well beyond supermarket aisles. A continued rise could affect everything from packaged goods to restaurant prices.

Despite calls for tightening policy, the BOJ has opted to keep interest rates at 0.5%, citing expectations of inflation easing in the coming months.

However, with geopolitical tensions and supply chain factors still looming, the outlook remains uncertain.

Japan’s core inflation rises to 3.5% – higher than expected

Japan economic data

Japan’s inflation figures for April 2025 have revealed a continued rise in consumer prices, with the Consumer Price Index (CPI) climbing 3.6% year-on-year.

This marks a sustained period of inflation above the Bank of Japan’s (BoJ) target of 2%, prompting speculation about potential interest rate hikes later in the year.

Core inflation, which excludes fresh food, rose 3.5% YoY, exceeding market expectations. A major driver of this surge has been food prices, particularly rice, which has soared by an astonishing 98% compared to last year.

The sharp increase has led the government to release emergency stockpiles to stabilise the market.

The BoJ faces a delicate balancing act. While inflation remains strong, economic uncertainty – partly fueled by U.S. tariffs, could complicate monetary policy decisions. The central bank has already raised rates in recent months but has paused further hikes to assess the broader economic impact.

With inflationary pressures persisting, analysts predict that the BoJ may tighten policy again by October 2025.

Concerns over global trade and domestic economic stability could influence the timing of any further rate adjustments.

The core inflation increase of 3.5% was far higher than expected.

Japan’s inflation up 3% in February 2025 – interest rates expected to rise

Japan inflation

Japan’s core inflation rate rose to 3% in February, exceeding market expectations of 2.9%

This marks the 35th consecutive month that inflation has remained above the Bank of Japan’s 2% target.

While the figure is slightly lower than January’s 3.2%, it reflects persistent price pressures, driven by rising food and wage costs. Government subsidies for fuel helped ease the overall inflation rate to 3.7%, down from January’s 4%.

The Bank of Japan has maintained its interest rate at 0.5%, but the data strengthens the case for potential rate hikes in the coming months as inflationary trends continue to challenge households.

Bank of Japan ends negative rates: a seismic shift in monetary policy

The flag of Japan

In a move that reverberated across global financial markets, the Bank of Japan (BOJ) recently bid farewell to its negative interest rate policy – the last of its kind in the world. This decision marks a pivotal moment in the realm of central banking and has far-reaching implications for economies and investors worldwide.

The Negative Interest Rate Saga

To understand the significance of this shift, let’s rewind the clock. Japan, grappling with deflation for years, embarked on an ambitious economic experiment known as ‘Abenomics’ in 2013. The strategy combined massive government spending with unconventional monetary measures. The BOJ, under the leadership of then-Prime Minister Shinzo Abe, injected liquidity into the system by purchasing bonds and other assets. The goal? Achieve a 2% inflation target and kickstart growth.

Among these measures was the adoption of negative interest rates. The idea was simple: discourage banks from hoarding excess reserves and encourage lending. However, the path to higher inflation proved elusive, and the BOJ found itself navigating uncharted waters.

The Change

Fast forward to 2024. Japan’s economy has experienced a moderate recovery, prompting policymakers to reassess their strategic options. The Bank of Japan (BOJ) has elevated its short-term interest rate from minus 0.1% to a range between zero and 0.1%. This adjustment marks the first increase in rates since 2007, representing a significant, even a ‘seismic’ policy shift.

The Effect

  1. Policy Pivot: The BOJ acknowledges that negative rates have played their part. With improving wages and corporate profits, the time is ripe for a change. The new rate range signals a departure from the era of ultra-accommodative policies.
  2. Global Implications: Japan now stands as the last central bank to exit negative rates. For years, central bankers worldwide wielded cheap money and unconventional tools. Now, the tide turns. The era of negative rates draws to a close, and other central banks take note.
  3. Market Response: Tokyo’s Nikkei 225 index responded positively, gaining 0.7%. The Japanese yen weakened against the dollar. Investors recalibrate their strategies, adjusting to a world where negative rates are no longer the norm. The Nikkei is sitting close to or at its all-time high!

Nikkei 225 3 month chart at: 40003 – close to its recent new all-time high of 40109

Nikkei 225 3 month chart at: 40003 – close to its recent new all-time high of 40109

The future?

As the BOJ takes its first step toward policy normalization, questions abound. Will further rate adjustments follow? How will markets adapt? And what does this mean for global liquidity?

One thing is certain: The decision of the Bank of Japan resonates beyond the confines of the nation. It heralds the beginning of a new era in which central banks adjust their strategies, economies establish stability, and investors once more chart a course through unfamiliar territory.

Within the chronicles of monetary history, the cessation of negative rates at the Bank of Japan will be marked as a pivotal moment. As the final details of this policy transition are solidified, the global community observes, prepared for the forthcoming developments.


Disclaimer: The views expressed in this article do not constitute financial advice. Readers are encouraged to consult professional advisors before making any investment decisions.

Remember to always do your own research

RESEARCH! RESEARCH! RESEARCH!