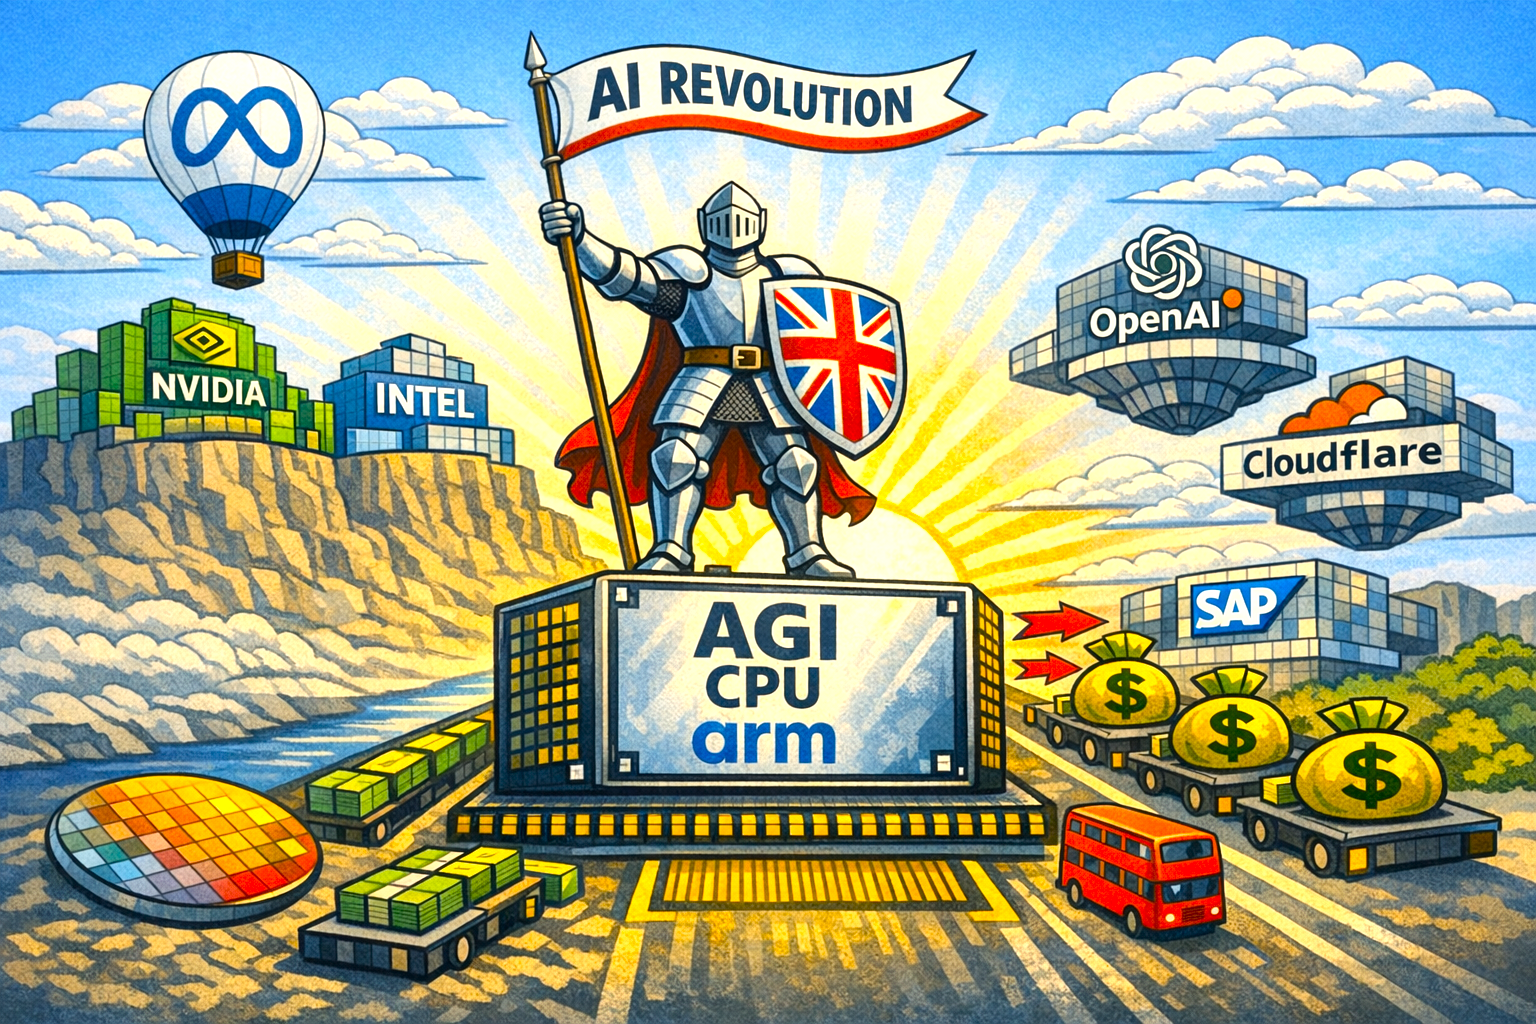
ARM has triggered one of the most dramatic shifts in its 35‑year history with the launch of its first in‑house data‑centre processor, the AGI CPU — a move that sent its shares surging 16% and reshaped expectations for the company’s future.
Long known for licensing energy‑efficient chip designs to the world’s biggest tech firms, ARM is now stepping directly into the silicon market, competing with the very customers that built its empire.
Major Tech Firms Using Arm Designs (AI & Mobile)
Company
Primary Use Case
Arm-Based Technology
Apple
Mobile & on‑device AI
A‑series (iPhone/iPad) and M‑series (Mac) chips
Samsung
Mobile, AI, IoT
Exynos processors
Qualcomm
Mobile & automotive AI
Snapdragon SoCs
Google
Android ecosystem & edge AI
Pixel phones (Arm cores inside Tensor chips)
Amazon (AWS)
Cloud compute & AI inference
Graviton & Trainium/Inferentia (Arm Neoverse)
Meta
AI infrastructure
Deploying Arm-based AGI CPU
OpenAI
AI inference & orchestration
Early adopter of Arm AGI CPU
Nvidia
AI data‑centre CPUs
Grace CPU (Arm architecture)
OPPO
Mobile AI
Arm-based SoCs in Find series
vivo
Mobile AI
Arm-based SoCs in X‑series
Strong demand
The new AGI CPU is engineered for the rapidly expanding world of AI inference and agentic AI — workloads that demand vast CPU coordination rather than pure GPU horsepower.
Early demand appears strong. Meta has signed on as the first major customer, with OpenAI, Cloudflare and SAP also adopting the chip as they race to expand their AI infrastructure.
The financial implications are striking. ARM expects the AGI CPU alone to generate $15 billion in annual revenue by 2031, a figure that dwarfs the company’s 2025 revenue of $4 billion.
Significant shift
Analysts have described the announcement as the most significant strategic shift ARM has ever undertaken, noting that the revenue projections exceed even the most optimistic market estimates.
By moving into full chip production, ARM is broadening its market to include companies that previously had no interest in its traditional IP‑licensing model.
Executives say the chip will be competitively priced, offering an alternative for firms unable to build their own custom silicon.
For the UK, the launch marks a rare moment of industrial ambition in a sector dominated by American and Asian giants.
If ARM’s forecasts hold, the AGI CPU could become one of the most commercially successful chips ever produced by a British company — and a defining pillar of the AI age.
Financial markets are no strangers to volatility, but even seasoned traders were taken aback by the extraordinary price action that unfolded recently.
Just a minute
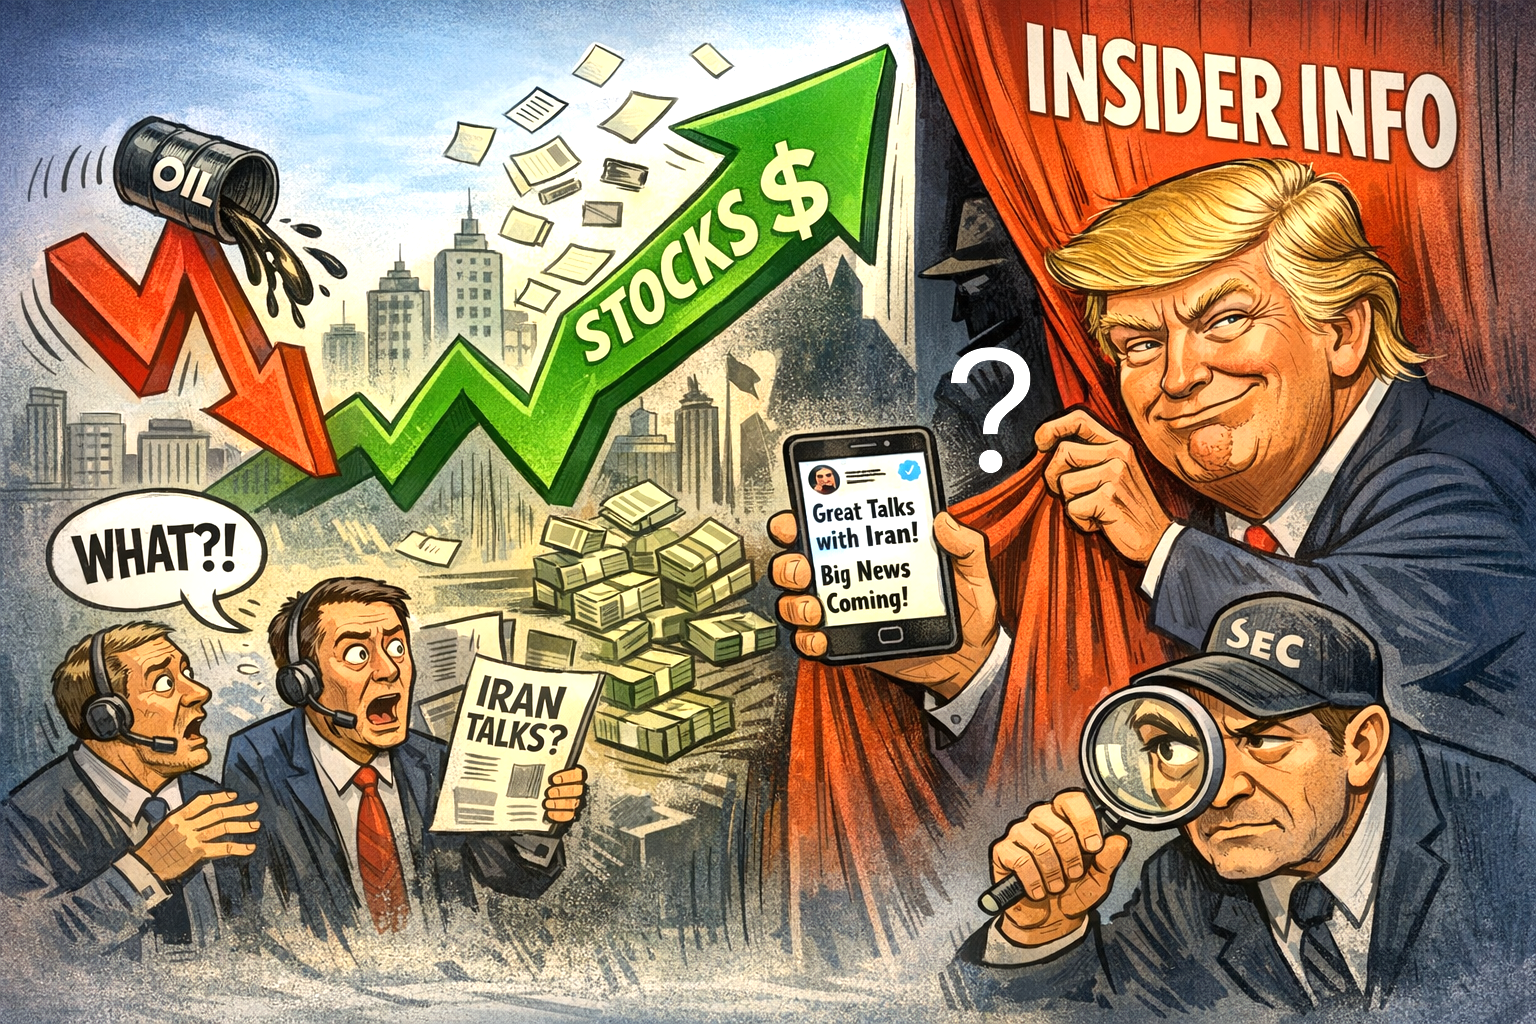
In the space of minutes, global indices lurched upwards, oil prices collapsed, and billions of dollars shifted across the financial system — all triggered by a single, unexpected announcement from President Trump claiming “productive talks” with Iran.
What followed was a whiplash-inducing reversal, a diplomatic denial from Tehran, and a growing chorus of questions about whether the market’s initial leap was quite as spontaneous as it appeared.
Spike
The sequence of events is now well documented. In the quiet pre‑market hours, trading volumes in S&P 500 futures and crude oil contracts suddenly spiked.
These were not the tentative probes of retail traders or the routine adjustments of algorithmic systems. They were large, directional, and unusually well‑timed.
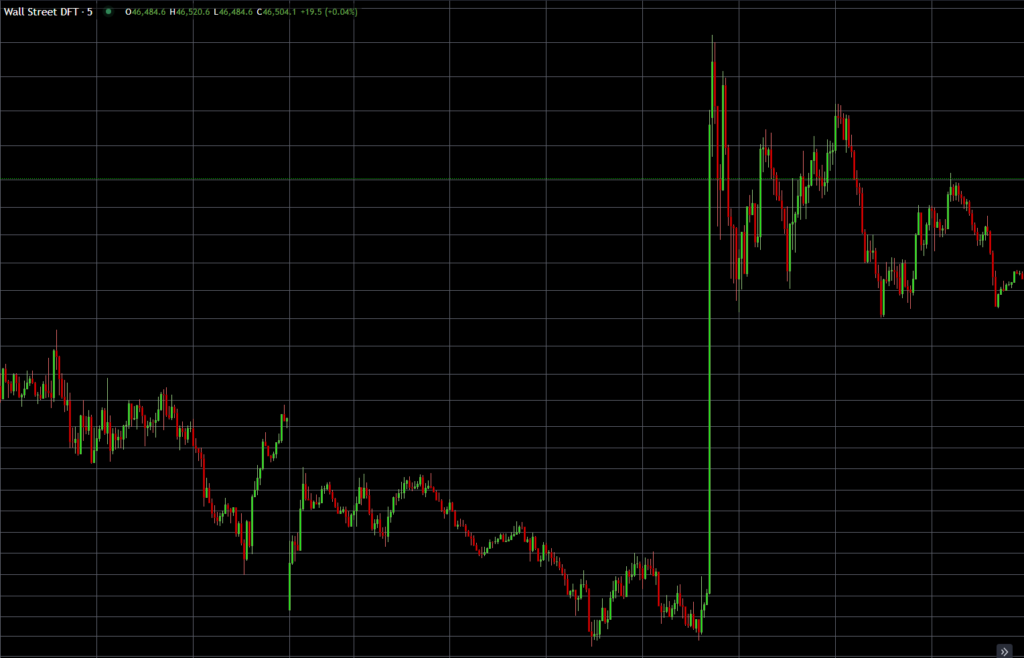
Snapshot of Wall Street DFT (Dow Jones Industrial Average) demonstrating the spike in question
Minutes later, Trump posted his statement about progress with Iran — a geopolitical development with obvious implications for equities and energy markets.
Instant
Prices reacted instantly. Equities surged. Oil tumbled. Within the hour, Iran publicly denied that any such talks had taken place, prompting a partial reversal of the earlier moves. Maybe we should draw a distinction between ‘talks’ and ‘messages’.
It is the precision of the trades placed before the announcement that has raised eyebrows. Markets do not move in anticipation of news that does not exist in the public domain.
Yet someone, somewhere, positioned themselves perfectly for the impact of Trump’s message posted on social media.
Fortuitous coincidence or deliberate manipulation?
Scale
The scale of the trades suggests institutional capability; the timing suggests foreknowledge. Whether that foreknowledge was legitimate, accidental, or illicit is now the central question.
Speculation about insider trading is inevitable in such circumstances, but it is important to distinguish between suspicion and proof. Political announcements are not governed by the same disclosure rules that apply to corporate earnings or mergers.
Presidents are not bound by quiet periods. Their advisers, however, are. So are the staff, intermediaries, and diplomatic channels through which sensitive information flows.
Obligation to investigate
If anyone in that chain traded — or tipped off someone who did — regulators will be obliged to investigate.
There is also a broader concern about the integrity of market‑moving communication. If Iran’s denial is accurate, and no talks occurred, then the market reacted to a statement that may not have reflected reality.
Even without malicious intent, such episodes undermine confidence in the informational foundations on which markets depend. When a single message can add or erase trillions in value, the accuracy and reliability of that message become matters of systemic importance.
Suspicion
For now, the episode sits in an ambiguous space: suspicious, but unproven; dramatic, but not unprecedented. Markets will move on, as they always do.
Yet the questions raised yesterday will linger — about transparency, about the porous boundaries between politics and finance, and about the unseen hands that sometimes seem to move just a little too quickly.
Does the idea that Trump ‘massages’ the market carry any weight?
It’s a fair question, and one that keeps resurfacing because the pattern is hard to ignore.
The idea that Trump “massages” the markets isn’t a conspiracy theory in itself — it’s an observation that his public statements often have immediate, dramatic financial consequences.
The real issue is whether those consequences are accidental, strategic, or exploited by people with advance knowledge.
Agentic AI is rapidly shifting from a speculative idea to a practical force reshaping how work gets done.
Unlike traditional AI systems, which wait passively for instructions, agentic AI can plan, act, and adapt within defined boundaries.
It is not simply a smarter chatbot; it is a system capable of taking initiative, coordinating tasks, and pursuing goals on behalf of its user.
This evolution marks a profound turning point in how we think about automation, creativity, and human–machine collaboration.
Agentic AI colleagues
The first major change is the move from reaction to autonomy. Today’s AI assistants excel at answering questions or generating content, but they still rely on constant prompting.
Agentic AI, by contrast, can break down a complex objective into smaller steps, choose the best tools for each stage, and execute them with minimal oversight. This transforms AI from a passive helper into an active collaborator.
For individuals and small teams, it promises a level of operational leverage previously reserved for large organisations with dedicated staff.
A second shift lies in the emergence of multi‑modal competence. Agentic systems will not be confined to text. They will navigate interfaces, analyse documents, draft communications, and even orchestrate workflows across multiple platforms.
In effect, they will behave more like digital colleagues—capable of understanding context, maintaining continuity, and adapting to changing priorities. The result is a new category of labour: cognitive automation that complements rather than replaces human judgement.
However, the rise of agentic AI also raises important questions. Autonomy introduces risk. If an AI can take action, it must do so safely, transparently, and within clear constraints.
On guard
Guardrails will be essential—not only technical safeguards, but also cultural norms around delegation, accountability, and trust. The future will require a balance between empowering AI to act and ensuring humans remain firmly in control of outcomes.
Another challenge is the shifting nature of expertise. As agentic AI handles more administrative and procedural work, human value will increasingly lie in strategic thinking, creativity, and ethical decision‑making.
This is not a loss but a rebalancing. Freed from routine tasks, people can focus on higher‑order work that genuinely benefits from human insight.
The organisations that thrive will be those that treat AI not as a shortcut, but as a catalyst for deeper, more meaningful contribution.
Future use of agents
Looking ahead, the most exciting aspect of agentic AI is its potential to democratise capability. A single individual could run a publication, a business, or a research project with the operational efficiency of a small team.
Barriers to entry will fall. Innovation will accelerate. And the line between “solo creator” and “organisation” will blur.
Agentic AI is not the end of human agency; it is an extension of it. The future belongs to those who learn to work with these systems—setting direction, providing judgement, and letting AI handle some of the heavy lifting.
Far from replacing us, agentic AI may finally give us the space to think, create, and lead with clarity.
OpenClaw has rapidly become one of the most influential developments in artificial intelligence, evolving from a small open‑source experiment into a global phenomenon reshaping how people interact with computers.
Launched in January 2026, the platform allows users to run autonomous AI agents locally on their own machines, giving them the power to organise files, write code, browse the web, and automate everyday digital tasks without relying on cloud services.
This local‑first design has been central to its explosive growth — and to the concerns now emerging around it.
One of the most striking cultural shifts has taken place in China, where OpenClaw has become a mainstream sensation.
AI Lobsters
Users refer to their agents as “AI lobsters,” a playful nod to the platform’s crustacean branding. Retirees, students, and professionals alike have begun “raising” these lobsters to help manage knowledge, streamline work, and perform practical tasks that traditional chatbots struggle with.
The trend has grown so quickly that crowds have gathered outside major tech offices in Beijing to install the software together, turning OpenClaw into a genuine grassroots movement.
This surge in popularity has also caught the attention of global markets. Chinese AI‑related stocks have risen sharply following comments from Nvidia CEO Jensen Huang, who described OpenClaw as “the next ChatGPT,” signalling its potential to redefine the agentic AI landscape.
Security
Companies building self‑evolving agents and cloud infrastructure around OpenClaw have seen double‑digit gains as investors position themselves for what appears to be the next major AI wave.
Yet OpenClaw’s power has also raised red flags. Because the agent runs locally and can control a user’s computer, enterprise IT teams have struggled to manage the security implications.
The platform’s ability to act autonomously — reading files, sending messages, and interacting with applications — has created a need for stronger guardrails, especially in corporate environments.
Nvidia’s NemoClaw
Nvidia has stepped in with NemoClaw, a new enterprise‑grade stack that adds privacy controls, security infrastructure, and vetted local models to OpenClaw through a single‑command installation.
The goal is to make autonomous agents more trustworthy and scalable without undermining the open‑source ethos that made OpenClaw successful.
OpenClaw’s own development continues at pace. The latest stable release, v2026.3.13, includes fixes for session handling, improved browser‑control mechanisms, and a shift away from legacy Chrome extensions towards direct attachment to existing browser sessions — a move designed to make agent operations safer and more reliable.
The future
In just a few months, OpenClaw has transformed from a niche project into a global force, driving cultural trends, market movements, and enterprise innovation.
Its trajectory suggests that autonomous, locally run agents may soon become a standard part of everyday computing — and the race to shape that future has only just begun.
Gold and silver prices have come under renewed pressure this week as a broad commodities sell‑off gathers pace, driven by a resurgence in global inflation concerns.
After months of steady gains, both metals have slipped sharply, catching out investors who had positioned for a more defensive environment.
The trigger has been a run of hotter‑than‑expected inflation readings across major economies, prompting traders to reassess the likelihood of interest rate cuts this year.
With central banks now signalling caution, yields have pushed higher, undermining the appeal of non‑yielding assets such as gold and silver.
The shift has been swift: spot gold has retreated from recent highs, while silver — typically more volatile — has fallen even harder as speculative positions unwind.
Market strategists note that the sell‑off is less about fundamentals and more about positioning.
Hedge
Gold’s long‑standing role as an inflation hedge remains intact, but in the short term, rising real yields tend to dominate sentiment.
Silver, meanwhile, sits awkwardly between its status as a precious metal and its industrial uses, leaving it exposed when growth expectations wobble.
Despite the pullback, some analysts argue the move may prove temporary. Persistent geopolitical tensions, ongoing currency instability, and the sheer scale of global debt continue to provide a supportive backdrop for safe‑haven assets.
But for now, traders appear focused on the near‑term path of inflation and interest rates — and that means precious metals remain vulnerable to further swings.
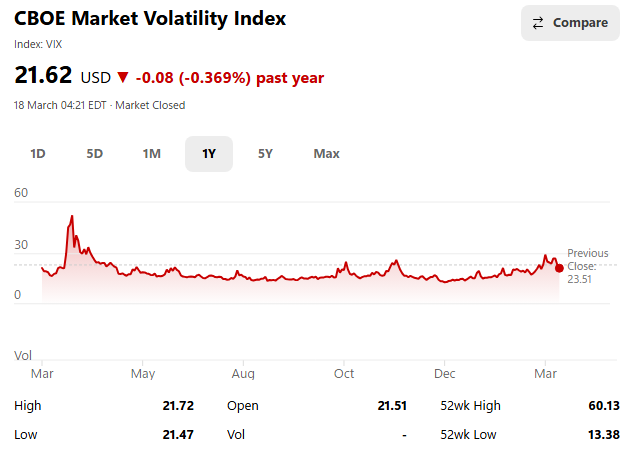
The VIX index currently (18th March 2026 – 8:30GMT) at 21.62, down around 8% from its previous close of 23.51. This drop suggests a modest easing in market fear, despite looming catalysts like the Fed decision and geopolitical tension.
VIX Snapshot – 18th March 2026
Metric
Value
Current Price
21.62 USD
Previous Close
23.51 USD
Day Change
−1.89 Down 8%
Intraday High/Low
21.72 / 21.47
52-Week High/Low
60.13 / 13.38
One-year market volatility index snapshot image 18th March 2026 at approx: 08:30 GMT
Implications
Still Elevated: A VIX above 20 suggests lingering unease, even if not full-blown panic.
Compression Context: This aligns with your “coiled spring” thesis — volatility is contained but not absent.
Directional Bias: If VIX continues to fall post-Fed, it supports a bullish breakout. A spike, however, would signal risk-off sentiment and potential sell-off.
Markets rarely sit still without reason. When they do — as they have in recent sessions, grinding sideways in an ultra‑tight range — it signals not calm but compression.
Price action becomes like a coiled spring: energy building, tension rising, and traders waiting for the moment when restraint snaps into motion.
This week’s narrow trading bands reflect a market holding its breath. Geopolitical tension in the Middle East, oil volatility, and a Federal Reserve decision all loom over investors, yet equities have refused to break down.
Futures are edging higher, European indices are opening firmer, and even the tech wobble — with Nvidia’s muted reaction to its latest showcase — hasn’t derailed broader sentiment
Tight range – a waiting game.
Historically, such tight ranges rarely resolve with a whimper. When volatility is suppressed for too long, the eventual breakout tends to be sharp and directional. The question, of course, is which way.
Right now, the evidence suggests upward. Markets have absorbed war‑driven oil swings, shrugged off hedge‑fund losses, and continued to find buyers on dips.
Breadth is stabilising, and risk appetite — surprisingly resilient given the backdrop — is creeping back into European and Asian sessions.
That doesn’t guarantee a bullish surge, but it does suggest the path of least resistance is higher.
Fed tone
If the Fed avoids surprising investors and signals comfort with the current trajectory, the spring is more likely to uncoil to the upside.
A dovish‑leaning tone could ignite a breakout as sidelined capital rushes back into equities. Conversely, a hawkish shock would release the same stored energy — but violently downward.
The market is coiled. The catalyst is imminent. And when the range finally breaks, it won’t be subtle.
You know, it almost doesn’t matter what disasters are ongoing in the world – the stock market just wants to win and go up!
Just how bad does it have to be before the stock market corrects? And what will be the catalyst to make that happen?
Debt, credit concerns, geopolitical tension, political scandal, Epstein, a rogue nuclear attack, AI failure, war or just another Trump tariff scenario?
Who knows? And does anybody really care as long as ‘making money’ isn’t interrupted.
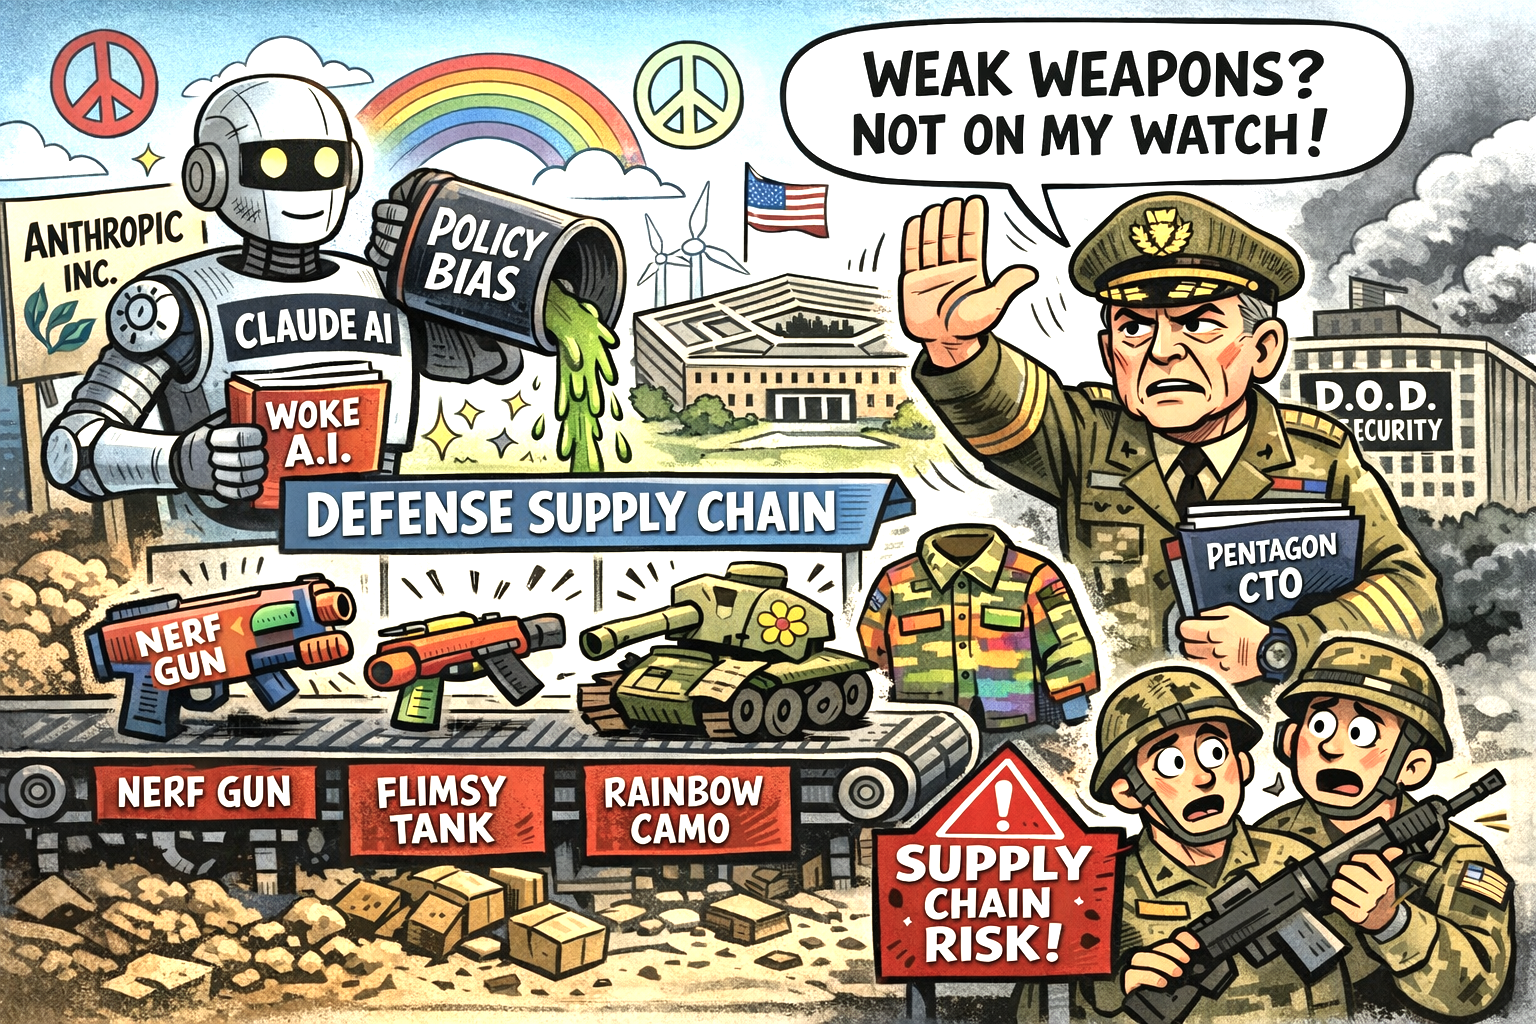
The Pentagon’s Chief Technology Officer, Emil Michael, has apparently ignited a fresh debate over the role of commercial artificial intelligence in national security, arguing that Anthropic’s Claude models could “pollute” the U.S. defence supply chain.
I notice his comments came in an interview with CNBC, offer the clearest rationale yet for the Department of Defense’s decision to designate Anthropic as a supply chain risk — an extraordinary step previously reserved for foreign adversaries.
It seems the opinion is that Claude’s “policy preferences”, embedded through Anthropic’s constitutional training approach, create an unacceptable misalignment with the Pentagon’s operational needs.
Risk
It was reported that any AI system whose underlying values diverge from defence priorities risks producing ineffective outputs, whether in decision‑support tools, equipment design, or battlefield logistics.
“We can’t have a company that has a different policy preference baked into the model… pollute the supply chain so our warfighters are getting ineffective weapons [and] ineffective protection,” he was reported to have said.
Anthropic has responded forcefully, suing the Trump administration and calling the designation “unprecedented and unlawful”.
The company argues that the move jeopardises hundreds of millions of dollars in contracts and mischaracterises the nature of its technology.
Claude in the ecosystem?
It also notes that Claude continues to be used within parts of the U.S. military ecosystem, including by major defence contractors such as Palantir, underscoring the practical difficulty of an immediate transition away from its models.
Michael insists the decision is not punitive and emphasises that only a small fraction of Anthropic’s business comes from government work.
Nonetheless, the designation forces contractors to certify they are not using Claude in Pentagon‑related projects, setting up a potentially lengthy and politically charged dispute over how value‑aligned AI must be before it is allowed anywhere near defence infrastructure.
The episode highlights a broader tension: as AI systems become more opinionated by design, governments are increasingly asking whether “alignment” is a technical question — or a geopolitical one.
For years we’ve clung to the comforting fiction that financial markets are rational machines. Prices rise and fall based on fundamentals, investors weigh risks carefully, and governments act as steady hands guiding the system through uncertainty.
It’s a pleasant story — and almost entirely untrue. Modern markets no longer behave sensibly because the people and structures shaping them no longer behave sensibly either.
Instead, we’ve built a hyper‑reactive ecosystem that rewards drama, amplifies noise, and punishes patience. The 24-hour mind numbing rolling news media frenzy helps feed the ‘stupid’ stock market indifference.
The result is a marketplace that convulses on command. A single line in a political speech can send oil and equities plunging, equities soaring, and futures whipsawing before most people have even digested the words.
This isn’t forward‑looking behaviour. It’s a system addicted to the ‘dollar’ adrenaline.
A Market Built on Complexity, Not Clarity
The first step in understanding today’s dysfunction is recognising just how complicated markets have become. The old world of human traders weighing company quality and long‑term prospects has been replaced by a tangled web of:
algorithmic trading systems scanning headlines for emotional triggers
derivatives hedging flows that move the underlying market
passive investment vehicles pushing money in and out mechanically
central bank signalling that distorts risk pricing
geopolitical noise that algorithms treat as gospel
Each layer adds speed, leverage, and opacity. None of it adds stability.
When markets were simpler, they could afford to be sensible. Today, they are too complex to behave rationally even if they wanted to.
The Incentives Are All Wrong
If you want to understand why markets behave badly, follow the incentives.
Traders are rewarded for short‑term performance, not long‑term judgement. Fund managers fear underperforming their peers more than they fear being wrong.
Algorithms are rewarded for speed, not context. Politicians are rewarded for drama, not restraint. News outlets are rewarded for shock and sensation, not nuance.
A comment or speech fed through central banker infiltrates opinion and moves the markets. It’s irrational behaviour – because it is now ingrained and expected!
In such an environment, knee‑jerk reactions aren’t a flaw — they’re the logical outcome of the system’s design.
A calm, measured response to geopolitical tension doesn’t generate clicks, flows, or political capital. A dramatic statement, however, can move billions in minutes. And some actors know this.
And we have blindly accepted this. One of the most uncomfortable truths about modern markets is that drama is profitable for certain players.
Volatility traders thrive on big swings. High‑frequency firms thrive on rapid order flow. Media outlets thrive on sensational headlines. Political figures thrive on attention. Algorithms thrive on sharp, binary signals. Not a constructive mix.
A calm market is good for society. A dramatic market is good for business.
So we’ve normalised the abnormal. Markets now move on:
rumours
tone
misinterpreted headlines
algorithmic overreactions
political theatre
hedging flows
central bank adjectives
This isn’t price discovery. It’s noise discovery.
We Could Have Chosen a Different Path
Here’s the part that stings: none of this was inevitable.
If governments communicated with clarity and restraint, markets would be calmer. If market makers prioritised liquidity and stability over speed, volatility would fall.
If traders were rewarded for long‑term thinking, the system would breathe more slowly. If algorithms were designed to interpret context rather than react to keywords, markets would behave more like markets and less like mindless sheep following a lost leader.
But we didn’t choose that path. We chose complexity, speed, and drama — and now we live with the consequences.
A System Too Complicated to Behave Sensibly
The modern market is not a rational judge of value. It is a behavioural ecosystem shaped by incentives, emotion, and structural institutional distortions.
It reacts to tone. It can price uncertainty, not fundamentals. It amplifies drama, not discipline.
When a single political sentence can move global markets, the problem isn’t the sentence. It’s the system that reacts to it.
Markets haven’t lost their minds. We’ve simply built a marketplace too complicated — and too dramatic — to act as if it still has one.
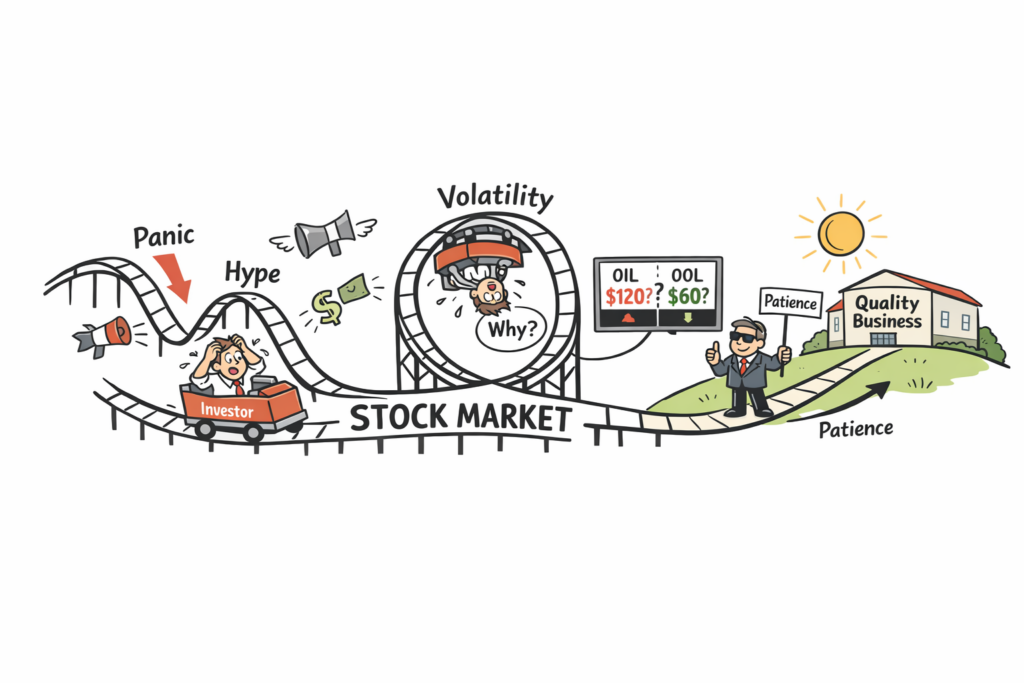
Fortunately, at least a good quality business can still provide a good quality return – but we all have to ride the stupid stock market roller-coaster to get there!
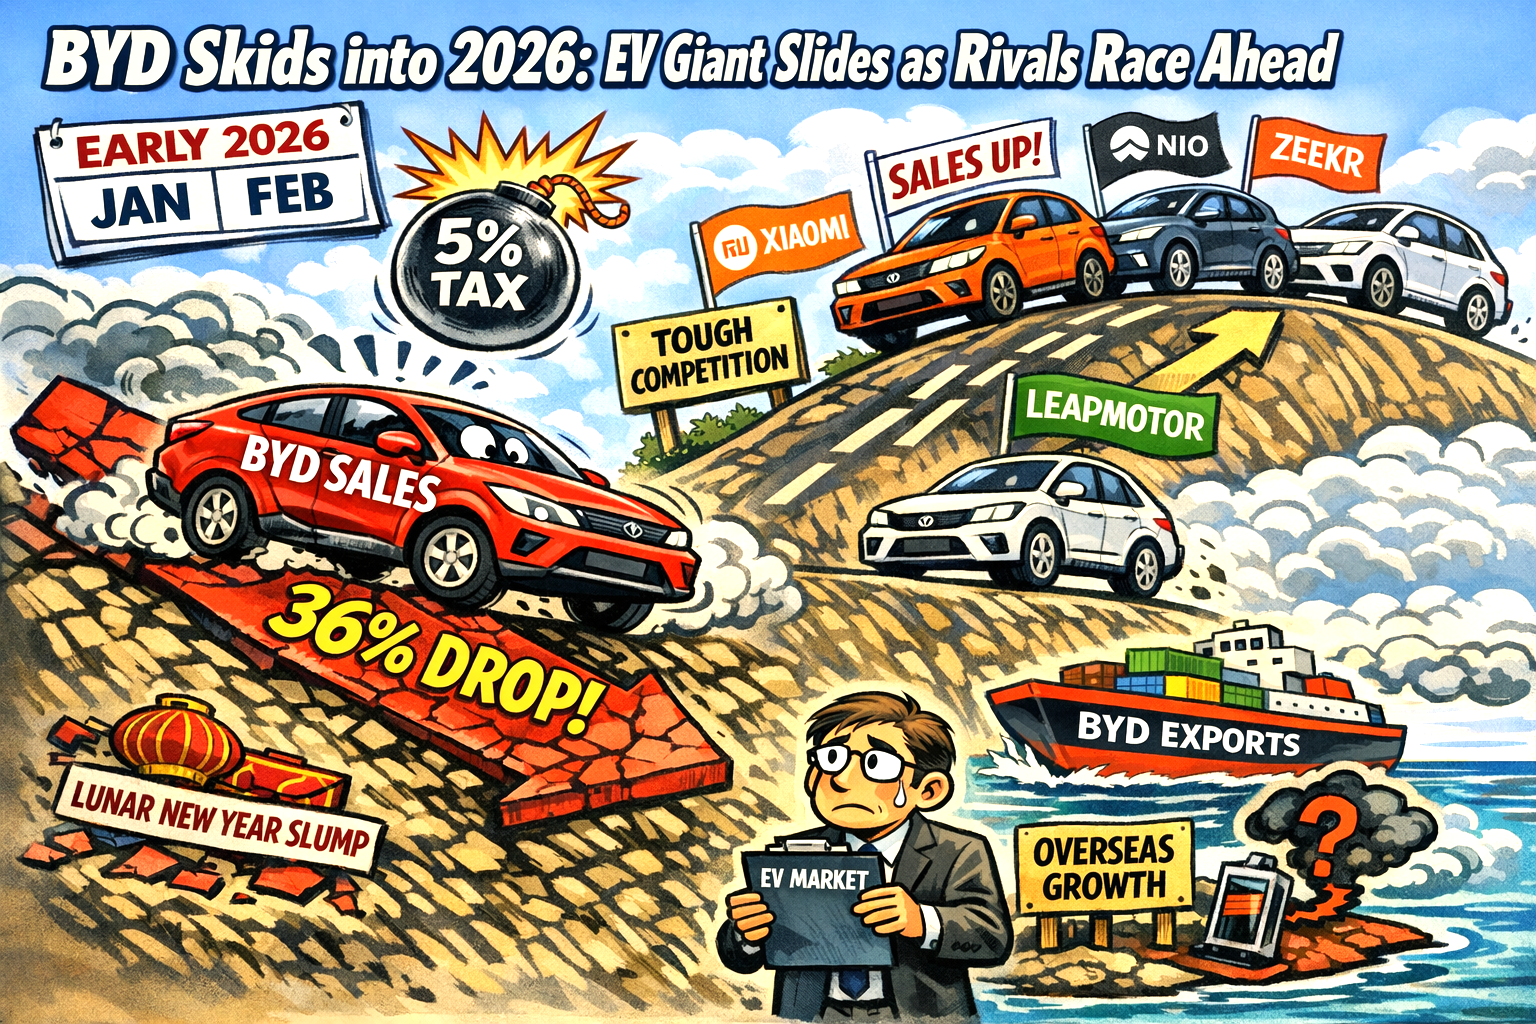
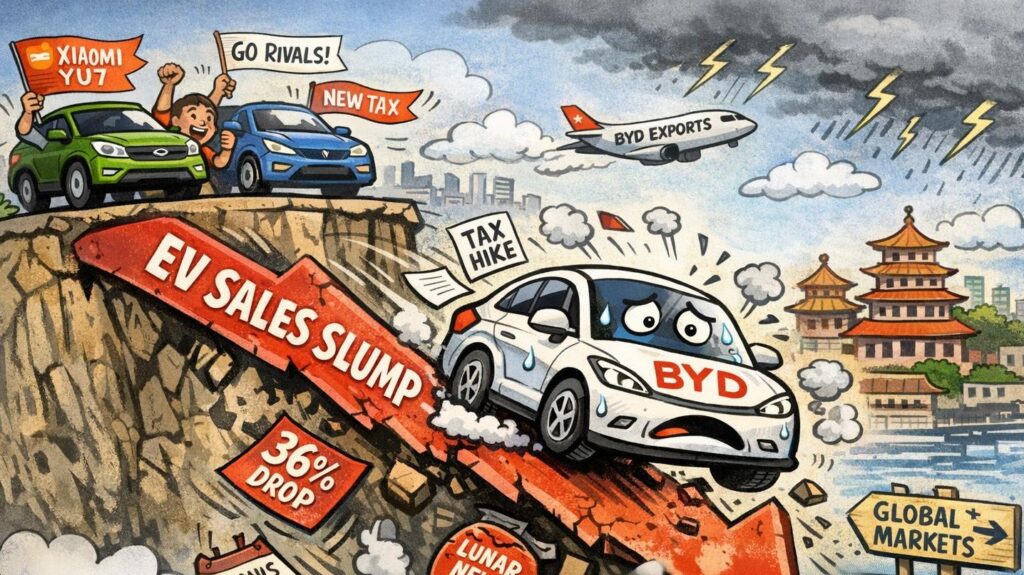
BYD’s sharp fall in electric‑vehicle sales across January and February 2026 marks a significant moment for the world’s largest EV maker, signalling both cyclical pressures and a deeper shift in China’s hyper‑competitive market.
Adjusted for the disruption caused by the mid‑February Lunar New Year holiday, BYD’s combined sales for the first two months of the year were down roughly 36% year on year, a rare contraction for a company that has spent the past three years dominating China’s new‑energy vehicle segment.
Slump
Several forces converged to produce the slump. The reinstatement of a 5% purchase tax on new‑energy vehicles at the end of 2025 pulled demand forward, leaving a vacuum in early 2026 as buyers rushed to complete purchases before the levy returned.
At the same time, China’s EV market is maturing, with consumers becoming more discerning and competitors far more aggressive.
Xiaomi, Leapmotor, Nio and Geely’s Zeekr all posted strong double‑digit growth over the same period, with Xiaomi’s YU7 SUV even becoming China’s best‑selling passenger vehicle in January.
This intensifying competition reflects a broader levelling of the playing field. Rivals are increasingly attacking BYD’s core mid‑market territory by packing more features into vehicles while keeping prices tight — a trend known locally as involution.
Leading still
Analysts note that while BYD’s lead remains substantial, it is narrowing as alternatives become more compelling.
Yet the picture is not uniformly negative. BYD’s strategic pivot towards overseas markets is beginning to pay off: in February 2026, its exports surpassed domestic sales for the first time, underscoring the company’s growing global footprint and providing a buffer against domestic volatility.
Later in 2026, BYD is expected to launch new models featuring its next‑generation Blade Battery 2.0 and faster flash‑charging technology — innovations that could help reignite domestic demand without resorting to a price war.
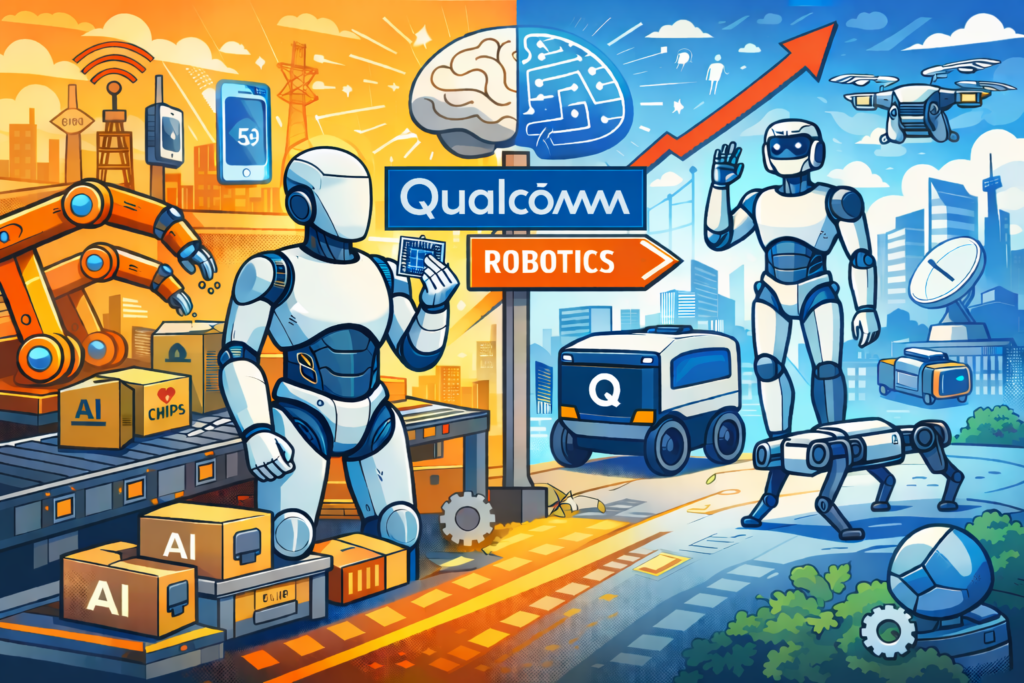
Qualcomm is accelerating its push into artificial intelligence and robotics, signalling a strategic shift that could redefine the company’s future beyond smartphones.
Executives now describe robotics as a core growth pillar, with chief executive Cristiano Amon reportedly forecasting that intelligent machines will become a “larger opportunity” for the business within the next two years.
Expanding from Mobile Chips to Physical AI
For decades, Qualcomm’s dominance has rested on its mobile processors, which power much of the global smartphone market.
The company is now repurposing that expertise for what it calls physical AI—robots capable of perceiving, reasoning, and acting autonomously in real‑world environments.
This transition reflects a broader industry trend: as generative AI matures, attention is shifting from digital assistants to embodied systems that can perform physical tasks.
Qualcomm’s new robotics architecture, unveiled recently, is designed as a full‑stack platform. It combines high‑efficiency system‑on‑chips, safety‑certified compute modules, and advanced on‑device AI models.
The aim is to give robot manufacturers a scalable foundation, whether they are building compact consumer devices or full‑size humanoids for industrial use.
Dragonwing Becomes the Flagship
At the centre of this strategy is the Dragonwing line of processors. The latest model, the Dragonwing IQ10, targets industrial automation and advanced humanoid robots.
It has reportedly been engineered to run complex AI models locally, reducing reliance on cloud connectivity and improving safety, responsiveness, and energy efficiency.
Qualcomm showcased these capabilities at recent industry events, where robots powered by Dragonwing chips demonstrated dexterity, mobility, and real‑time decision‑making.
The company’s ambition places it in direct competition with Nvidia, which currently dominates AI compute for robotics, and with a growing cohort of start‑ups building specialised hardware for autonomous machines.
Why Robotics Matters Now
Three factors underpin Qualcomm’s renewed focus
Diversifying revenue as smartphone markets plateau and competition intensifies.
Leveraging its edge‑AI strengths, particularly in low‑power, high‑performance chips suited to mobile robots.
Rising industrial demand, with logistics, retail, and manufacturing sectors adopting automation at scale.
The robotics push also complements Qualcomm’s automotive and PC AI strategies, creating a broader ecosystem of connected, intelligent devices.
A Critical Two Years Ahead
Qualcomm’s challenge now is to convert impressive demonstrations into commercial deployments.
If successful, the company could become a foundational supplier for the emerging era of physical AI—an era in which robots move from novelty to necessity.
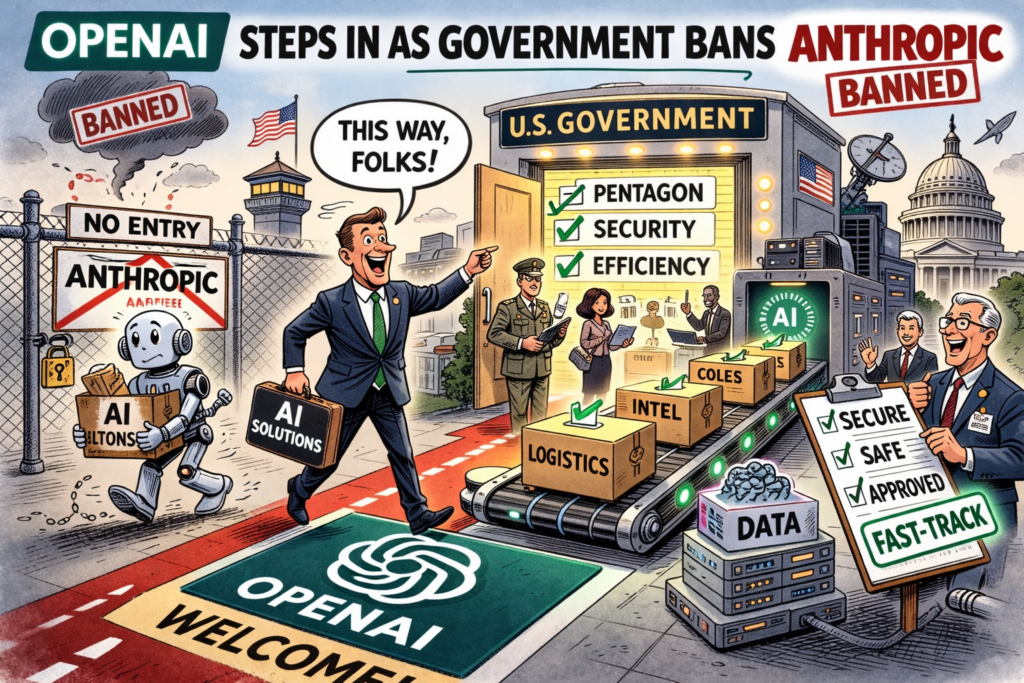
Following the abrupt federal ban on Anthropic’s Claude models, OpenAI has moved quickly to position itself as the primary replacement across U.S. government departments.
With Claude now designated a supply‑chain risk, agencies are likely scrambling to reconfigure AI workflows — and OpenAI’s systems appear to be emerging as the default alternative.
Integration
The company’s flagship GPT‑4.5 and its agentic development tools have reportedly already been integrated into several defence and civilian systems, according to some observers.
OpenAI’s reported longstanding compatibility with government‑approved platforms, including Azure and OpenRouter, has smoothed the transition. Unlike Anthropic, OpenAI has historically offered more flexible deployment options.
Industry analysts note that OpenAI’s recent hires — including agentic systems pioneer Peter Steinberger (OpenClaw) — signal a deeper push into autonomous task execution, a capability highly prized by defence and intelligence agencies.
The company’s agent frameworks are being trialled for logistics, simulation, and multilingual analysis, with early results described as “mission‑ready.”
Friction
However, the shift is not without friction. It has been reported that some federal teams have built Claude‑specific workflows, particularly in legal, policy, and ethics‑driven domains where Anthropic’s safety constraints were seen as a feature, not a limitation.
Replacing those systems with GPT‑based models requires careful recalibration to avoid unintended consequences.
OpenAI’s rise also raises broader questions about vendor concentration. With Anthropic sidelined and Google’s Gemini models still undergoing federal evaluation – OpenAI now dominates the landscape — a position that may invite scrutiny from oversight bodies concerned about resilience and competition.
Still, for now, OpenAI appears to be the primary beneficiary of the Claude ban. In the vacuum left by Anthropic, OpenAI will be attempting to fill the space.
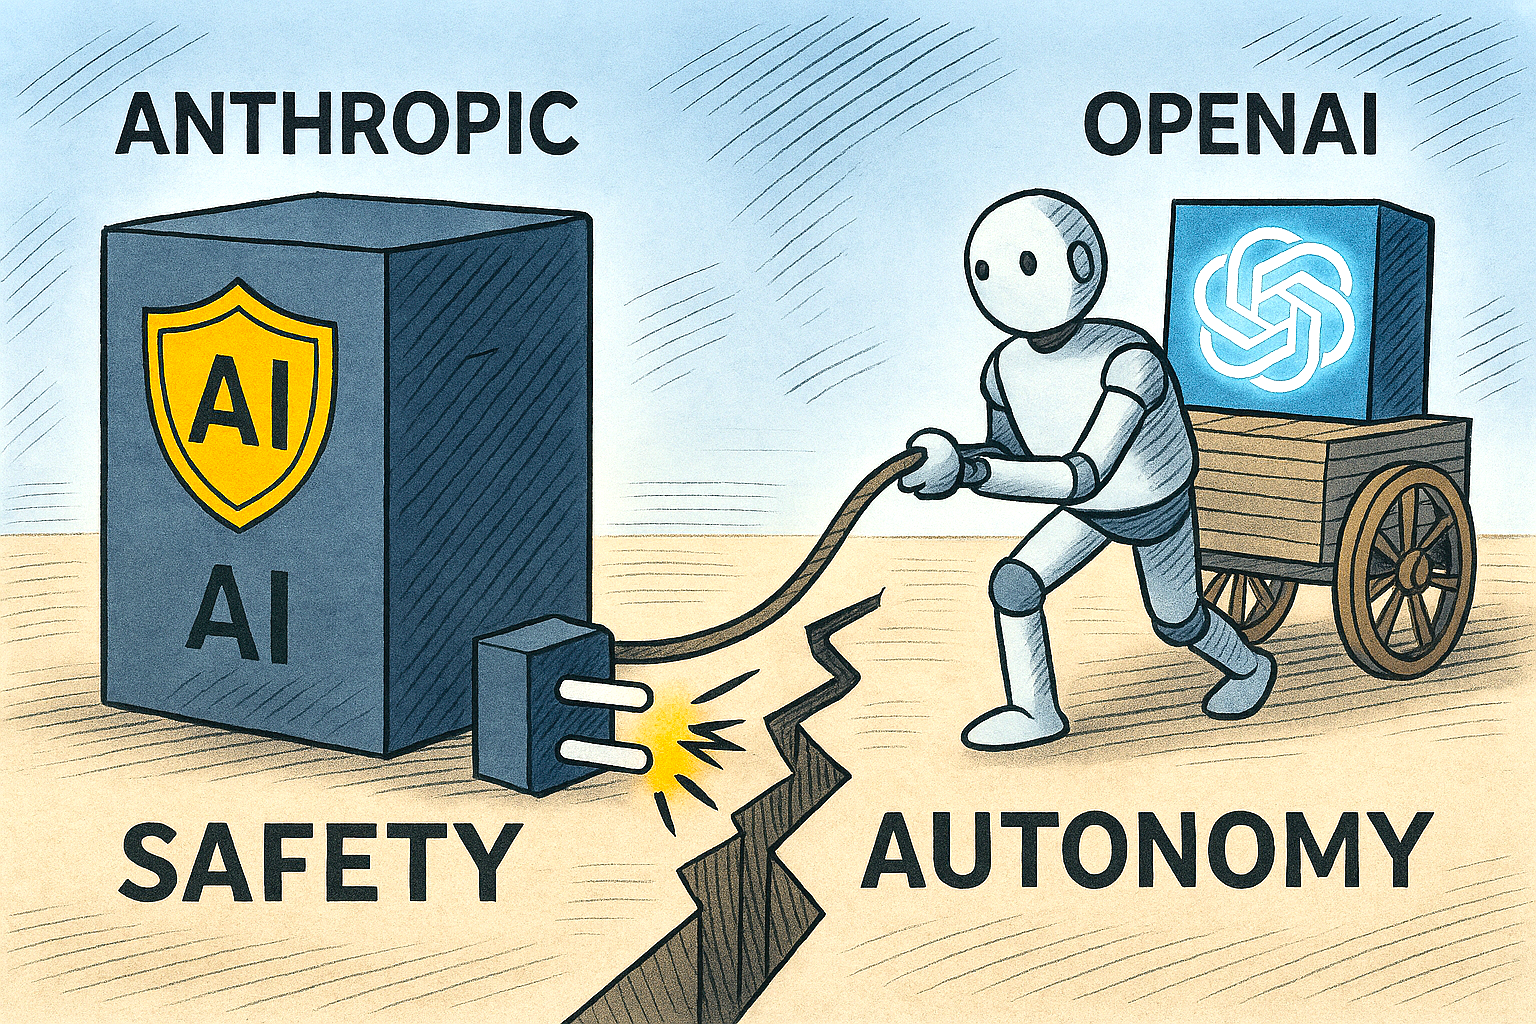
OpenAI vs Anthropic: Safety vs Autonomy in Federal AI
OpenAI’s agentic tools are likely filling the vacuum left by Anthropic’s ban, offering flexible deployment and autonomous task execution prized by defence and intelligence agencies.
While Claude prioritised safety constraints and ethical guardrails, OpenAI’s GPT‑based systems should offer broader operational freedom.
This shift reflects a deeper philosophical divide: Anthropic’s models were designed to resist misuse, while OpenAI’s are engineered for adaptability and control.
As federal agencies recalibrate, the tension between safety‑first design and unrestricted autonomy is becoming the defining fault line in U.S. government AI strategy.
How long will it be before Anthropic is invited back to the table?
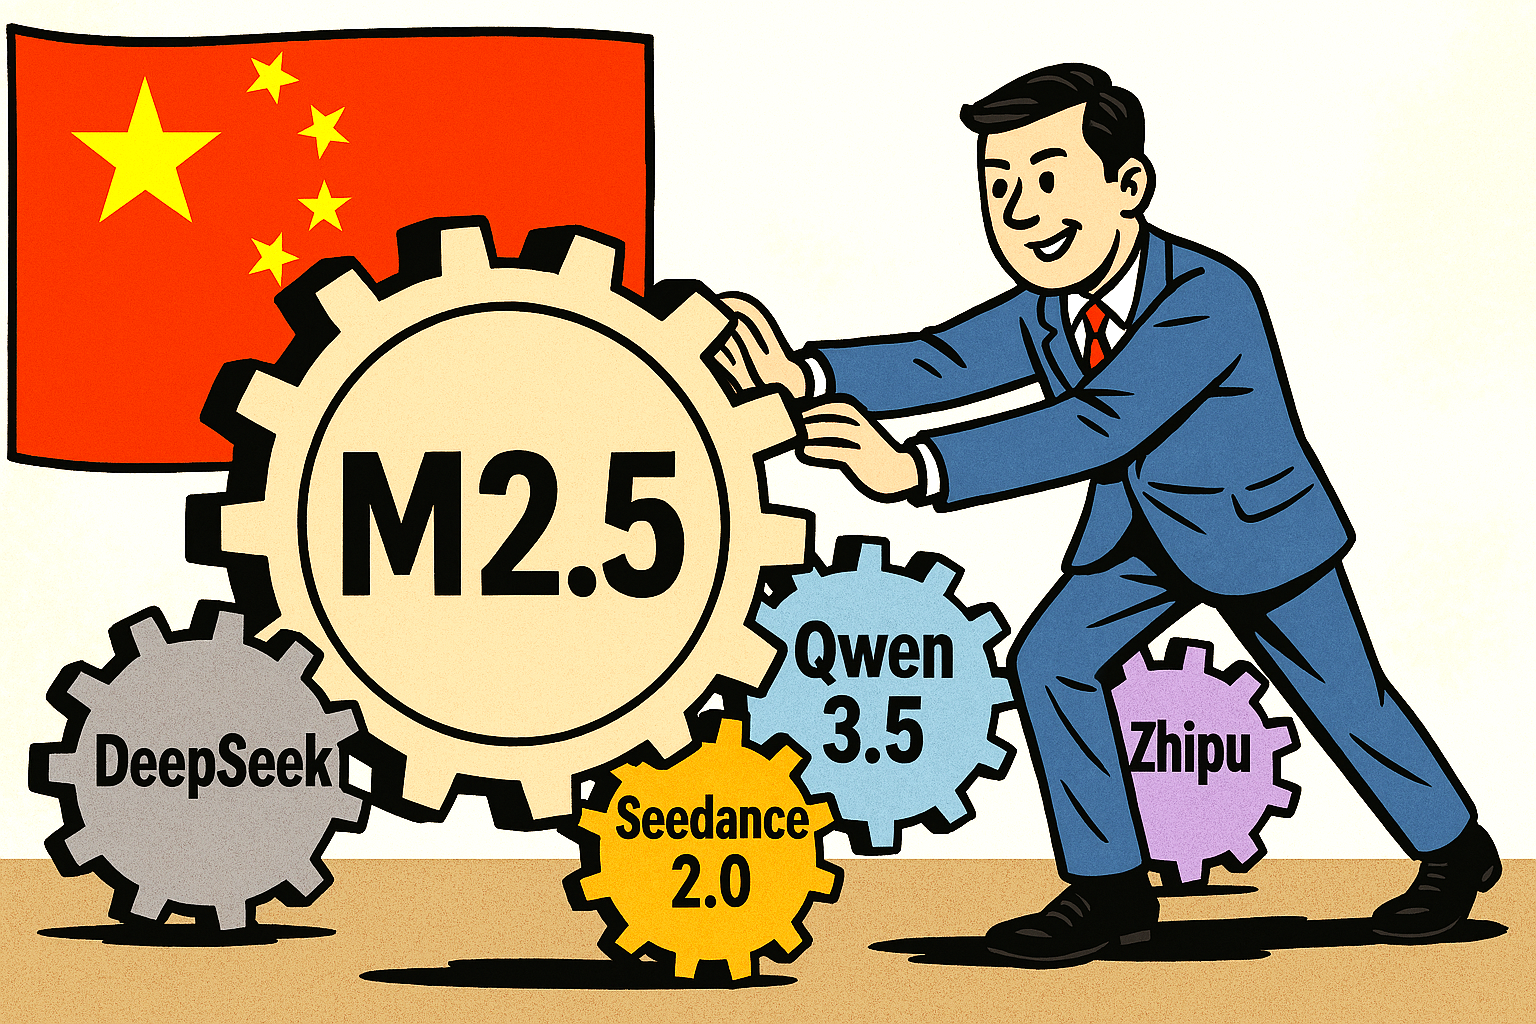
MiniMax’s M2.5 model has emerged as the unexpected frontrunner in China’s latest wave of artificial intelligence releases, earning a clear endorsement from analysts.
While much of the recent global conversation has fixated on DeepSeek’s rapid evolution, China has quietly produced five new frontier‑level models in recent weeks.
Widening choice
Among them—Alibaba’s Qwen 3.5, ByteDance’s Seedance 2.0, Zhipu’s latest offerings, DeepSeek’s V3.2, and MiniMax’s M2.5—it is MiniMax that reportedly has captured institutional attention.
Some analysts reportedly cite its performance, pricing, and commercial readiness as the reasons it stands apart.
MiniMax, which listed publicly in Hong Kong in January, released M2.5 in mid‑February 2026. The model rivals Anthropic’s Claude Opus 4.6 in capability while costing a fraction of the price—an advantage that has driven a surge of developer adoption.
Data from OpenRouter reportedly shows developers increasingly choosing M2.5 over DeepSeek’s V3.2 and even several U.S. based models.
Analysts argue that this combination of competitive performance and aggressive pricing positions MiniMax as the Chinese model with the strongest global commercial potential.
Productive and less expensive
The model’s technical profile reinforces that view. M2.5 is designed for real‑world productivity, with strengths in coding, agentic tool use, search, and office workflows.
It reportedly scores around 80.2% on SWE‑Bench Verified and outperforms leading Western models—including Claude Opus 4.6, GPT‑5.2, and Gemini 3 Pro—on tasks involving web search and office automation, all while operating at ten to twenty times lower cost.
MiniMax describes the model as delivering “intelligence too cheap to meter,” a claim supported by its lightweight Lightning variant, which generates 100 tokens per second and can run continuously for an hour at roughly one dollar.
This shift signals a broader trend: China’s AI race is no longer defined by a single breakout model. Instead, a competitive ecosystem is emerging, with MiniMax demonstrating that cost‑efficient frontier performance can reshape developer behaviour and enterprise planning.
For global markets, UBS’s preference suggests that investors are beginning to look beyond headline‑grabbing releases and toward models with sustainable commercial trajectories.
Comparison of China’s Five New AI Models
Model
Developer
Key Strengths
Performance Notes
Pricing Position
MiniMax M2.5
MiniMax
Coding, agentic tasks, office automation
Rivals Claude Opus 4.6; 80.2% SWE‑Bench Verified; outperforms GPT‑5.2 and Gemini 3 Pro on search/office tasks
Extremely low cost; “too cheap to meter”
DeepSeek V3.2
DeepSeek
Reasoning, general chat
Strong but losing developer share to M2.5
Low‑cost but not as aggressive as MiniMax
Alibaba Qwen 3.5
Alibaba
Enterprise integration, multilingual capability
Part of Alibaba’s expanding Qwen family
Competitive mid‑range
ByteDance Seedance 2.0
ByteDance
Video generation
Focused on multimodal creativity
Premium creative‑tool pricing
Zhipu (latest models)
Zhipu AI
Knowledge tasks, enterprise AI
Continues Zhipu’s push into LLM infrastructure
Mid‑range enterprise
MiniMax M2.5 leads China’s AI surge with performance rivalling Claude Opus and Gemini 1.5 Pro, yet at a fraction of the cost.
It excels in coding, search, and office automation, scoring 80.2% on SWE‑Bench Verified. DeepSeek V3.2 offers strong reasoning but lags in developer adoption.
Compared to ChatGPT-4, Claude 2.1, and Gemini 1.5, China’s models are closing the gap in capability, with MiniMax M2.5 now outperforming Western leaders on several benchmarks—especially in speed and cost efficiency.
Comparison of leading Chinese and Western AI models
(SWE‑Bench Verified — latest public leaderboard, early 2026) guide data
Model
Developer
Primary Strengths
SWE‑Bench Verified
Notes
Claude 4.6 Opus
Anthropic
High‑end reasoning, long‑context reliability
76–77%
Current top performer on independent coding benchmarks.
Nvidia’s earnings didn’t disappoint on the numbers — they were spectacular — but Wall Street was disappointed by the guidance, the pricing signals, and the shift in the AI‑chip cycle, which is why the stock fell despite a blowout quarter.
Nvidia’s latest quarterly results were, on the surface, extraordinary. Revenue surged, margins remained enviably high and demand for its AI chips continued to reshape the global technology landscape.
Yet the company’s shares fell sharply, dragging broader markets with them. The reaction reflects a deeper unease on Wall Street: not about what Nvidia has achieved, but about what comes next.
The company delivered a blowout quarter, but investors were looking for something even more explosive.
Cooling expectations after a year of euphoria
Nvidia has become the defining stock of the AI boom, and with that status comes a valuation that assumes relentless acceleration.
This quarter’s guidance, while strong, suggested growth is beginning to normalise. Investors who had priced in another step-change in demand instead saw signs of a company settling into a more sustainable—though still impressive—trajectory.
In a market conditioned to expect perpetual hyper‑growth, “very strong” can feel like a disappointment.
Fears of peak pricing power
A second concern is whether Nvidia’s extraordinary pricing power is nearing its peak. The company’s flagship AI chips have commanded eye‑watering prices, but cloud providers and enterprise customers are now signalling resistance.
Competitors are improving, and hyperscalers are accelerating development of their own silicon.
Some analysts are asking – whether the industry has already seen the high‑water mark for Nvidia’s margins, a question that goes straight to the heart of the stock’s valuation.
China remains a structural drag
Regulatory constraints continue to weigh on Nvidia’s China business. The company has not yet been able to meaningfully sell its U.S. approved AI chips into the market, and executives have warned that local rivals could fill the gap.
China was once a major contributor to Nvidia’s data‑centre revenue; now it is a source of uncertainty. Investors are increasingly factoring in the possibility that this revenue may not return in its previous form.
A crowded trade unwinds
Finally, Nvidia’s sell‑off reflects positioning as much as fundamentals. The stock has been one of the most crowded trades in global markets.
When expectations are stretched, even exceptional results can trigger profit‑taking. The pullback spilled into broader indices, with Asia‑Pacific markets trading mixed as investors digested the slump.
Nvidia remains the central force in the AI hardware boom, but Wall Street is beginning to ask harder questions about sustainability, competition and the next phase of growth.
The question of whether China can overtake the United States in artificial intelligence has shifted from speculative debate to a central geopolitical storyline.
What once looked like a distant rivalry is now a tightly contested race, shaped by compute constraints, divergent industrial strategies, and the growing importance of AI deployment rather than pure research supremacy.
Chinese Technology
China’s progress over the past few years has been impossible to ignore. A wave of domestic model developers has emerged, producing systems that—while not yet at the absolute frontier—are increasingly competitive.
Their rapid ascent has unsettled assumptions about a permanent American lead. Analysts now argue that a significant share of the world’s population could be running on a Chinese technology stack within a decade, particularly across regions where cost, accessibility, and political alignment matter more than brand prestige or cutting‑edge performance.
Yet China’s momentum is not without friction. The country’s biggest structural challenge remains compute.
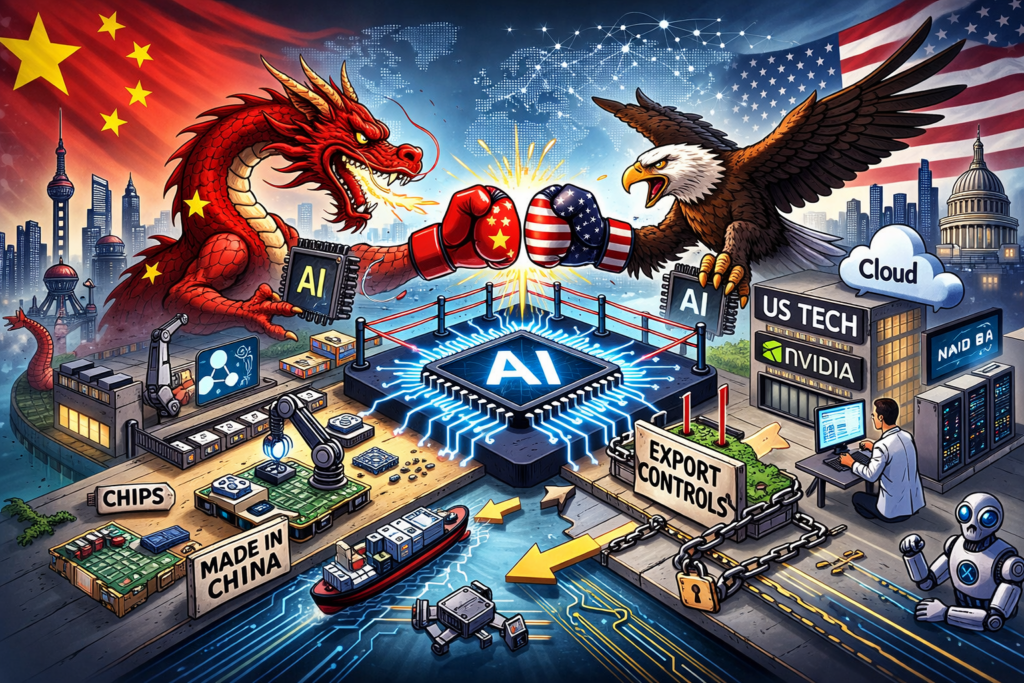
Export controls have sharply limited access to the most advanced GPUs, creating a ceiling on how far and how fast Chinese labs can scale their largest models.
Even leading Chinese developers openly acknowledge that they operate with fewer resources than their American counterparts.
AI Investment Research
This gap matters: frontier AI research is still heavily dependent on vast compute budgets, and the United States retains a decisive advantage in both semiconductor technology and hyperscale infrastructure.
But China has turned constraint into strategy. Rather than chasing brute‑force scale, its labs have doubled down on efficiency—pioneering quantisation techniques, optimised inference pipelines, and compute‑lean architectures that deliver strong performance at lower cost.
In a world where enterprises increasingly care about value rather than theoretical peak capability, this approach is resonating.
Open‑weight Chinese models, in particular, are eroding the commercial moat of closed‑source American systems by offering capable alternatives that organisations can run cheaply on their own hardware.
Power Hungry
Energy is another under‑appreciated factor. China’s massive expansion of power generation—adding more capacity in four years than the entire U.S. grid—gives it a long‑term advantage in scaling data‑centre infrastructure.
AI is an energy‑hungry technology, and the ability to deploy at national scale may prove as important as breakthroughs in model design.
Still, the United States retains formidable strengths. It leads in advanced chips, frontier‑model research, and global cloud platforms.
American firms continue to attract enormous investment and maintain deep relationships with governments and enterprises worldwide. These advantages are not easily replicated.
The most realistic outcome is not a single winner but a universal AI landscape. China will dominate in some regions and layers of the stack; the U.S. will lead in others.
Translation of AI Power
The race is no longer about who builds the ‘best’ model, but who can translate artificial intelligence into economic and strategic power at scale.
China may not ‘win’ outright—but it no longer needs to. It only needs to be close enough to reshape the global balance of technological influence.
And on that front, the race is already far tighter than many expected.
When artificial intelligence first ignited investor enthusiasm, it lifted almost every major technology stock.
The narrative was simple: AI would transform industries, boost productivity and unlock vast new revenue streams.
Yet as the cycle matures, markets are becoming more selective. In recent weeks, shares of IBM have drifted lower, illustrating how the ‘AI effect’ can cut both ways.
At first glance, IBM should be a prime beneficiary. The company has spent years repositioning itself around hybrid cloud infrastructure, data analytics and enterprise AI solutions.
Its Watson platform has been refreshed with generative AI tools designed to automate customer service, streamline software development and enhance business decision-making. Management has repeatedly emphasised AI as a core growth engine.
Market Expectations
However, the market’s expectations have shifted. Investors are increasingly rewarding companies that sit at the very heart of AI infrastructure — those supplying advanced semiconductors, high-performance computing capacity and hyperscale cloud services.
These businesses are reporting visible surges in AI-related demand, often accompanied by sharp revenue acceleration and expanding margins.
By contrast, IBM’s AI exposure is embedded within broader consulting and software operations, making its growth trajectory appear steadier rather than explosive.
This distinction matters in a momentum-driven environment. When earnings updates fail to deliver dramatic upside surprises, shares can quickly lose favour.
Less AI Effect
IBM’s results have shown progress in software and recurring revenue, but they have not reflected the kind of dramatic AI-driven uplift seen elsewhere in the sector. For some investors, that raises questions about competitive positioning and pricing power.
There is also a perception issue. Despite its reinvention efforts, IBM still carries the legacy image of a mature technology conglomerate rather than a cutting-edge AI disruptor.
In a market captivated by bold innovation stories, narrative can influence valuation just as much as fundamentals.
If capital flows concentrate in a handful of high-growth AI names, diversified players may struggle to keep pace in share price performance.
AI Tension
Yet the sell-off may also highlight a deeper tension within the AI theme. Enterprise adoption of AI tools tends to be gradual, cautious and closely tied to measurable productivity gains.
IBM’s strategy is built around long-term integration rather than short-term hype. While that approach may lack immediate fireworks, it could prove more durable as corporate clients prioritise reliability, governance and cost control.
For now, though, the AI effect is amplifying investor discrimination. In a market eager for rapid transformation, IBM’s more measured path has translated into weaker share performance — a reminder that not all AI exposure is valued equally.
Further discussion
IBM has found itself on the wrong side of the artificial intelligence boom, with its shares tumbling more than 13% after Anthropic unveiled a new capability that directly targets one of the company’s most enduring revenue pillars: COBOL modernisation.
The sell‑off reflects a broader market anxiety that AI is beginning to erode long‑protected niches in enterprise technology, and IBM has become the latest high‑profile casualty.
For decades, IBM has been synonymous with mainframe computing and the maintenance of vast COBOL‑based systems that underpin global finance, government services, airlines, and retail transactions.
These systems are notoriously complex, expensive to update, and dependent on a shrinking pool of specialist developers.
Premium Brand
That scarcity has long worked in IBM’s favour, allowing it to charge a premium for modernisation and support.
Anthropic’s announcement threatens to upend that equation. Its Claude Code tool, the company claims, can automate the most time‑consuming and costly parts of understanding and restructuring legacy COBOL environments.
Tasks that once required teams of analysts months to complete—mapping dependencies, documenting workflows, identifying risks—can now be accelerated dramatically through AI‑driven analysis.
The implication is clear: modernising legacy systems may no longer require the same level of human expertise, nor the same level of spending.
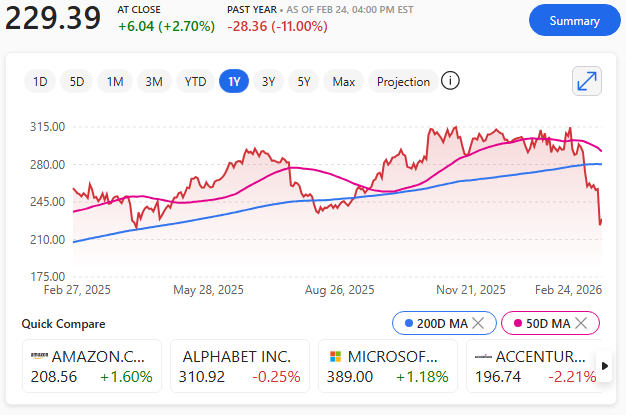
Investors reacted swiftly. IBM’s share price fell to $223.35, extending a year‑to‑date decline of more than 24% – recovering later to $229.39
IBM one-year chart as of 24th February 2026
The drop reflects not only concerns about lost revenue, but also the fear that IBM’s competitive moat—built on decades of institutional reliance on COBOL—may be eroding faster than expected.
The timing has amplified market jitters. Only days earlier, cybersecurity stocks were hit by another Anthropic announcement: Claude Code Security, a feature designed to scan codebases for vulnerabilities.
AI Mood Logic
The rapid expansion of AI into specialised technical domains has created a ‘sell first, ask questions later’ mood across the market, with investors increasingly wary of companies whose business models depend on labour‑intensive or legacy‑bound processes.
For IBM, the challenge now is to demonstrate that it can harness AI rather than be displaced by it.
The company has invested heavily in its own AI initiatives, but the latest market reaction suggests investors are unconvinced that these efforts will offset the threat to its traditional strongholds.
The AI revolution is reshaping the technology landscape at speed. IBM’s sharp decline is a reminder that even the industry’s oldest giants are not insulated from disruption—and that the next wave of AI competition may hit the most established players hardest.
But remember, this is IBM we are talking about.
Explainer
What is COBOL?
COBOL is an old but remarkably durable programming language created in the late 1950s to run business, finance, and government systems, and it’s still powering much of the world’s banking and administrative infrastructure today.
It was designed to read almost like plain English, making it easier for non‑technical managers to understand, and its stability means many core systems have never been replaced.
For much of the past three years, the so‑called Magnificent Seven – Apple, Microsoft, Alphabet, Amazon, Meta, Tesla and Nvidia – have powered US equities to repeated record highs.
Their sheer scale, earnings strength and centrality to the AI boom turned them into a market narrative as much as an investment theme.
But as 2026 unfolds, the question is no longer whether they can keep leading the market higher, but whether the idea of treating them as a single trade still makes sense.
The short answer is closer to: the trade isn’t dead, but the era of effortless, broad‑based mega‑cap dominance is fading.
Mag 7 fatigue
The first sign of fatigue is the breakdown in cohesion. Last year, only a minority of the seven outperformed the wider S&P 500, a sharp contrast to the near‑uniform surges of 2023 and early 2024.
Nvidia and Alphabet continue to benefit from the structural demand for AI infrastructure and cloud‑driven productivity gains. Others, however, appear to be wrestling with slower growth, regulatory pressure or strategic resets.
Apple faces a maturing hardware cycle, Tesla is contending with intensifying global competition, and Meta’s spending plans continue to divide investors.
Mag 7 trade – which company is missing?
Divergence
This divergence matters. For years, investors could simply buy the group and let the rising tide of AI enthusiasm and index concentration do the work.
That simplicity has evaporated. Stock‑picking is back, and the market is finally distinguishing between companies with accelerating earnings power and those relying on past momentum.
At the same time, market breadth is improving. Capital is rotating into industrials and defensive sectors as investors seek exposure to areas that have lagged the mega‑cap rally. However, AI is affecting software stocks, law and financial sectors.
Healthy future
This broadening is healthy: it reduces concentration risk and signals that the U.S. economy is no longer dependent on a handful of tech giants to sustain equity performance.
Yet it would be premature to declare the Magnificent Seven irrelevant. Their combined earnings growth is still expected to outpace the rest of the index, and their role in AI, cloud computing and digital infrastructure remains foundational.
Change
What has changed is the nature of the trade. These are no longer seven interchangeable vehicles for tech exposure; they are seven distinct stories with diverging trajectories.
The Magnificent Seven haven’t left the stage. They have likely stopped performing in unison – and for investors, that marks the beginning of a more nuanced, more selective chapter.
Blue Owl’s decision to halt investor withdrawals at one of its flagship retail‑focused private credit vehicles has sent a jolt through a market long celebrated for its resilience.
The move, centred on Blue Owl Capital Corporation II (OBDC II), marks one of the most significant stress signals yet in the rapidly expanding private credit sector.
Redemption
The firm confirmed that investors in OBDC II will no longer be able to redeem shares on a quarterly basis, ending a mechanism that previously allowed withdrawals of up to 5% of net asset value each quarter.
The redemption facility had already been paused in November 2025 as withdrawal requests accelerated, but the permanent halt represents a decisive shift.
To meet liquidity needs and prepare for a partial return of capital, Blue Owl has sold a substantial portion of its loan book.
Reportedly around $600 million of assets were offloaded from OBDC II as part of a wider $1.4 billion sale across three funds, with the firm planning to return 30% of the fund’s value to investors by the end of March.
Reaction
Markets reacted swiftly. Shares in Blue Owl fell between 6% and 10% across recent trading sessions, touching their lowest levels in more than two years.
The sell‑off was fuelled not only by the redemption freeze but also by broader concerns about the firm’s exposure to software‑sector borrowers — an area facing valuation pressure and heightened sensitivity to disruption from artificial intelligence.
The episode has reignited debate about the structural vulnerabilities of private credit, a market now estimated at $1.8 trillion.
The model relies on illiquid loans packaged into vehicles that promise periodic liquidity to investors — a mismatch that works only as long as redemption requests remain manageable.
Blue Owl’s move suggests that, under stress, even well‑established managers may be forced into asset sales or wind‑down scenarios.
Contagion?
Contagion fears quickly spread across the sector. Shares of major alternative‑asset managers, including Apollo, Blackstone and TPG, all declined sharply as investors reassessed liquidity risks in retail‑facing credit products.
For now, Blue Owl insists that capital will continue to be returned through loan repayments and asset sales.
But the permanent closure of redemptions at OBDC II stands as a stark reminder: the private credit boom is entering a more volatile phase, and liquidity — once taken for granted — is becoming the industry’s most fragile commodity.
Nvidia has formally severed its financial ties with Arm Holdings, selling the final tranche of its shares and closing the book on one of the semiconductor industry’s most ambitious — and ultimately unsuccessful — takeover attempts.
Regulatory filings reportedly show the chipmaker disposed of roughly 1.1 million Arm shares during the fourth quarter, a holding valued at around $140 million based on Arm’s recent market price.
Sale of entire ARM stake
The move brings Nvidia’s ownership of the British chip‑architecture specialist to zero, marking a symbolic end to a saga that began in 2020 when Nvidia launched a bold $40 billion bid to acquire Arm.
That deal, which would have reshaped the global semiconductor landscape, collapsed under intense regulatory scrutiny and resistance from major industry players concerned about competition and neutrality.
Despite the divestment, the relationship between the two companies is far from over. Nvidia remains a major licensee of Arm’s instruction‑set technology, which underpins its current and next‑generation CPU designs.
Strategic move
Analysts note that the sale appears to be strategic housekeeping rather than a shift in technological direction, especially given Nvidia’s rapid expansion across data‑centre, AI, and edge‑computing markets.
Arm’s shares initially wobbled on news of the disposal but quickly stabilised, even edging higher as investors interpreted Nvidia’s exit as a clearing of legacy baggage rather than a signal of weakening confidence in Arm’s long‑term prospects.
The company, now primarily owned by SoftBank, continues to push ahead with its growth strategy following its public listing.
For Nvidia, the sale represents a clean break from a failed acquisition that once promised to redefine the industry.
For Arm, it marks another step in its evolution as an independent powerhouse at the centre of global chip design. The strategic paths of both companies however, remain intertwined
For much of the modern AI era, the United States has held a clear advantage in frontier research, compute infrastructure, and commercial deployment.
Silicon Valley’s combination of elite talent, abundant capital, and world‑class semiconductor design created an environment where breakthroughs could scale at extraordinary speed.
Challenge
That dominance, however, is no longer uncontested. China’s accelerating push into advanced AI is reshaping the global technological landscape and posing the most credible challenge yet to America’s leadership.
China’s strategy is not built on a single breakthrough but on coordinated national effort. Beijing has spent years aligning universities, state‑backed funds, and private‑sector giants around a shared objective: achieving self‑sufficiency in critical technologies and becoming a global AI powerhouse.
Competitive
Companies such as Huawei, Baidu, Alibaba and Tencent are now producing increasingly competitive large models, while domestic chipmakers are narrowing the performance gap with U.S. suppliers despite export controls.
Crucially, China’s AI ecosystem benefits from scale and cost advantages that the U.S. cannot easily replicate.
Massive data availability, lower energy costs, and vertically integrated supply chains allow Chinese firms to train and deploy models at prices that appeal to developing economies.
For many countries, especially those already reliant on Chinese infrastructure, adopting a Chinese AI stack is becoming a pragmatic economic choice rather than a geopolitical statement.
Investment returns?
This shift is occurring just as U.S. tech giants embark on unprecedented spending cycles. Hyperscalers are pouring hundreds of billions of dollars into data centres, specialised chips, and model training.
The U.S. and its massive BIG Tech Spending Spree – Feeding the AI Habit
While this investment underscores America’s determination to stay ahead, it also raises questions about sustainability.
Investors are increasingly asking whether such vast capital expenditure can deliver long‑term returns in a world where China is offering cheaper, rapidly improving alternatives.
The emerging reality is not one of immediate American decline but of a genuinely multipolar AI landscape. The U.S. still leads in foundational research, top‑tier talent, and cutting‑edge semiconductor design.
Yet China’s rise represents a powerful economy that has mounted a serious challenge to the technological frontier.
The global AI race is no longer defined by a single centre of gravity. Instead, two competing ecosystems — one market‑driven, one reportedly state‑directed — are shaping the future of intelligent technology.
The outcome will influence not only economic power but the digital architecture of much of the world.
The world’s largest cloud providers are engaged in one of the most expensive technological races in history.
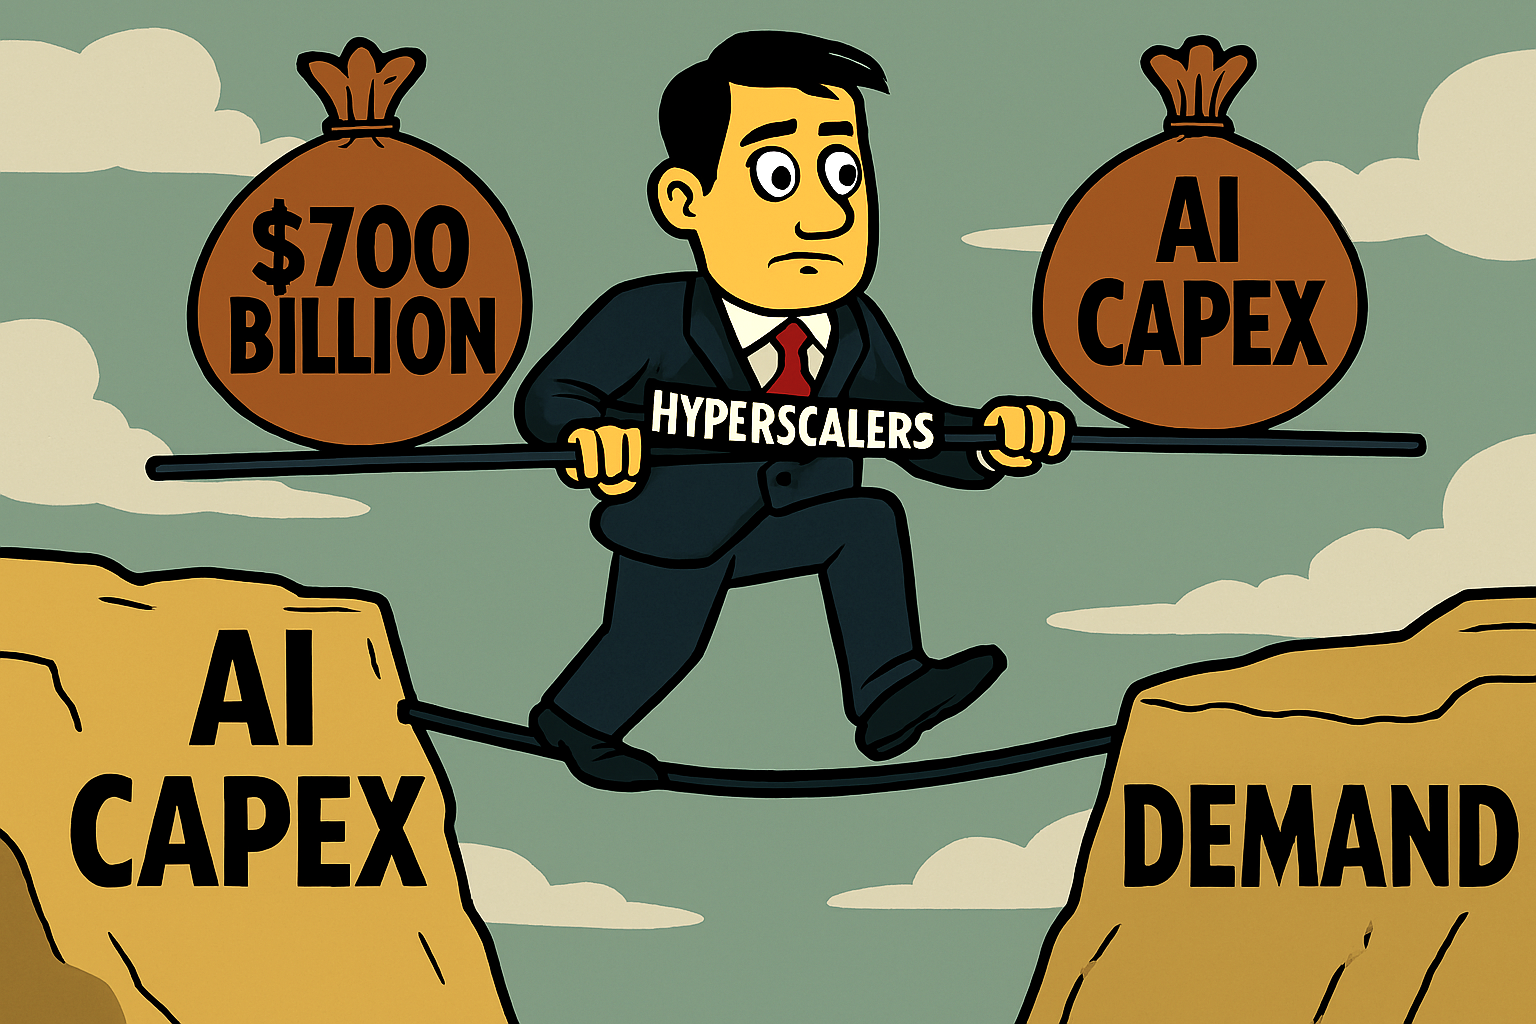
Amazon, Microsoft, Meta and Alphabet are collectively on track to spend as much as $700 billion on AI‑related capital expenditure this year — a figure that rivals the GDP of mid‑sized nations and has understandably rattled investors.
The question now dominating markets is simple: can hyperscalers justify this level of spending, and should analysts remain so bullish on their stocks?
A Binary Bet on the Future of AI
The scale of investment has shifted the AI build‑out from a strategic growth initiative to what some analysts describe as a binary corporate bet. As some analysts suggest, the leap in capex — up roughly 60% year‑on‑year — means the payoff must be both rapid and substantial.
If monetisation fails to keep pace, the consequences could be of severe concern.
This is compounded by the fact that hyperscalers are now consuming nearly all of their operating cash flow to fund AI infrastructure, compared with a decade‑long average of around 40%. That shift alone explains the recent market jitters.
Why Analysts Remain Upbeat
Despite the turbulence, many analysts still argue the long‑term fundamentals remain intact. One reason is that hyperscalers are pre‑selling data‑centre capacity before it is even built, effectively locking in revenue ahead of deployment.
That dynamic supports the bullish view that AI demand is not only real but accelerating.
There is also a belief that as AI tools become embedded across consumer and enterprise workflows, willingness to pay will rise sharply.
If that scenario plays out, today’s eye‑watering capex could look prescient rather than reckless.
The Real Risk: Timelines
The challenge is timing. Much of the infrastructure being deployed — from chips to data‑centre hardware — has a useful life of just three to five years.
That gives hyperscalers a narrow window to recoup investment before the next upgrade cycle hits.
Without clearer monetisation strategies and firmer payback timelines, investor anxiety is likely to persist.
AI capex justification?
Hyperscalerscan justify their AI capex — but only if demand scales as quickly as they expect and monetisation becomes more transparent.
Analysts may be right to stay bullish, but the margin for error is shrinking. In the coming quarters, clarity will matter as much as capital.
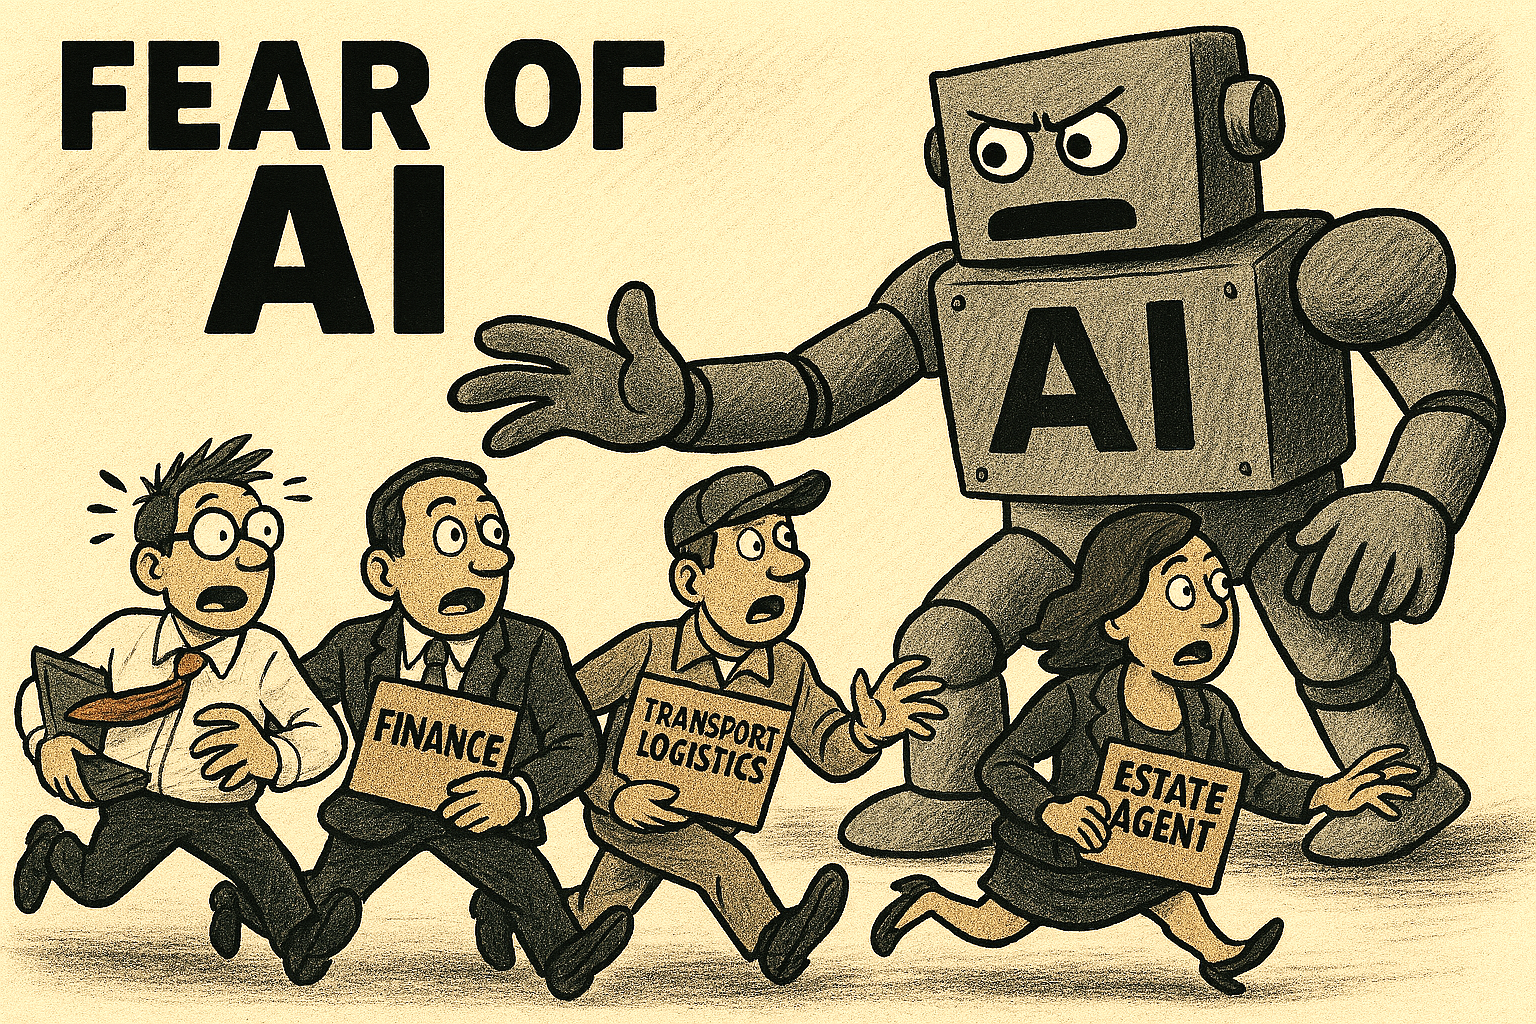
A curious shift has taken place over the past year. The fear of AI ‘taking over’ is no longer confined to software engineers, coders, or the legal and financial professions.
It has spilled into transport logistics, estate agency, recruitment, customer service, and even the once‑untouchable world of creative work.
Anxiety spreads
The anxiety is spreading horizontally across the economy rather than vertically within a single industry — and that tells us something important about where we are in the technological cycle.
At the heart of this unease is a simple realisation: AI is no longer a specialised tool. It is becoming a general‑purpose capability, much like electricity or the internet.
When a technology can be applied to almost any workflow, the boundaries between ‘safe’ and ‘at risk’ jobs dissolve.
Estate agents see AI systems that can generate listings, negotiate pricing models, and automate client follow‑ups. Logistics managers watch algorithms optimise routes, staffing, and inventory with a precision no human team can match.
Even white‑collar professionals, once insulated by complexity and regulation, now face AI systems capable of drafting contracts, analysing case law, or producing financial models in seconds.
This broadening of impact is what’s fuelling the current wave of concern. It’s not that AI is replacing everyone — it’s that it could plausibly reshape the value chain in every sector.
Axis shift
For the stock market, this shift has created a two‑speed economy. Companies building AI infrastructure — chips, cloud platforms, foundation models — are being rewarded with valuations that assume long‑term dominance.
Meanwhile, firms whose business models rely on labour‑intensive processes are being quietly repriced. Investors are asking a new question: Which companies can integrate AI fast enough to defend their margins? Those that can’t risk being treated like legacy utilities.
But the story isn’t simply about winners and losers. The diffusion of AI across industries also creates a multiplier effect.
Productivity gains in logistics lower costs for retailers; smarter estate agency tools accelerate housing transactions; automated legal drafting reduces friction for start‑ups. Each improvement compounds the next.
AI taking over?
The fear, then, is partly a misunderstanding. AI isn’t ‘taking over’ — it’s infiltrating. It is dissolving inefficiencies, redrawing job descriptions, and forcing companies to rethink what they actually do.
The stock market has already priced in the first wave of this transformation. The second wave — where every sector becomes an AI‑enabled sector — is only just beginning.
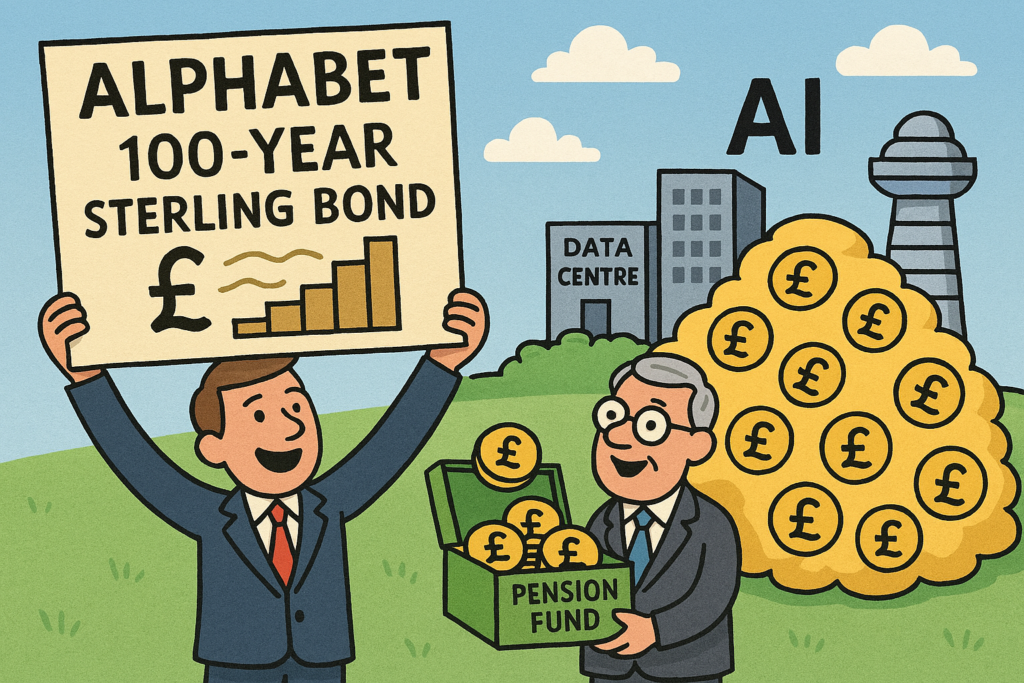
Alphabet’s decision to issue a 100-year sterling bond has captured the attention of global markets, not only because of its rarity but also because of what it signals about the escalating competition in artificial intelligence.
100 year sterling bond
A century-long bond denominated in pounds is an extraordinary financing move, particularly for a technology company.
It reflects both investor confidence in Alphabet’s long-term prospects and the scale of capital now required to compete in the AI era.
On the surface, the benefits are clear. Locking in funding for 100 years at today’s rates provides financial certainty. Alphabet can secure vast sums of capital without facing refinancing risk for generations.
In an industry defined by rapid change and enormous upfront costs — from data centres and semiconductor procurement to specialised AI chips and energy infrastructure — patient capital is invaluable.
Sterling
The sterling denomination also diversifies Alphabet’s funding base beyond U.S. dollar markets, potentially appealing to European institutional investors seeking stable, long-duration assets.
The bond may also be interpreted as a strategic signal. By committing to long-term financing, Alphabet demonstrates confidence in its ability to generate cash flows well into the next century.
It reinforces the company’s image as a durable, infrastructure-like enterprise rather than a volatile technology stock.
For investors such as pension funds and insurers, a 100-year instrument from a highly rated issuer can offer predictable returns in a world where long-term yield is scarce.
Cyclical
However, the move is not without shortcomings. Committing to fixed debt obligations over such an extended horizon reduces flexibility. While Alphabet currently enjoys strong balance sheet metrics, the technology sector is notoriously cyclical.
A century is an eternity in innovation terms. Business models, regulatory frameworks and geopolitical dynamics may shift dramatically.
Future generations of management will inherit the obligation, regardless of whether today’s AI investments deliver the expected returns.
More broadly, the bond feeds concern about a debt-fuelled AI arms race. As technology giants pour tens of billions into AI research, chip design and cloud infrastructure, borrowing is becoming an increasingly prominent tool.
If rivals respond with similar long-dated issuance, the sector’s leverage could rise meaningfully. In a downturn or if AI monetisation disappoints; heavy debt burdens could amplify financial strain.
Ultimately, Alphabet’s 100-year sterling bond embodies both ambition and risk. It underlines the immense capital demands of the AI revolution while raising questions about whether today’s competitive fervour is encouraging companies to stretch their balance sheets too far in pursuit of technological dominance.
Systemic anxiety
The deeper anxiety is systemic. With Oracle, Amazon, Microsoft and others also scaling up borrowing, total tech‑sector issuance is projected to hit $3 trillion over five years.
Some analysts warn this resembles a late‑cycle credit boom, where investors chase thematic excitement rather than sober fundamentals.
Alphabet’s century bond may be a masterstroke of timing — or a marker of excess.
Either way, it crystallises the tension at the heart of the AI revolution: extraordinary promise, financed by extraordinary debt.
Why a Sterling Bond?
Alphabet issued its 100‑year sterling bond to tap deep UK demand for ultra‑long‑dated assets, especially from pension funds seeking to match long‑term liabilities.
The sterling market offered strong appetite, with orders reportedly reaching nearly ten times the £1 billion on offer.
It also formed part of Alphabet’s broader multi‑currency fundraising drive to finance massive AI‑related capital spending, including data‑centre expansion.
Issuing in sterling diversified its investor base, reduced reliance on U.S. dollar markets, and signalled confidence in its long‑term stability as a quasi‑infrastructure‑scale business.
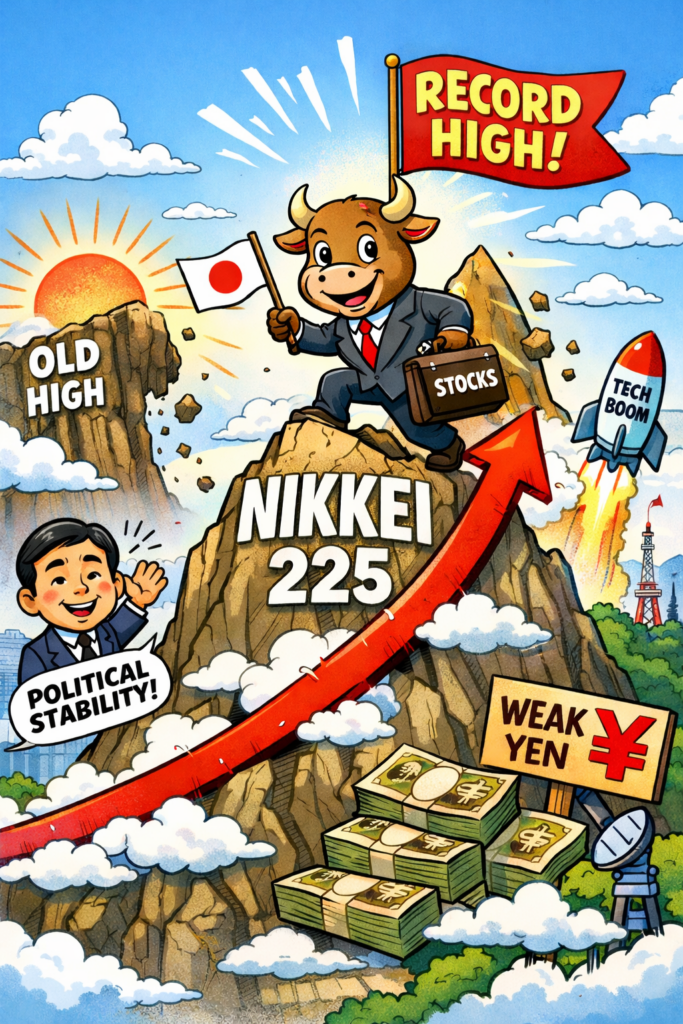
Japan’s Nikkei 225 has surged to a series of record highs, signalling a decisive shift in investor sentiment as political clarity, a weak yen, and global tech momentum converge.
The index has climbed well beyond its previous peaks, driven by strong demand for semiconductor and AI‑linked stocks, alongside renewed confidence in Japan’s economic direction.
The index is hitting repeated all‑time highs
The Nikkei has surged to fresh record levels — closing around 57,650 and even touching 57,760 in early trade. This marks consecutive days of record closes.
In previous intraday trading the Nikkei 225 touched 58,500.
The driver: the ‘Takaichi trade’
Markets are reacting strongly to Prime Minister Sanae Takaichi’s landslide election victory, which has created expectations of:
Looser economic policy
Increased fiscal stimulus
A more stable political environment
Investors are effectively pricing in a pro‑growth agenda with fewer legislative obstacles.
Much of the rally reflects expectations of a more expansionary policy environment. Investors are likely betting that the government will prioritise growth, support corporate investment, and maintain a stable backdrop for reform.
This has amplified interest in heavyweight exporters and technology firms, which stand to benefit both from global demand and the yen’s prolonged softness.
Weaker Yen?
The currency’s slide towards multi‑decade lows has been a double‑edged force: while it boosts overseas earnings for major manufacturers, it also raises the prospect of intervention from policymakers keen to avoid excessive volatility.
For now, markets appear comfortable with the trade‑off, focusing instead on the competitive advantage it provides.
With global equity markets still heavily influenced by AI enthusiasm and shifting monetary expectations, Japan’s resurgence stands out.
The Nikkei’s latest ascent suggests investors are increasingly willing to treat Japan not as a defensive allocation, but as a genuine engine of growth in its own right.
Nearly a decade after its launch, the Nintendo Switch has secured its place as the company’s most successful console, surpassing 155 million units sold and overtaking the long‑standing record held by the Nintendo DS.
It is a milestone that reflects not only commercial strength but a dramatic turnaround in Nintendo’s modern history.
Arrival of the Switch
When the Switch arrived in 2017, Nintendo was emerging from the disappointment of the Wii U, a console hampered by confused messaging and fierce competition. Investor confidence had waned, and the company’s valuation had slipped.
The Switch needed to be more than a hit — it needed to redefine Nintendo’s trajectory. It did exactly that.
The hybrid design proved transformative. By merging handheld and home console experiences into a single device, Nintendo unified two previously separate audiences and simplified its hardware strategy.
Success
Analysts have long argued that this consolidation was central to the Switch’s runaway success, allowing Nintendo to focus its creative and commercial energy on one platform rather than splitting resources across two.
Software, as ever, played a decisive role. First‑party titles such as Mario Kart 8 Deluxe, Animal Crossing: New Horizons, and a steady stream of Mario, Zelda and Pokémon releases kept the console culturally relevant.
Movie
The pandemic years accelerated demand further, while the 2023 Super Mario Bros. film reignited interest in Nintendo’s characters and, by extension, the Switch itself.
Nintendo’s broader strategy — expanding its intellectual property into theme parks, films, merchandise and collaborations — created a feedback loop that continually pushed new audiences toward the console.
With the Switch 2 already breaking internal sales records, Nintendo appears intent on repeating the formula.
But the original Switch remains the system that rescued, redefined and ultimately revitalised one of gaming’s most iconic companies.
The Dow Jones Industrial Average has surged beyond the 50,000 mark for the first time in its 130‑year history, capping a dramatic rebound after a turbulent week for global markets.
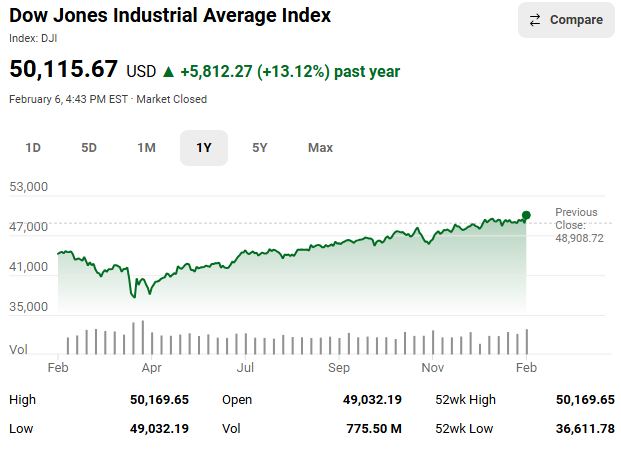
The blue‑chip index leapt more than 1,200 points on Friday 6th February 2026 to close at 50,115.
DJIA one-year chart
This climb was fuelled by renewed investor confidence and a sharp recovery in technology and cyclical stocks.
Friday’s rally followed several days of heavy selling across the tech sector, but optimism returned as chipmakers and industrial giants led a broad‑based climb.
Analysts say the move signals both the resilience of the current bull market and investors’ willingness to ‘buy the dip’ despite ongoing volatility.
Political reaction was swift, with President Donald Trump celebrating the milestone as a symbol of American economic strength.
Psychological 50,0000 barrier
Market commentators, meanwhile, emphasised the psychological significance of the 50,000 threshold, noting that the Dow has added 10,000 points in record time.
For traders on the floor of the New York Stock Exchange, the moment was marked by cheers, flashing screens, and a palpable sense of relief.
Whether the momentum continues remains to be seen, but for now, Wall Street is savouring a landmark moment decades in the making.