Starlink – Starshield and Ukraine: The Power to Switch Off a Nation’s Defences

Systems at war

Have Elon Musk, Donald Trump and the control of critical technology exposed a dangerous weakness in modern warfare.

Remote control decision

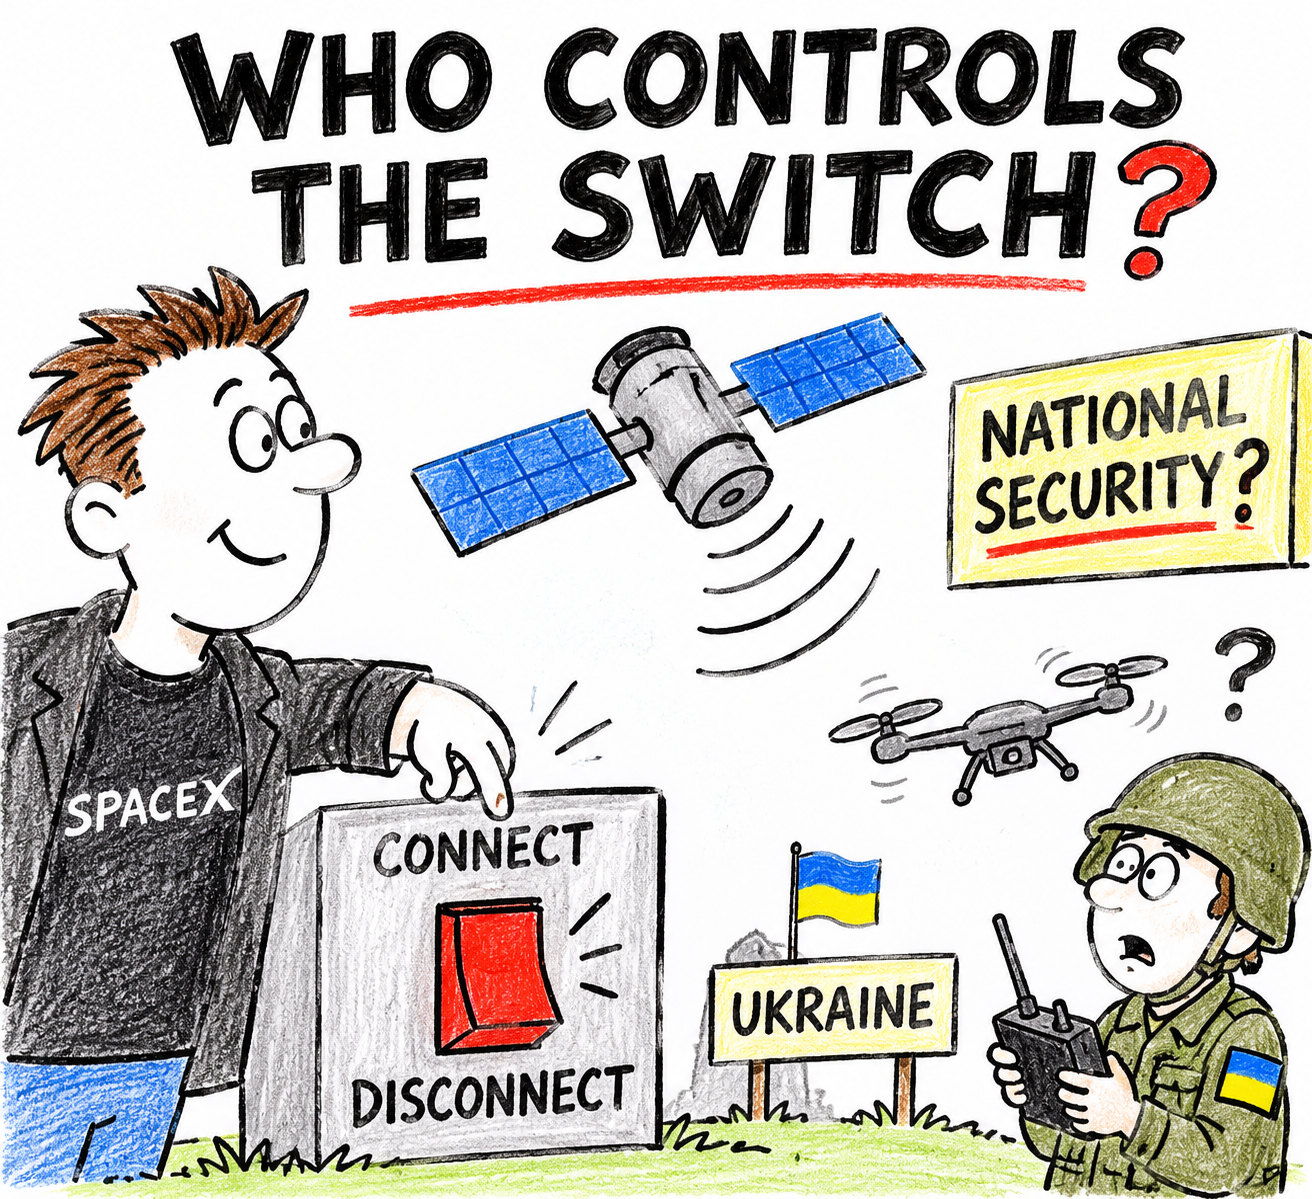
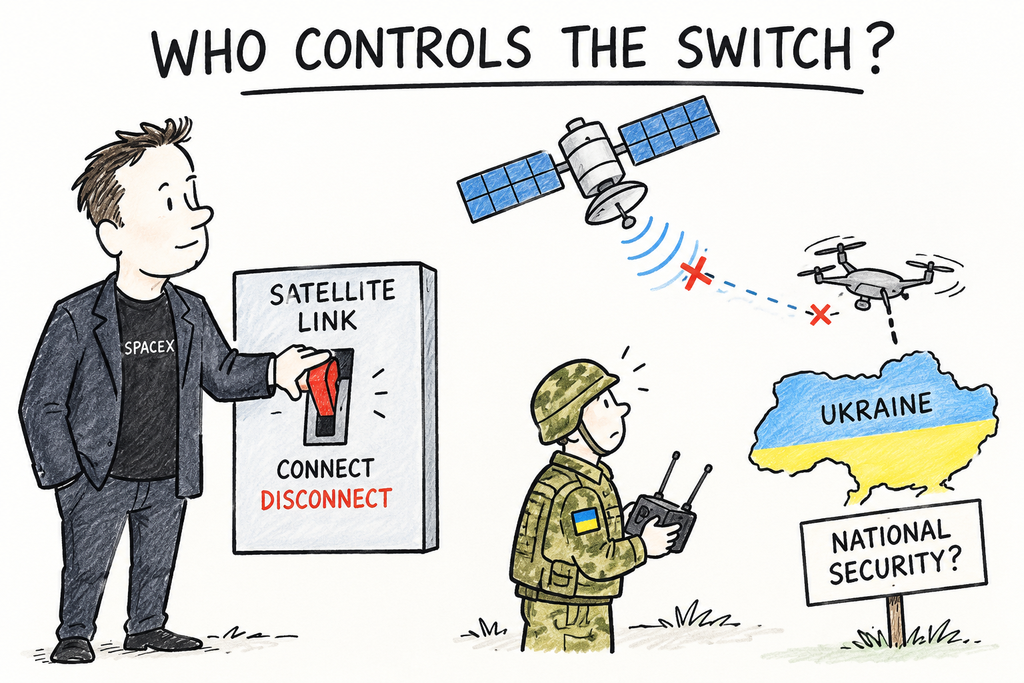
Imagine fighting a war for your country’s survival, only to discover that some of your most important military capabilities can be weakened by a decision taken thousands of miles away, in a boardroom or a government or by the White House for instance.

That is the unsettling question raised by the latest controversy surrounding Elon Musk’s SpaceX satellite technology, Donald Trump and Ukraine.

In October 2026, Ukrainian forces widely reported restrictions on their access to Starshield, the military-focused satellite communications service developed by SpaceX for the U.S. government and national-security customers.

The restrictions reportedly affected fast-moving drones, complicating Ukrainian operations against Russian forces and the interception of incoming attack drones.

Ukrainian officials reported that connectivity problems were partly resolved, but a speed restriction remained an issue.

The episode has exposed a fundamental vulnerability in modern warfare: what happens when a nation depends on technology that it does not ultimately control?

How did this happen?

Since Russia’s full-scale invasion in 2022, Starlink has become an important part of Ukraine’s communications infrastructure.

Its satellites have helped military units communicate across a battlefield where conventional infrastructure has been destroyed or disrupted.

Starshield is a separate, security-focused service, developed for government and military purposes. Although distinct from ordinary Starlink, it uses the same underlying satellite network technology.

This distinction matters because the latest controversy concerns restrictions on military-grade connectivity, not simply an ordinary household internet service being switched off.

Reports in October 2026 reportedly said that restrictions affecting terminals on fast-moving platforms disrupted Ukrainian drone operations.

A speed limit of approximately 160 kilometres per hour was reported, a significant problem for drones designed to travel faster. Ukraine said the limitations affected operations, including efforts to intercept Russian attack drones.

The question of responsibility remains contested

Reuters reported on 15th October 2026 that U.S. officials and a Western official had traced the order to limit Starshield to within the White House – this however is conjecture and unproven.

Ukrainian officials were reportedly told that the decision came from there. However, a senior U.S. official reportedly said President Trump had not requested the restriction.

Musk reportedly argued that Starshield was owned and controlled by the U.S. government, with decisions about its use resting with the American military and ultimately the president. On 16th October, Trump reportedly may have denied that he or Musk was responsible for Ukraine losing access.

Subsequent reporting, including a Wall Street Journal account cited by a U.S. Senator reportedly pointed towards Musk’s involvement and discussions with Trump and administration officials.

The precise chain of decision-making, however, has not been established publicly beyond dispute.

The important point is not to assume that one individual has been conclusively shown to have pressed a particular button. It is that the system can be restricted, and that the ability to make or authorise such a decision is concentrated in very few hands.

Why does one company have so much power?

The answer is infrastructure

SpaceX has built a vast satellite network that is difficult and expensive to replicate. Its low-Earth-orbit satellites provide connectivity in places where conventional communications networks are unavailable, damaged or vulnerable to attack.

For Ukraine, this has meant access to a capability that would otherwise have been extremely difficult to establish during wartime.

But dependence creates leverage.

A country can possess tanks, aircraft, missiles and trained soldiers while remaining dependent on an outside provider for the communications that make those assets effective.

If that connection is interrupted, the equipment may still exist, but its usefulness can diminish.

This is the distinction between owning the weapons and controlling part of the system that enables them to operate.

Musk does not personally need to command Ukrainian troops or decide which targets they attack. The ability to influence a critical communications service can itself confer considerable strategic power.

Nor does the system necessarily require a dramatic, total shutdown. A restriction on speed, coverage, access or functionality may be sufficient to undermine a particular military operation.

A technical adjustment can have consequences far beyond the software setting that produced it.

Where does Donald Trump fit into this?

The controversy also illustrates the power of the American presidency.

The United States is a major customer of SpaceX’s national-security services, and Starshield operates within a government defence framework.

Washington therefore has an important role in determining how those capabilities are supplied and used.

Trump’s administration also has substantial influence over American military assistance, intelligence sharing and the wider relationship with Ukraine.

At a time of deteriorating relations between Washington and Kyiv, the reported restrictions raised questions about whether technology access could become part of the political leverage exerted over Ukraine.

The timing is notable, but timing alone does not prove the motive behind the decision.

There are two distinct forms of power here.

Musk and SpaceX possess technical expertise, infrastructure and the ability to implement changes to services they operate.

The U.S. government possesses contractual, military and political authority over the government-controlled elements of the arrangement.

Where these powers intersect, the practical consequences for Ukraine can be immediate, even if the formal decision-making process remains opaque.

That is the real concern: a nation’s battlefield capabilities may be affected by a handful of decisions made outside its borders, without the nation itself having an effective veto.

Is this democratic accountability?

In a democracy, decisions about war and peace are supposed to be subject to public scrutiny, institutional checks and political accountability.

Yet critical digital infrastructure increasingly sits between governments and the people they serve.
A private company may be accountable to its shareholders, its contractual obligations and the laws of the country in which it operates. A president is accountable through political and constitutional institutions.

But neither arrangement automatically ensures that an allied nation dependent on the technology will receive adequate warning, consultation or protection against sudden disruption.

The problem is not simply whether Musk or Trump has acted appropriately. It is whether the safeguards are sufficient when the consequences extend to another country’s soldiers and civilians.

If an allied military depends on a commercial or government-controlled system, who decides when access can be restricted? What emergency procedures apply?

Must the affected country be notified? Can a single executive decision override established military planning? And who is accountable if the consequences are disastrous?

These are questions of governance, not merely technology.

People die!

What happens if the switch is turned off?

Ukraine cannot instantly build a replacement for a sophisticated satellite network. Alternative providers, including Europe’s OneWeb and developing satellite services from other companies, may offer options, but integrating them into military operations requires time, equipment, money and testing.

A robust defence therefore requires more than finding another supplier after a crisis begins.

Governments must consider redundancy, alternative communications systems, interoperable equipment and contingency plans. They must also examine the terms under which private companies provide services essential to national security.

The United States faces a related problem of its own. If American forces become heavily dependent on one provider, the same concentration of control could create vulnerabilities for U.S. operations in a future conflict.

This is why the episode has prompted scrutiny in Washington, including a congressional inquiry into SpaceX’s role and the government’s dependence on its technology.

The lesson extends far beyond Ukraine

Satellite communications are only one example. Similar questions arise wherever essential services depend on concentrated technological control: cloud computing, artificial intelligence, digital payment systems, communications networks and critical software.

The more indispensable a system becomes, the greater the potential influence of whoever controls access to it.

That influence need not be exercised maliciously. A legitimate security decision, a contractual dispute, a technical failure or a change in political priorities could all have serious consequences.

The danger lies in building national capabilities around a system that can be altered without sufficient safeguards. Any country could be affected.

Ukraine’s experience raises a difficult question for every government: can a nation genuinely be sovereign if essential elements of its defence depend on decisions made by a small number of people outside its control?

The answer cannot simply be to abandon private technology. Such systems can provide extraordinary capabilities that governments would struggle to develop independently.

But convenience and efficiency must be balanced against resilience and accountability.

The Power is ALL in one hand

In modern warfare, power no longer rests solely with those who possess the weapons. It can also rest with those who control the networks, software and infrastructure that make those weapons effective.

These too could be deemed part of the weapons network.

And sometimes, the most consequential weapon is not a missile or a tank.

It is the ability to decide who remains connected — and who does not.
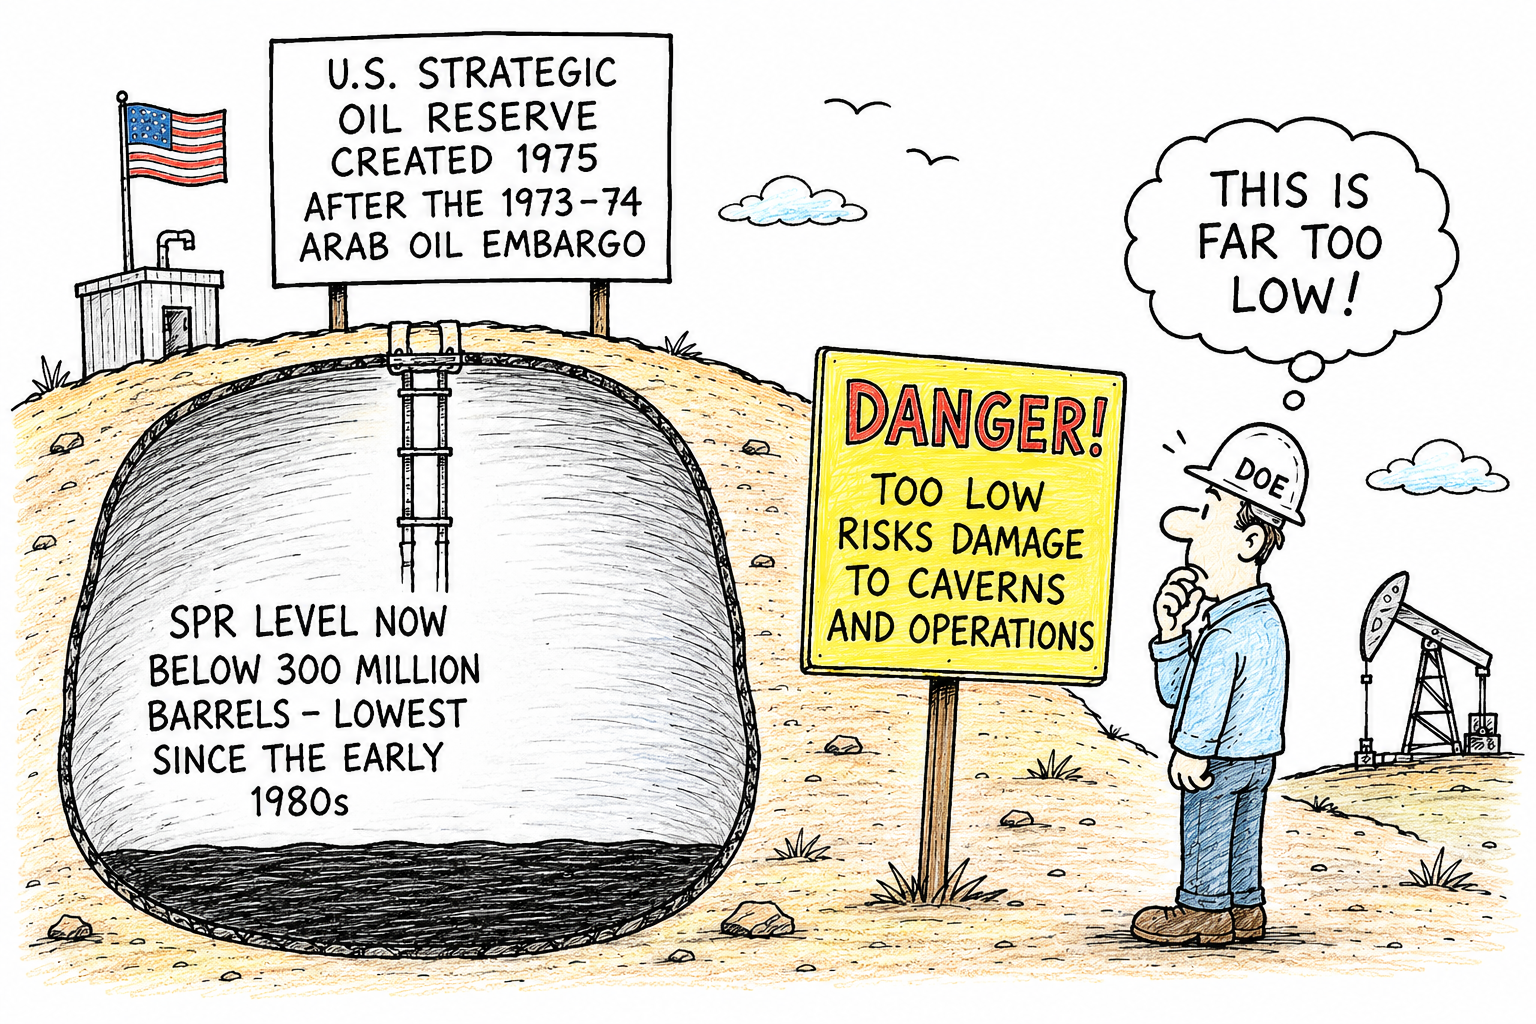
U.S. strategic Oil Reserves under Pressure

America’s Strategic Petroleum Reserve (SPR) was created in 1975, in the aftermath of the 1973–74 Arab oil embargo, when an oil supply shock exposed America’s vulnerability to disruptions in foreign energy supplies.

Its purpose was straightforward: provide the United States with an emergency stockpile of crude oil that could be released if supplies were suddenly threatened.

More than 50 years later, that safety net is looking increasingly fragile.

Depleted levels

The SPR has fallen to around, and now below, 300 million barrels — its lowest level since the early 1980s. The decline follows a succession of major releases, including the huge drawdown ordered in 2022 to help counter the surge in oil prices following Russia’s invasion of Ukraine.

The problem is not simply that America has less oil available during an emergency. The crude is stored deep underground in enormous salt caverns, and repeatedly removing and replacing large quantities of oil creates additional engineering and operational challenges.

Concerns have been raised that allowing inventories to fall too far could complicate the safe and efficient operation of some caverns.

Collapse

That does not mean the underground storage sites are on the verge of collapse. The SPR was specifically designed around the properties of salt formations, and the facilities are subject to extensive monitoring and maintenance.

But the reserve was never intended to be routinely used as a tool for managing ordinary fluctuations in oil prices.

Rebuilding it is also a slow process. Buying hundreds of millions of barrels requires money, suitable crude and sufficient time to inject it back into the caverns. The infrastructure itself must also remain operational.

That leaves Washington facing an uncomfortable dilemma. The SPR exists precisely to be used during an energy crisis.

But if it is drawn down too aggressively, America risks weakening the very emergency insurance policy created in 1975 to protect it.

The strategic question is no longer simply how much oil America has — but how much of its emergency reserve it can safely afford to use.

Deal or No Deal – The President of The United States and his Team Tease an Iran Deal, Markets Soar — Again. And Then Nothing. Why Does This Keep Happening?

Deal or no deal?

It has become an increasingly familiar pattern: Donald Trump hints that an agreement with Iran is close, investors breathe a sigh of relief, oil prices fall and stock markets jump — only for the promised breakthrough to fail to materialise. Why?

Deal or no deal

This week (early-August 2026) was another example. Trump and members of his administration suggested that progress towards an agreement involving Iran and the Strait of Hormuz could come within days.

Markets responded enthusiastically, betting that a deal would reduce the risk of prolonged conflict and ease pressure on global energy supplies.

Yet no comprehensive agreement appeared. Iran subsequently said direct talks with Washington would not take place while it considered the existing interim arrangement to be breached.

So why does it keep working?

Because financial markets trade expectations, not facts. The possibility of peace is enormously valuable when war threatens oil supplies, inflation and global growth.

Algorithms and traders react within seconds to headlines containing words such as “deal”, “ceasefire” or “agreement”.

Oil falls, equities rise and the economic relief can be priced in long before diplomats have actually agreed anything.

Loop of distrust

There is also a dangerous feedback loop. If markets repeatedly reward optimistic statements, there is little immediate financial incentive for politicians to stop making them.

Reports have previously documented dozens of occasions on which Trump suggested an Iran agreement was imminent without a final deal emerging.

Unhealthy relationship

That does not prove deliberate market manipulation. But it does expose a deeply unhealthy relationship between political rhetoric and financial markets.

Peace should be based on verified agreements, not carefully timed hints.

When a presidential statement can erase billions of dollars of perceived risk from markets before a single binding document exists, investors are effectively trading political promises.

And when those promises repeatedly fail to arrive, the credibility of both the politician and the market reaction suffers.

Shouldn’t markets price reality?

Not headlines. And certainly not hype.

Can U.S. markets ever fail… I wonder?

Europe goes all out on drones

Drone investment by the EU

Europe’s accelerating bet on drone technology marks one of the most significant strategic pivots in its modern defence posture.

After years of rebuilding military capacity in response to Russia’s invasion of Ukraine, European governments are now converging on drones and autonomous systems as the backbone of future security planning.

The shift is rapid, coordinated, and backed by unprecedented investment.

NATO

Over recent weeks, NATO, the U.K., Germany and major defence-tech firms have all announced large-scale programmes centred on drones.

NATO’s new initiative commits allies to more than $40 billion in counter‑drone capabilities over five years, reflecting Secretary General Mark Rutte’s assessment that drones have “fundamentally altered” modern warfare.

The U.K.’s Defence Investment Plan allocates £5 billion to a national drone transformation programme, while Germany has moved to procure 50,000 drones for Ukraine—an order that underscores how battlefield lessons from Ukraine are shaping procurement across the continent.

Lesson

Those lessons are clear: low‑cost, AI‑enabled drones can gather intelligence, extend the reach of conventional weapons, and operate effectively even in contested electronic environments.

Companies such as Auterion are developing operating systems that allow drones to strike targets despite jamming, navigate below the radio horizon, and eventually operate in coordinated swarms.

AI enabled

This software‑first approach signals a broader trend: Europe’s defence industry increasingly sees autonomy, AI, secure communications, and electronic warfare as central to future military capability.

Investment boom

The investment boom is also reshaping Europe’s defence‑tech sector. Venture funding has surged from €200 million in 2021 to €2.6 billion in 2025, and firms like Munich‑based Helsing—now valued at $18 billion—are emerging as continental champions in autonomous defence systems.

Europe’s big bet on drones is ultimately a bet on a new model of warfare: networked, data‑driven, and increasingly autonomous.

It reflects both urgency and ambition as the continent adapts to a rapidly changing security landscape.

THE WIDER FALLOUT: How a Prolonged U.S.–Iran War Radiates Through the Global Economy

War in Iran Global Fallout Effects

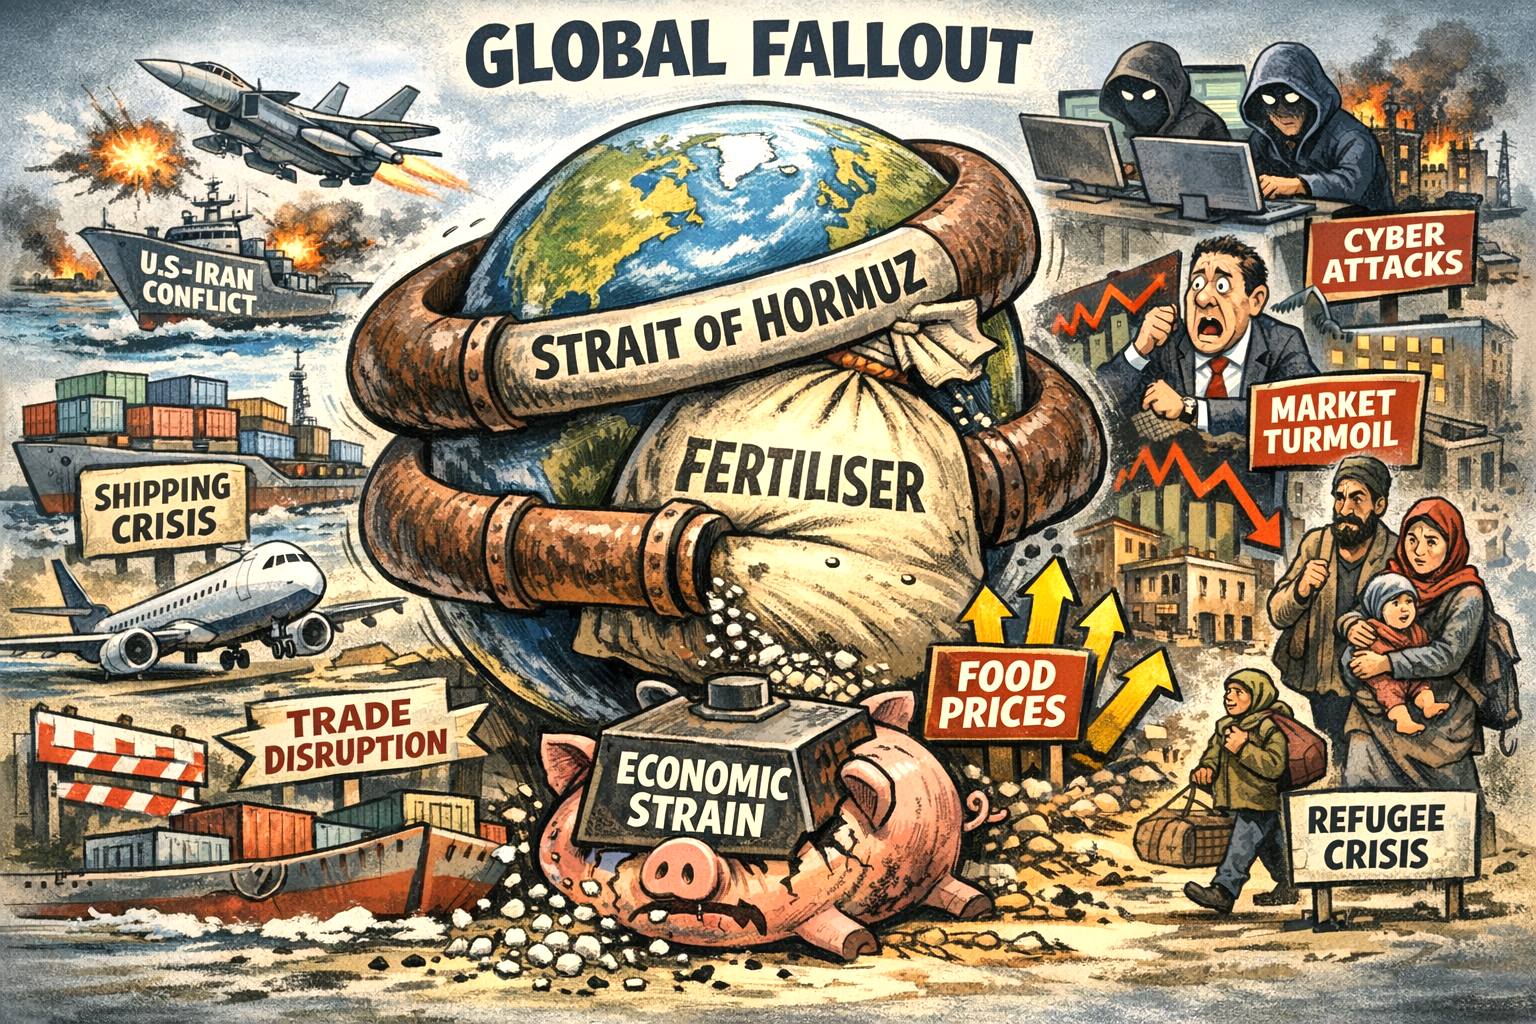
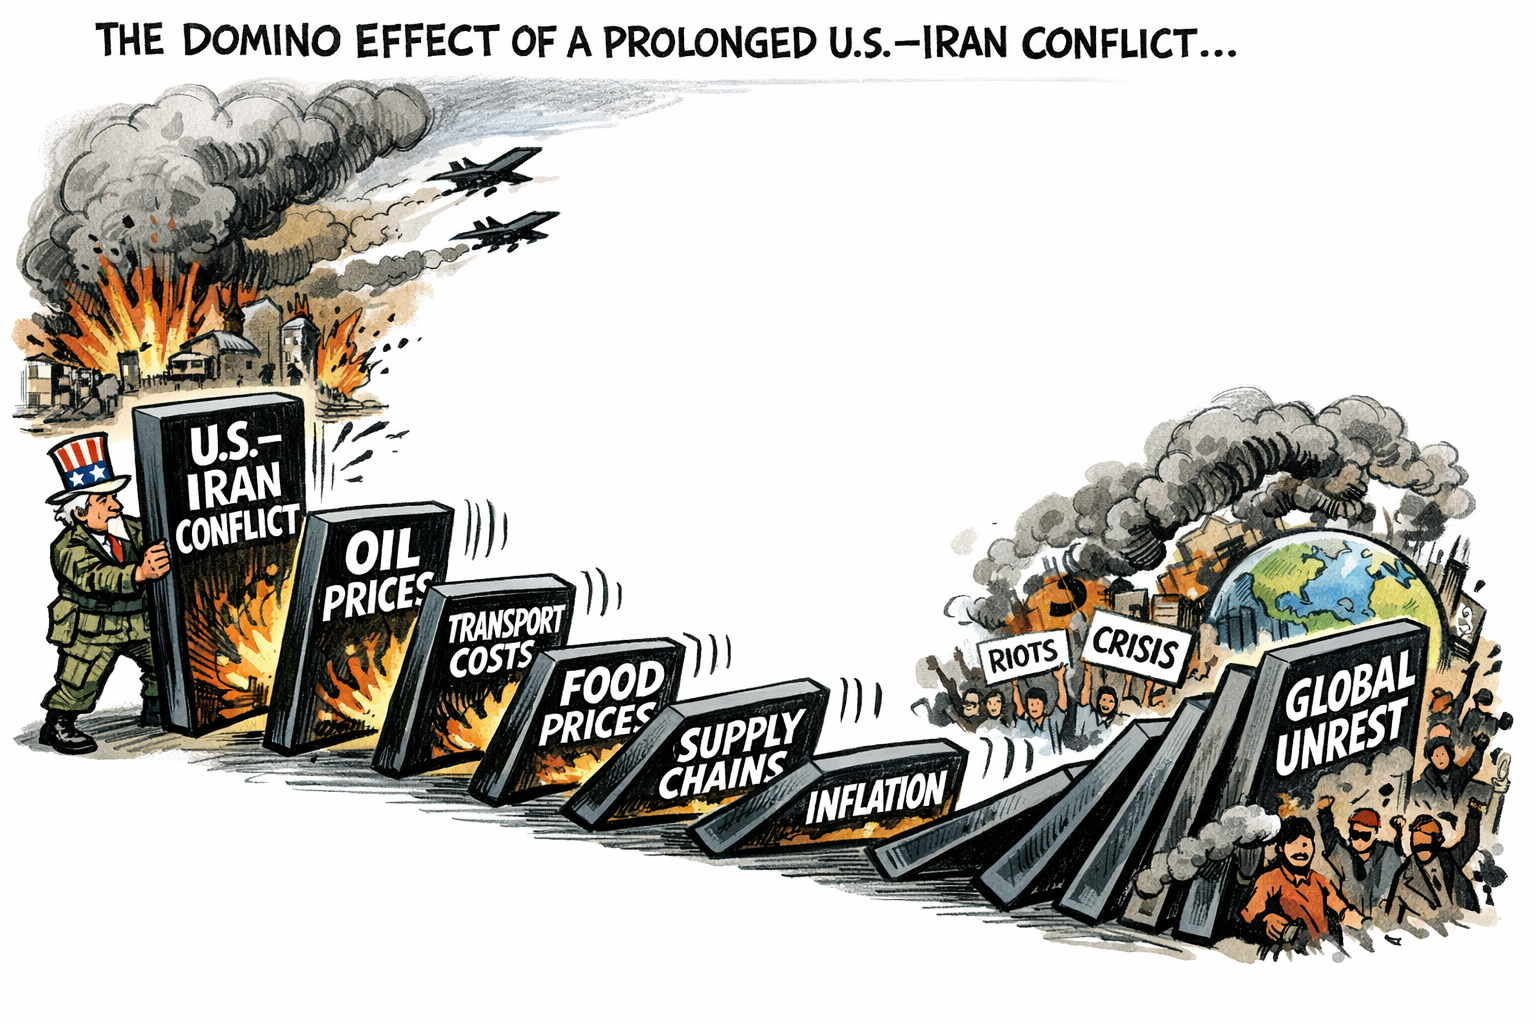
If the U.S.–Iran conflict drags on for weeks or months, the global impact will extend far beyond oil markets. Energy prices are only the first domino.

The deeper, more destabilising effects emerge through shipping disruption, fertiliser shortages, food‑price inflation, financial volatility, cyber escalation, and regional political instability.

For the UK — already wrestling with structural food‑system fragility — the conflict becomes a real‑world stress test.

This report outlines 15 potential major knock‑on effects that would shape the global economy if the conflict becomes protracted.

1. Global Shipping Disruption

The Strait of Hormuz is not just an oil artery; it is a global shipping chokepoint. As vessels reroute or halt operations:

  • Container shipping delays spread across Asia, Europe and the Gulf.
  • War‑risk insurance premiums spike for all vessels.
  • Freight costs rise, feeding into non‑energy inflation.

This is the mechanism by which a regional conflict becomes a global economic event.

2. Aviation and Travel Disruption

Iranian retaliation has already included strikes on Gulf airports and hotels. If this continues:

  • Airlines reroute or cancel flights across the Gulf, South Asia and East Africa.
  • Longer flight paths increase fuel burn and fares.
  • Tourism in the UAE, Oman, Bahrain and potentially Turkey contracts sharply.

Aviation is one of the fastest channels through which geopolitical instability hits consumers.

3. Financial Market Volatility

Markets dislike uncertainty, and this conflict delivers it in abundance.

  • Investors flee to gold, the dollar and U.S. Treasuries.
  • Emerging markets face capital outflows.
  • Equity volatility rises in shipping, aviation and manufacturing sectors.

The longer the conflict persists, the more entrenched this volatility becomes.

4. Fertiliser Disruption: The Hidden Trigger

Over one‑third of global fertiliser trade moves through the Strait of Hormuz. With shipments stranded:

  • Urea, ammonia, phosphates and sulphur prices surge.
  • Farmers worldwide face higher input costs.
  • Lower fertiliser availability leads to reduced crop yields.

This is the beginning of a food‑system shock that unfolds over months, not days.

5. Global Food‑Price Inflation

As fertiliser shortages ripple through agriculture:

  • Wheat, rice, maize and oilseed yields fall.
  • Livestock feed becomes more expensive, pushing up meat, dairy and egg prices.
  • Food‑importing regions face acute pressure.
  • Grain futures markets become more volatile.

This is how a conflict becomes a global cost‑of‑living crisis.

UK Exposure

The UK is particularly vulnerable because:

  • It imports a large share of its fertiliser and food.
  • Its agricultural sector is energy‑intensive.
  • Supermarket supply chains are sensitive to freight and insurance costs.

Bread, cereals, dairy and meat are the first categories to feel the squeeze.

6. Supply Chain Strain Beyond Food and Energy

A prolonged conflict disrupts:

  • Petrochemicals
  • Plastics
  • Fertilisers
  • Industrial metals
  • Gulf‑based manufacturing and logistics

This feeds into higher costs for everything from packaging to electronics.

7. Corporate Investment Freezes

Businesses hate uncertainty. Expect:

  • Delays or cancellations of Gulf megaprojects.
  • Slower investment in petrochemicals, logistics and tech hubs.
  • Reduced appetite for Gulf‑exposed assets.

This undermines diversification efforts like Saudi Vision 2030.

8. Cyber Escalation

Iran has a long history of cyber retaliation. Likely developments include:

  • Attacks on Western banks, utilities and government systems.
  • Disruptions to Gulf infrastructure, including airports and desalination plants.
  • Rising cybersecurity costs for businesses globally.

Cyber conflict is asymmetric, deniable and cheap — making it a likely pressure valve.

9. Regional Political Destabilisation

The killing of senior Iranian leadership has already shaken the region.

Possible outcomes include:

  • Internal instability within Iran.
  • Escalation involving Hezbollah, Iraqi militias, Syrian factions and the Houthis.
  • Pressure on Gulf monarchies if civilian infrastructure continues to be targeted.

This is where the conflict risks widening beyond its initial theatre.

10. Migration and Humanitarian Pressures

If the conflict intensifies:

  • Refugee flows from Iran, Iraq and Syria could rise.
  • Europe — especially Greece, Turkey and the Balkans — faces renewed border pressure.
  • Humanitarian budgets shrink as Western states divert funds to defence.

This adds a political dimension to the economic fallout.

11. Insurance Market Stress

War‑risk insurance is already spiking.

Expect:

  • Higher premiums for shipping, aviation and energy infrastructure.
  • Reduced insurer appetite for Gulf‑exposed assets.
  • Knock‑on effects on global trade costs and consumer prices.

Insurance is a silent amplifier of geopolitical risk.

12. Higher Global Borrowing Costs

Sustained conflict spending creates:

  • Budgetary strain for the U.S., UK, EU and Gulf states.
  • Reduced fiscal space for domestic programmes.
  • Higher global borrowing costs as markets price in sustained uncertainty.

This tightens financial conditions worldwide.

13. Pressure on Emerging Markets

Countries heavily reliant on imported energy or food face:

  • Worsening trade balances
  • Currency depreciation
  • Higher inflation
  • Greater risk of sovereign stress

This is especially acute in South Asia, North Africa and parts of Latin America.

14. Strain on Multilateral Institutions

A prolonged conflict diverts attention and resources from:

  • Climate finance
  • Development aid
  • Humanitarian relief
  • Global health programmes

Institutions already stretched by Ukraine, Gaza and climate disasters face further overload.

15. The Strategic Reordering of Alliances

A drawn‑out conflict may accelerate geopolitical realignment:

  • Gulf states hedge between Washington and Beijing.
  • India and Turkey pursue more independent foreign policies.
  • Europe faces renewed pressure to define its own security posture.
  • Russia benefits from higher energy prices and Western distraction.

This is the long‑term consequence: a shift in the global balance of power.

Conclusion: A Conflict That Radiates Far Beyond Oil

If the U.S.–Iran war limps on, the world will feel it in supermarket aisles, shipping lanes, financial markets and political systems.

The most consequential knock‑on effect is not oil — it is fertiliser. That is the hinge on which global food security turns.

For the UK, the conflict exposes the fragility of a food system dependent on imports, long supply chains and energy‑intensive agriculture.

This is not just a Middle Eastern conflict. It is a global economic event in slow motion.

And who says we don’t need oil still!

China’s restriction of rare earth materials hurts

Chinas rare earth material dominance

China’s recent export restrictions on rare earth elements are sending shockwaves through multiple industries worldwide.

As the curbs continue to take effect, sectors reliant on these critical minerals—including automotive, defence, and clean energy—are beginning to feel the strain.

China controls about 60–70% of global rare earth production and nearly 90% of the refining capacity.

Even when rare earths are mined elsewhere, they’re often sent to China for processing, since few countries have the infrastructure or environmental tolerance to handle the complex and polluting refining process.

In April 2025, China introduced export controls on seven key rare earth elements and permanent magnets, citing national interests and responding to rising trade tensions—particularly with the U.S.

Automotive industry in crisis

The auto sector is among the hardest hit. Rare earth elements are essential for both combustion engines and electric vehicles, particularly in the production of magnets used in motors and batteries.

European auto suppliers have already reported production shutdowns due to dwindling inventories.

Germany’s car industry, a global powerhouse, has reportedly warned that further disruptions could bring manufacturing to a standstill.

Japan’s Nissan and Suzuki have also expressed concerns, with Suzuki reportedly halting production of its Swift model due to shortages.

Defence and technology sectors at risk

China’s dominance in rare earth refining, controlling nearly 90% of global capacity, poses a strategic challenge for defense industries.

The U.S. military relies heavily on these materials for missile guidance systems, radar technology, and advanced electronics.

With nearly 78% of defence platforms dependent on Chinese-processed rare earths, the restrictions expose vulnerabilities in national security.

Clean energy ambitions under threat

The clean energy transition depends on rare earths for wind turbines, solar panels, and electric vehicle batteries.

China’s curbs threaten global efforts to reduce carbon emissions, forcing countries to scramble for alternative sources. India’s electric vehicle sector, for instance, faces potential setbacks as manufacturers struggle to secure supplies.

As industries grapple with these disruptions, governments and corporations are urgently seeking solutions. Whether through diplomatic negotiations or investment in domestic rare earth production, the race is on to mitigate the fallout from China’s tightening grip on these critical resources.

Several countries have significant rare earth reserves and can supply these materials in high quantities.

Top rare earth materials suppliers

China – The dominant player, with 44 million metric tons of reserves.

Brazil – Holds 21 million metric tons of rare earth reserves.

Vietnam – Has 22 million metric tons, making it a rising supplier.

India – Contains 6.9 million metric tons.

Australia – A key producer with 5.7 million metric tons.

Russia – Holds 10 million metric tons.

United States – While not a leading producer, it has 1.8 million metric tons.

Greenland – An emerging supplier with 1.5 million metric tons.

China remains the largest supplier, but countries like Brazil, Vietnam, and Australia are working to expand their production to reduce reliance on Chinese exports.

Ukraine?

Ukraine reportedly has significant reserves of rare earth elements, including titanium, lithium, graphite, and uranium. These minerals are crucial for industries such as defence, aerospace, and green energy.

However, the ongoing conflict with Russia has disrupted access to many of these deposits, with some now under Russian control.

Despite these challenges, Ukraine is being considered for strategic raw material projects by the European Union, aiming to strengthen supply chains and reduce reliance on China. The country’s mineral wealth could play a key role in post-war recovery and global supply diversification

Greenland?

Greenland is emerging as a key player in the global rare earth supply chain. The European Union has recently selected Greenland for new raw material projects aimed at securing critical minerals.

The island holds significant deposits of rare earth elements, including graphite, which is essential for battery production.

However, Greenland faces challenges in developing its rare earth industry, including harsh terrain, environmental concerns, and geopolitical tensions.

The U.S. and EU are keen to reduce reliance on China, which dominates rare earth processing, and Greenland’s resources could play a crucial role in this effort.

Greenland has indicated it has little desire to be transformed into a mining territory. It could have little choice.

Canada?

Canada is emerging as a significant player in the rare earth supply chain. The country has over 15.2 million tonnes of rare earth oxide reserves, making it one of the largest known sources globally.

Recently, Canada opened its first commercial rare earth elements refinery, marking a major step toward reducing reliance on Chinese processing.

The facility, located in Saskatchewan, aims to produce 400 tonnes of neodymium-praseodymium (NdPr) metals per year, enough for 500,000 electric vehicles annually.

Additionally, Canada is investing in critical minerals infrastructure to unlock rare earth development in Northern Quebec and Labrador.

The government has allocated $10 million to support mining projects, including the Strange Lake Rare Earth Project, which contains globally significant quantities of dysprosium, neodymium, praseodymium, and terbium.

Rare earth materials are a necessity for our modern technological lives – big tech tells us this. The hunger for these products needs to be fed, and China, right now, does the feeding.

And the beast needs to be fed.

From Missiles to Tariffs: A desensitised stock market faces Trump’s new world

Markets desensitised to U.S. policy making

In years past, the mere hint of U.S. airstrikes or heightened geopolitical tension would send global stock markets into panic mode.

Yet, following President Trump’s re-election and his increasingly aggressive foreign policy stance, investor reactions have become notably muted.

From missile strikes on Iranian nuclear sites to an orchestrated ceasefire between Iran and Israel, markets have barely flinched. The question arises: are investors becoming desensitised to Trump’s geopolitical theatre?

Take the latest skirmish between Iran and Israel. After nearly two weeks of missile exchanges, Trump’s announcement of a ‘complete and total ceasefire’ barely nudged the S&P 500.

That calm came despite the U.S. launching pre-emptive strikes on Iranian facilities and absorbing retaliatory attacks on its military base in Qatar.

In another era, or under a different administration even, such developments might have triggered a broad risk-off sentiment. Instead, Wall Street just shrugged.

One reason may be fatigue. Trump’s approach – rife with tariffs, sanctions, and sudden reversals – has bred a kind of market immunity.

Investors, well-versed in the rhythm of Trump’s provocations, have begun treating them as background noise. His revived tariff agenda, particularly the threats aimed once again at China and EU auto imports, has likewise failed to prompt major selloffs.

Similarly, the ongoing Russia-Ukraine conflict, once a source of intense volatility, now registers as a strategic stalemate in the market’s eyes.

While Trump’s rhetoric surrounding Ukraine has shifted unpredictably, investors appear more focused on earnings, inflation data, and central bank signals than on diplomatic fallout and war!

This is not to suggest markets are indifferent to geopolitical risk, but rather that they’ve adapted. Algorithmic trading models may be increasingly geared to discount Trump’s headline-grabbing tactics, while institutional investors hedge through gold, volatility indices, or energy plays without dumping equities outright.

Critics argue this detachment is dangerous. Should a flashpoint spiral out of control, be it over Hormuz, Ukraine, or Taiwan, the slow-boiling complacency could leave portfolios badly exposed.

Still, for now, Trump’s policies are being priced in not with panic, but with complacency maybe.

The real story may not be what Trump does next, but how long the markets can continue to look away.

Trump announces he had brokered ceasefire between Israel and Iran?

Tensions between Israel and Iran reached a boiling point after 12 days of cross-border missile and drone strikes.

The situation escalated further when U.S. forces under President Trump launched targeted airstrikes on key Iranian nuclear sites, Fordow, Natanz, and Isfahan, prompting a direct Iranian missile response on a U.S. base in Qatar.

In a dramatic turn, President Trump announced what he called a ‘Complete and Total CEASEFIRE‘ – announced on Truth Social. According to Trump’s plan, Iran would begin the ceasefire immediately, with Israel to follow 12 hours later.

The truce would reportedly be considered complete after 24 hours if all attacks stopped.

While Trump touted the ceasefire as a triumph of ‘peace through strength’, analysts questioned the ceasefire’s enforceability – especially since missile exchanges reportedly continued despite the announcement.

Nonetheless, Trump claimed credit for halting the region’s slide into all-out war without committing to prolonged U.S. military involvement.

Critics argue Trump’s strategy relies more on military pressure and media theatrics than diplomatic engagement.

Supporters counter that his boldness forced both sides to the table. Either way, the world is watching to see whether this fragile peace endures – or erupts again in fire.

If this turns out to be a masterstroke in political brinkmanship – hats off to Trump, I guess. Whichever way you look at it, the precision U.S. strike on Iran was exactly that – precision. And, you have to take note.

Iran has been weakened, and this may even influence Russia’s war on Ukraine. Hopefully Israel with Palestine too – regardless of stock market reaction.

And that has to be a good thing!

But has Israel finished their war?

Despite all the noise regarding stock market reaction, one thing is for certain – the anxiety and worry for the people of the Middle East is unquestionable.

It’s not a happy time.