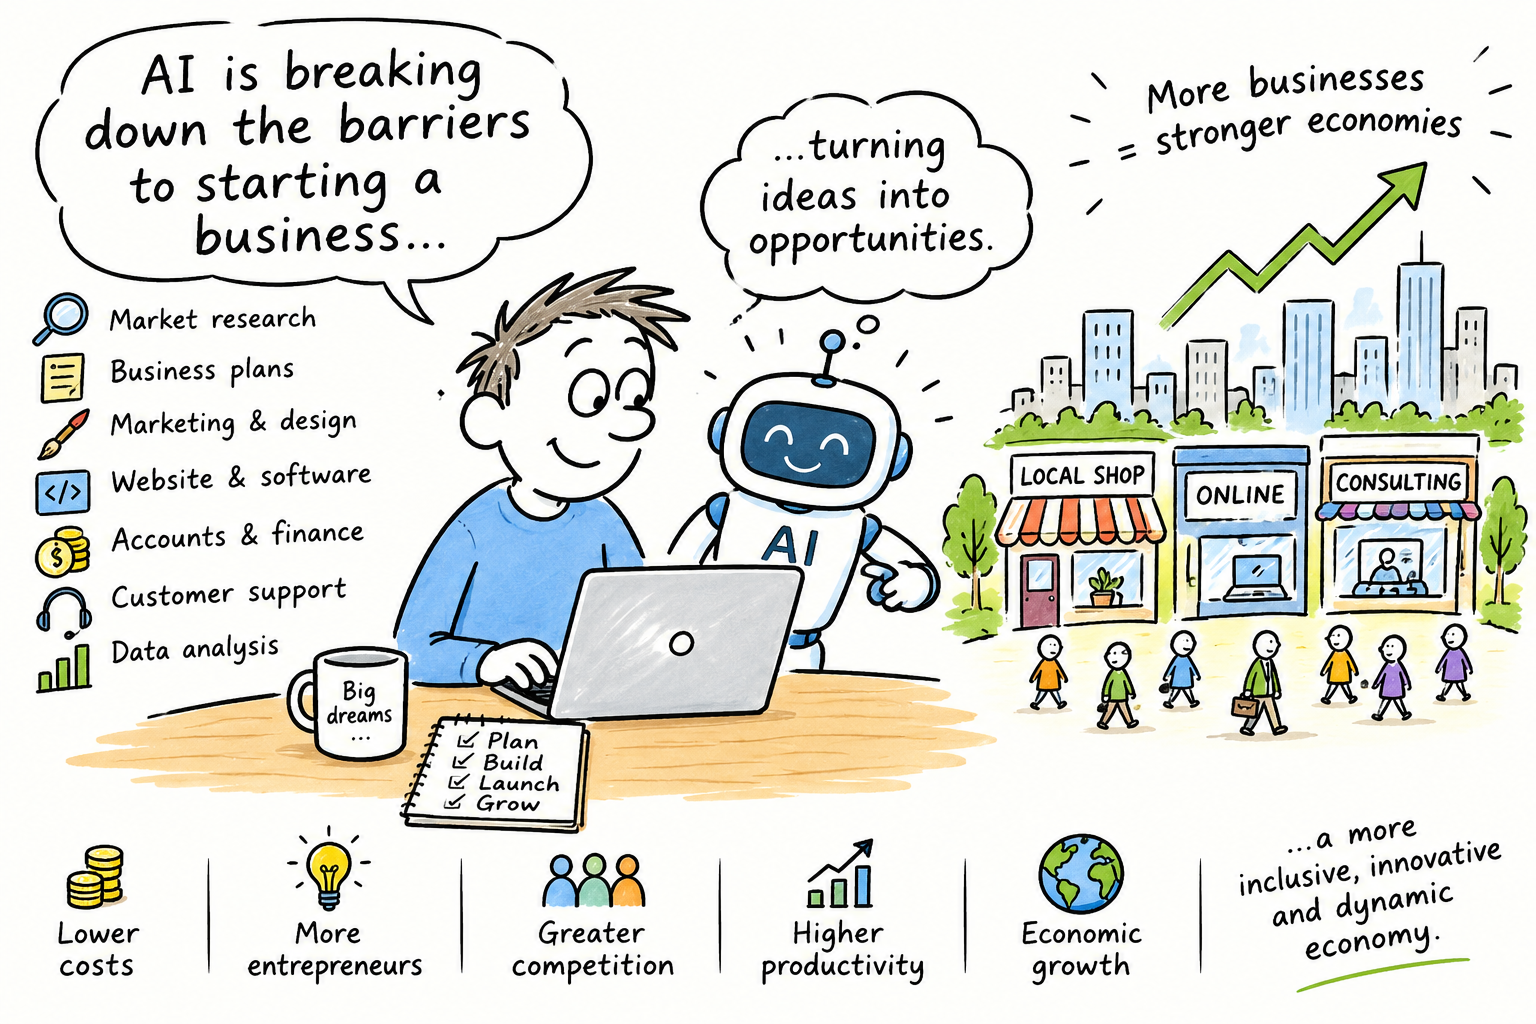
AI Is Breaking Down the Barriers to Starting a Business

The power of AI empowering business start-ups

Artificial intelligence is beginning to reshape the economics of starting and running a business.

AI is easily accessible

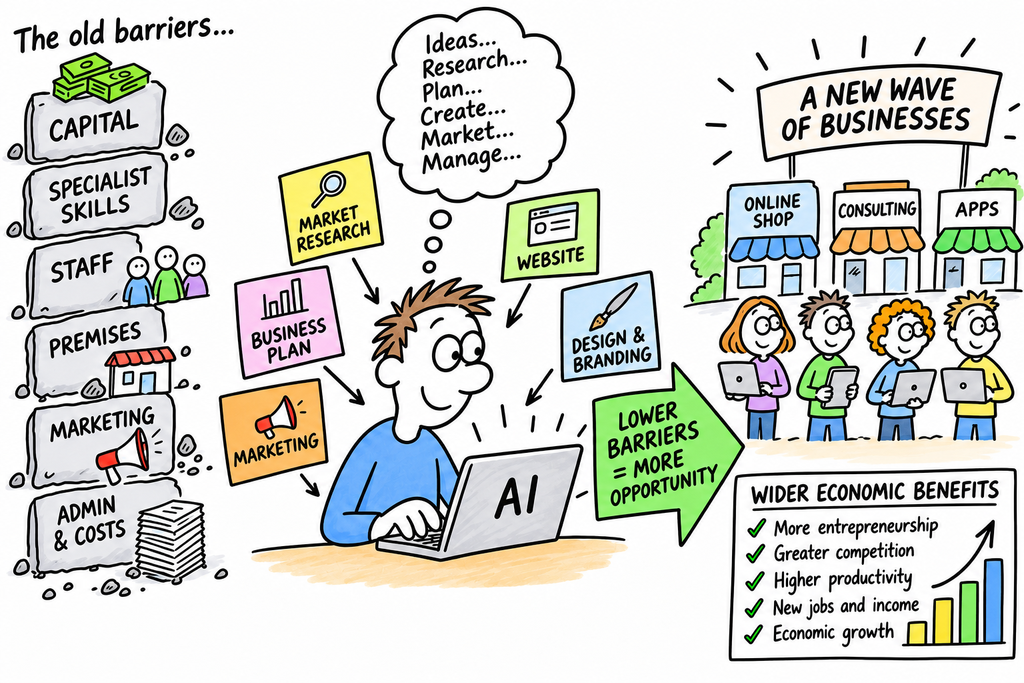
What once required substantial financial investment, specialist skills and a team of employees can increasingly be achieved by an individual with a computer, an internet connection and access to AI tools.

The implications could extend well beyond entrepreneurship, potentially changing productivity, employment, competition and economic growth.

Traditionally, starting a business involved considerable upfront costs. Entrepreneurs needed to invest in staff, premises, marketing, professional services, technology and administration, often before generating their first pound of revenue.

These expenses created significant barriers to entry, particularly for individuals without access to capital or business connections.

AI is changing this economic equation

An individual can now use AI to conduct market research, develop business plans, build websites, write software, produce marketing campaigns, analyse financial information and manage customer enquiries.

Tasks that previously required several employees or expensive external consultants can increasingly be handled by one person at a fraction of the cost.

This has the potential to create a new generation of micro-businesses, independent entrepreneurs and highly productive one-person companies.

Lower operating costs could allow businesses to become profitable with considerably less revenue than was previously necessary.

For the many

The wider economic consequences could be significant. If millions of individuals can establish businesses with relatively little capital, entrepreneurship could become a much more accessible route to generating income and creating employment.

Smaller businesses may also become more competitive, challenging established corporations that have traditionally benefited from economies of scale, larger workforces and greater financial resources.

But first we will have a period of transition and discovery.

Productive

There is also a potentially important productivity dividend. Businesses able to produce more with fewer employees could reduce operating costs, improve margins and increase output.

At a national level, this could contribute to economic growth without requiring the same expansion in the workforce.

For governments struggling with ageing populations, labour shortages and weak productivity, AI could become an increasingly important economic tool.
Saturation

However, there is another side to the equation. As the cost of establishing a business falls, competition will intensify.

Markets could become saturated with similar products and services, while automation may displace certain administrative, creative and professional roles.

The economic benefits will depend partly on whether new businesses and industries create sufficient opportunities to offset employment lost elsewhere.

Access to AI will also matter. If the technology becomes concentrated among a small number of powerful companies, the savings generated by automation may not be distributed evenly.

Nevertheless, AI could represent a significant democratisation of business ownership. The traditional advantages of capital, staffing and infrastructure may become less important, while creativity, commercial judgement and the ability to identify opportunities become increasingly valuable.

The Next Wave

The next wave of business creation may not come from large corporations investing billions, but from individuals using AI to build businesses that previously would have been financially impossible.

AI is not eliminating the risks of entrepreneurship. It is, however, dramatically reducing the cost of trying. That could have profound implications for the future structure of the global economy.
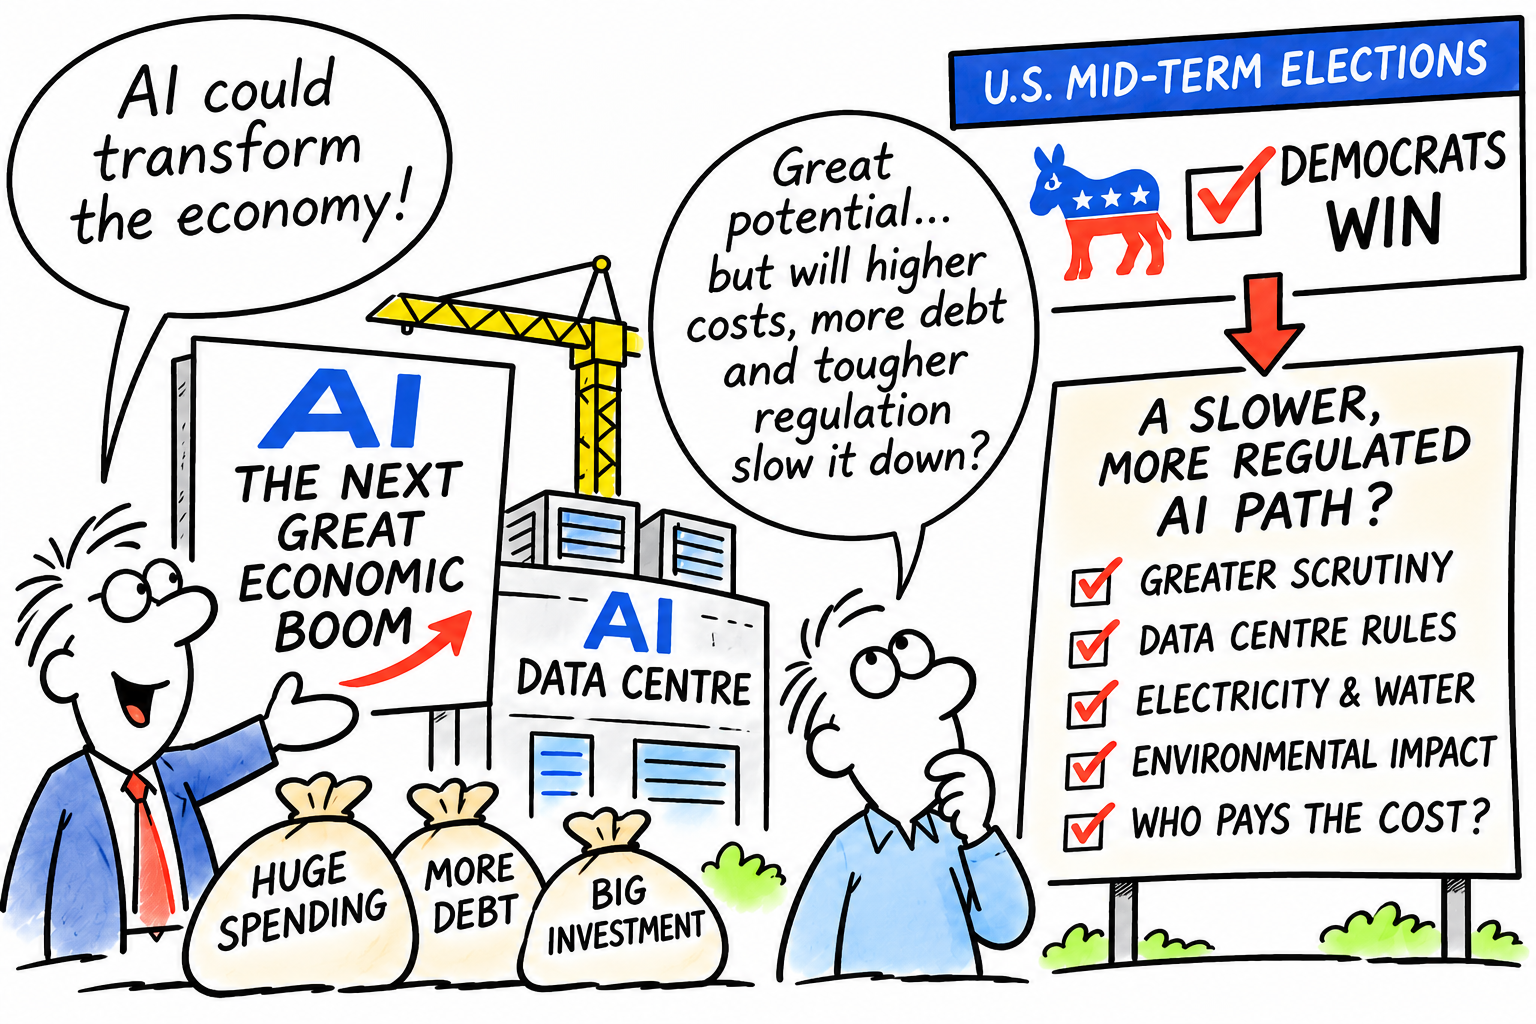
AI: The Next Great Economic Boom – But at What Financial and Economic Cost?

The artificial intelligence revolution continues to dominate financial markets, attracting extraordinary investment from some of the world’s largest technology companies.

Yet beneath the enthusiasm, a growing number of economic, financial and political concerns are emerging. While technology shares have recently staged a recovery, the fundamental questions surrounding the sustainability of the AI investment boom remain unanswered.

The central issue is becoming increasingly difficult to ignore: can the commercial returns from artificial intelligence justify the enormous cost of building the infrastructure required to support it?

An unprecedented investment programme

Microsoft, Amazon, Alphabet, Meta, Oracle and many others are committing hundreds of billions of dollars to data centres, specialist processors and supporting infrastructure. Their ambitions are substantial, with AI expected to transform productivity, business operations, healthcare, manufacturing and countless other industries.

However, the scale of expenditure is creating growing financial pressures. The Bank of England has highlighted the increasing reliance on borrowing to finance AI infrastructure. Morgan Stanley reportedly estimated that global AI-related debt issuance had reached approximately $450 billion by early September 2026, more than double the total for the whole of 2025.

The Bank has also highlighted the growing involvement of private credit and more complicated financing arrangements. These developments raise questions about where the financial risks ultimately sit, particularly if expected commercial returns fail to materialise.

Debt itself is not necessarily a problem. Large companies routinely borrow to finance expansion. The concern is whether the investment will generate sufficient cash flow to service that borrowing while continuing to fund further development.

The returns question

Technology companies are investing on the assumption that AI adoption will eventually produce enormous commercial opportunities. However, the gap between infrastructure expenditure and demonstrable financial returns remains an important consideration.

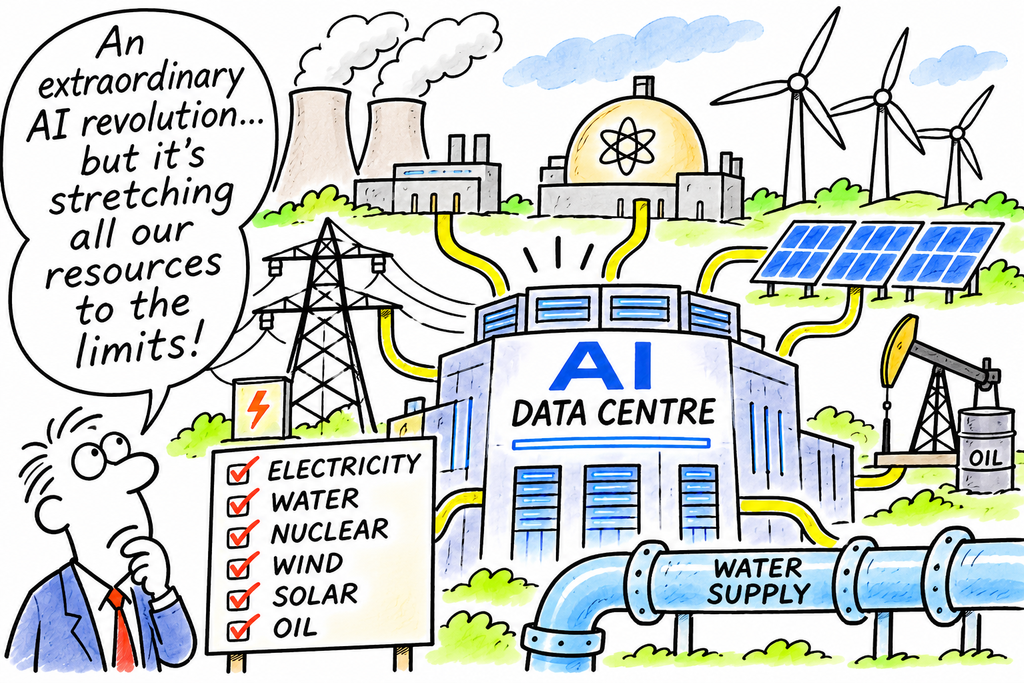
Data centres are expensive to construct and operate. Specialist chips require continual investment, while electricity, cooling, water and network infrastructure add further costs.

The industry must also contend with rapidly changing technology. Today’s expensive processors and facilities could become less competitive as more efficient systems emerge.

There is also the possibility that investment is running ahead of commercial demand. Businesses are experimenting with AI, but widespread adoption does not automatically translate into sufficient revenue to justify the enormous infrastructure costs.

Investors will increasingly want evidence that AI-related revenues and productivity improvements are keeping pace with capital expenditure.

Chinese competition adds another complication

Competition from China represents another potential challenge.

Chinese developers have demonstrated that increasingly capable AI models can be produced using more cost-efficient approaches. This could put pressure on the pricing structures of American technology companies.

If businesses can access capable AI systems at considerably lower prices, the commercial returns expected by companies investing heavily in infrastructure could be affected.

The AI industry may ultimately become much larger, but that does not guarantee that every company currently investing in it will generate attractive returns.

The political landscape changes

The U.S. midterm elections have introduced another dimension.

Democrats have secured control of both the House of Representatives and the Senate, creating a more challenging political environment for President Trump during the remainder of his term.

Technology companies could face increased scrutiny over data-centre construction, electricity consumption, environmental considerations, water supplies and AI regulation.

There are already disagreements in Washington over who should pay for the additional electricity infrastructure required by data centres. Some lawmakers want technology companies to shoulder more of the cost rather than passing it on to ordinary electricity consumers.

These concerns are particularly relevant in states such as Texas, where substantial AI infrastructure investment is planned.

Greater political scrutiny does not necessarily mean that AI development will stop. However, additional regulation, planning restrictions and infrastructure costs could slow the expansion or reduce the profitability of some projects.

Why is the Nasdaq recovering?

Despite these concerns, technology shares have recently demonstrated considerable resilience.

On 3rd November 2026, the Nasdaq gained approximately 0.83%, supported by a recovery in major AI and semiconductor shares. Nvidia, Broadcom and Micron were among the beneficiaries.

However, this recovery seemed to start ahead of the full midterm election results. Following the Democratic victories, global markets initially reacted negatively, reflecting concerns about potential regulatory changes and the future pace of AI infrastructure investment.

The recovery in technology shares should therefore not be interpreted as evidence that the underlying problems have disappeared.

Investors may be buying following recent declines, taking advantage of lower valuations or closing short positions. Such activity can produce substantial market recoveries without any corresponding improvement in the industry’s financial fundamentals.

A defining moment for investors

The AI revolution could ultimately prove to be one of the most important technological developments in modern economic history. Its potential should not be underestimated.

However, technological success and investment success are not necessarily the same thing.

The companies building the infrastructure must demonstrate that their investments can generate sustainable revenues, adequate cash flow and acceptable returns. Meanwhile, increasing borrowing, competition, resource constraints and political intervention could complicate that process.

For investors, the next stage of the AI story may be less about excitement surrounding technological possibilities and more about financial discipline.

Capital expenditure, debt issuance, free cash flow, AI-related revenues and institutional investment decisions deserve particularly close attention.

The wider economic consequences also matter. If AI delivers the productivity improvements its supporters anticipate, the benefits could extend well beyond the technology sector.

Conversely, if investment expectations become disconnected from commercial reality, the financial consequences could reach credit markets and the wider economy.

The AI revolution may be gathering momentum, but the investment boom financing it is approaching an important test.

The question is no longer simply how transformative AI might become. It is whether the extraordinary sums being committed today can generate sufficient economic value tomorrow.

For investors, that distinction could become increasingly important.

When Water Becomes the Weak Link in Europe’s Energy System

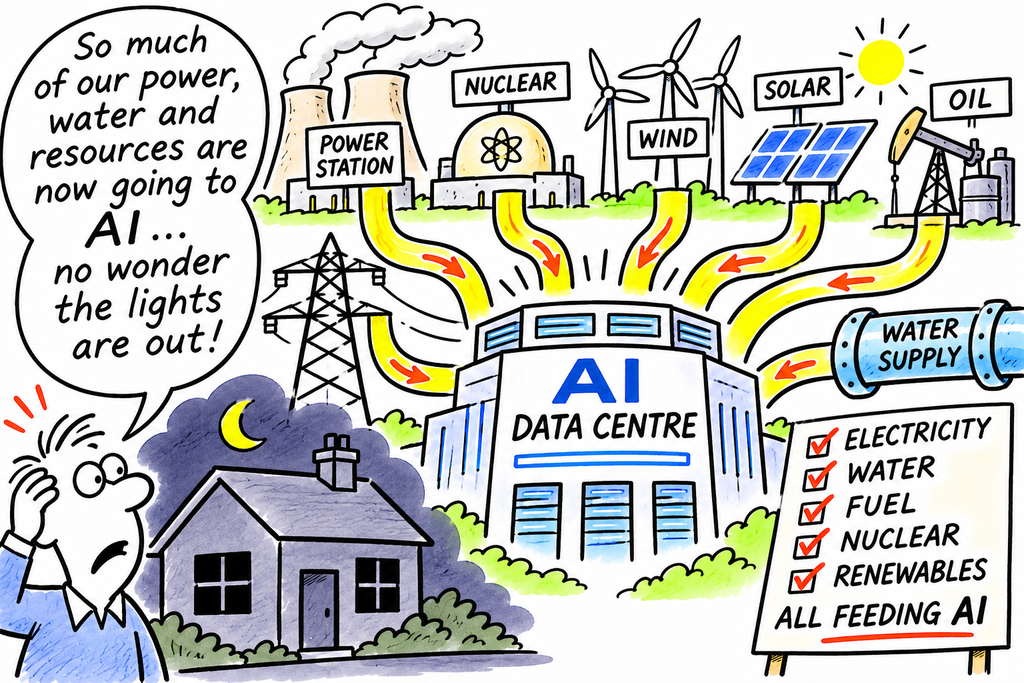
Energy, AI, Data Centres, people and water!

Europe’s extraordinary summer heatwave is exposing an uncomfortable truth about modern energy systems: electricity may be generated from uranium, gas, coal, wind or sunlight, but much of the infrastructure still depends on something increasingly unreliable — water.

The Danube has become the most dramatic example. Romania has now shut down both reactors at its Cernavoda nuclear power station after the river fell to historically low levels. The plant normally supplies around a fifth of Romania’s electricity.

Hungary’s Paks nuclear station has also been operating at sharply reduced output as the Danube struggles to provide sufficient cooling water.

Emergency engineering measures have even been considered to raise water levels around the plant.

But this is not simply a Danube problem

France’s huge nuclear fleet is facing a different version of the same challenge. Several reactors have been shut down or had their output reduced because rivers and seawater have become too warm.

Nuclear plants need enormous quantities of cooling water, but environmental rules restrict how much additional heat can be discharged into rivers when their temperatures are already dangerously high.

As of 13th August 2026, almost 20% of French nuclear capacity was unavailable, with the heatwave expected to force further reductions.

Jellyfish blockage

France has also encountered a rather more bizarre cooling problem. At Gravelines, one of Europe’s largest nuclear stations, huge quantities of jellyfish clogged seawater intake systems, forcing three reactors temporarily offline.

Warmer seas may make such biological disruptions more frequent

Elsewhere, Italy, Poland and Slovenia have also experienced power-plant restrictions linked to low river levels or excessive water temperatures.

Slovenia’s Krško nuclear plant, for example, reduced output because of hydrological and meteorological conditions affecting the Sava River.

The problem extends beyond nuclear: coal, gas and other thermal power stations also require cooling, while drought reduces the water available for hydroelectric generation.

UK gas heats up

Britain has not escaped the problem. During an earlier heatwave, five major gas-fired power stations reportedly had to reduce output because high temperatures made cooling more difficult.

The UK grid has also been under unusual summer pressure as air-conditioning demand rises, power-plant efficiency is affected and electricity imports become more important.

The bigger warning

Climate change does not simply mean hotter weather. It means the simultaneous arrival of several stresses: higher electricity demand for cooling, lower river flows, warmer cooling water, drought, wildfires, reduced hydroelectric output and pressure on transmission infrastructure.

Irony

The irony is striking. We build power stations to protect society from the weather, yet increasingly extreme weather can interfere with the very systems designed to keep the lights on.

Europe’s energy challenge is therefore becoming a climate-and-water challenge as much as an electricity challenge.

Future power stations may need alternative cooling systems, greater water efficiency, more storage, stronger interconnections and a much wider mix of generation.

Water security

The lesson from this summer is uncomfortable but simple: energy security depends on water security too.

The Ed Miliband energy paradox: how Britain ended up paying France to take its power

UK energy paradox

If you are anything like me, you’re not wrong to feel that this is insane. On the face of it, Britain has:

  • Among the highest electricity prices in the developed world, especially for industry.
  • Growing periods of negative wholesale prices, where generators pay others to take power.

That combination is not just a glitch; it’s the product of how the UK has chosen to do net zero—through a tangle of subsidies, rigid contracts and a grid that was never upgraded to match the political ambition.

This is the Ed Miliband paradox: a “cheap renewables” story that somehow delivers some of the world’s most expensive power, and then occasionally becomes so oversupplied that we literally pay France and others to take it away.

What is actually happening when prices go negative?

Negative prices are not a metaphor. For several dozen hours already this year, the wholesale price of electricity in Britain has dropped below zero.

Generators effectively pay the system to keep running, and interconnectors export that surplus to countries like France, Holland and Belgium—sometimes with a “chunky payment” attached.

This happens when:

  • Supply massively exceeds demand—typically on windy, sunny, mild days when heating and cooling demand is low.
  • Certain generators cannot or will not switch off—because of technical constraints (nuclear, some gas) or because their subsidy contracts reward them for generating regardless of price.
  • The grid cannot move or store the surplus—limited storage, constrained transmission, and slow grid reinforcement mean power piles up in the wrong place at the wrong time.

In that moment, electricity stops being a valuable commodity and becomes a waste product that must be disposed of. Interconnectors to France and others are the “sewer pipe” for that surplus.

Why the UK is uniquely bad at this

Negative prices are not just a British phenomenon—Germany, Spain, the Netherlands and others have also seen record hours of sub‑zero prices as renewables surge. But the UK has managed to combine:

  • High average prices, especially for industry;
  • Frequent negative prices at the margin;
  • Huge policy costs loaded onto bills rather than general taxation.

That cocktail is the result of several design choices.

1. Subsidy structures that pay to generate, not to be useful

A big chunk of UK renewables is supported by:

In a negative price event, the market is screaming “stop generating”. But if your contract still pays you based on output, you have every incentive to keep going. The cost of paying someone else to take the power can be less than the subsidy you’d lose by switching off.

So the system ends up doing something perverse: it pays generators to keep producing power that nobody wants, and then pays other countries to take it away.

2. A grid built for yesterday, not for a renewables surge

The UK has poured money into generation capacity—offshore wind, solar, interconnectors—but has been slow, bureaucratic and under‑invested on:

  • Transmission upgrades—moving power from windy Scotland and the North Sea to demand centres in England.
  • Storage—batteries, pumped hydro, demand‑side response at scale.
  • Flexible backup—fast‑ramping gas, smart tariffs, and industrial load‑shifting.

When you bolt a 21st‑century renewables fleet onto a 20th‑century grid, you get congestion, curtailment and waste.

The system then has to pay wind farms not to generate in some regions, while importing power elsewhere. Negative prices are just the most visible symptom of that mismatch.

3. Political obsession with “headline capacity” over system design

Net zero politics has been sold as a race to headline numbers:

  • X gigawatts of offshore wind by year Y
  • Z per cent of power from renewables
  • “Clean power by 2030”

What has not been sold—or properly designed—is the system architecture that makes that capacity economically coherent: locational pricing, flexible demand, storage, and a planning regime that can actually deliver grid reinforcement on time.

Ed Miliband’s own Electricity Market Review explicitly rejected zonal pricing in favour of a reformed national price, arguing that a single price is “fairest” and better for investment. That sounds nice politically, but it hides the real cost of congestion and mis‑location.

Instead of prices signalling “don’t build another wind farm here until the grid is upgraded”, the system socialises the pain across everyone’s bills.

Why are we paying France?

Interconnectors are not inherently stupid. In a rational system, they:

  • Smooth out volatility—import when you’re short, export when you’re long.
  • Share capacity—you don’t need to build as much domestic backup if you can lean on neighbours.

The problem is that the UK has created a structure where:

  • We over‑generate at certain times because of rigid contracts and inflexible plant.
  • We lack storage and flexible demand to soak up that surplus domestically.
  • We then use interconnectors as a dumping ground, paying others to take power that our own consumers have already funded through subsidies and levies.

France, with its large nuclear fleet and different cost structure, can happily take that cheap or even “paid‑to-take” power, displacing its own generation and lowering its average costs.

Meanwhile, UK industry is paying power prices around 60 per cent higher than in France on average.

So, we (the UK) socialise the cost of building and subsidising the capacity, then export the benefit at a discount.

How did this policy architecture even get created?

This isn’t one bad decision; it’s a stack of incentives and political choices that line up in the worst possible way.

1. Short‑term politics, long‑term contracts

Governments of all colours wanted:

  • Quick, visible progress on renewables.
  • Private capital to fund it, not the state balance sheet.
  • Minimal upfront tax rises.

The answer was long‑term, legally binding contracts (RO, CfDs, capacity market) that shifted risk onto consumers via bills. Once signed, these contracts are hard to change without spooking investors or triggering compensation claims.

So ministers get the photo‑ops—“world‑leading offshore wind”, “clean power by 2030”—while the structural costs and distortions are baked in for decades.

2. Ideological framing: net zero as a moral crusade, not an engineering project

Net zero has been framed as a moral imperative first, an engineering challenge second. That has consequences:

  • Questioning the design is painted as questioning the goal.
  • Complex system trade‑offs are reduced to slogans about “cheap renewables” and “green jobs”.
  • Uncomfortable truths—like the need for gas backup, storage, and grid reform—are pushed into the technical long grass.

The result is a policy environment where it is easier to announce another offshore wind auction than to confront the messy, expensive business of rewiring the grid and redesigning market signals.

3. Regulatory fragmentation and institutional cowardice

Ofgem, National Grid ESO, the Department for Energy Security and Net Zero, the Treasury—each has a slice of the problem, but no one owns the whole system outcome.

  • Ofgem focuses on consumer protection and network costs, often slowing investment.
  • Treasury resists big upfront public spending on grid and storage, preferring “market‑based” fixes.
  • Ministers chase announcements that look good in manifestos.

No one is politically rewarded for saying: “We need to spend billions on grid reinforcement and storage now, or we’ll be paying France to take our power in five years.” So it doesn’t happen at the necessary scale.

Is this fixable, or are we stuck paying others to take our power?

It is fixable—but not with more of the same.

An honest, grown‑up approach would mean:

  • Rewriting incentives so generators are paid for being useful to the system, not just for raw output. That means tighter rules on when subsidies are paid during negative prices, and contracts that reward flexibility.
  • Accelerating grid and storage investment as national infrastructure, not an afterthought. That likely means more state involvement and faster planning, not just hoping private investors will do it.
  • Introducing stronger locational signals—whether full zonal pricing or something close to it—so that the cost of building in the wrong place is visible, not smeared across everyone’s bills.
  • Using interconnectors intelligently, not as a dumping ground: export surplus when it’s genuinely cheap, but don’t subsidise over‑generation just to keep contracts happy.

So how stupid is this policy?

On a technical level, the engineers keeping the lights on are doing miracles with the system they’ve been given. The stupidity sits higher up:

  • Designing a net zero pathway around rigid subsidies and under‑built infrastructure.
  • Refusing to confront the trade‑offs, then acting surprised when the physics bites back.
  • Allowing a political narrative of “cheap green power” to coexist with some of the highest industrial prices in the world and growing episodes of negative pricing.

The real scandal isn’t just that we pay France to take our power. It’s that British households and firms have already paid once—through levies and high tariffs—to build that surplus, and then pay again when the system has to bribe someone else to use it.

Work that one out…!

UK economy will be hit hardest by the U.S.-Israel Iran war warns the IMF

UK Economy damaged by U.S. Iran War

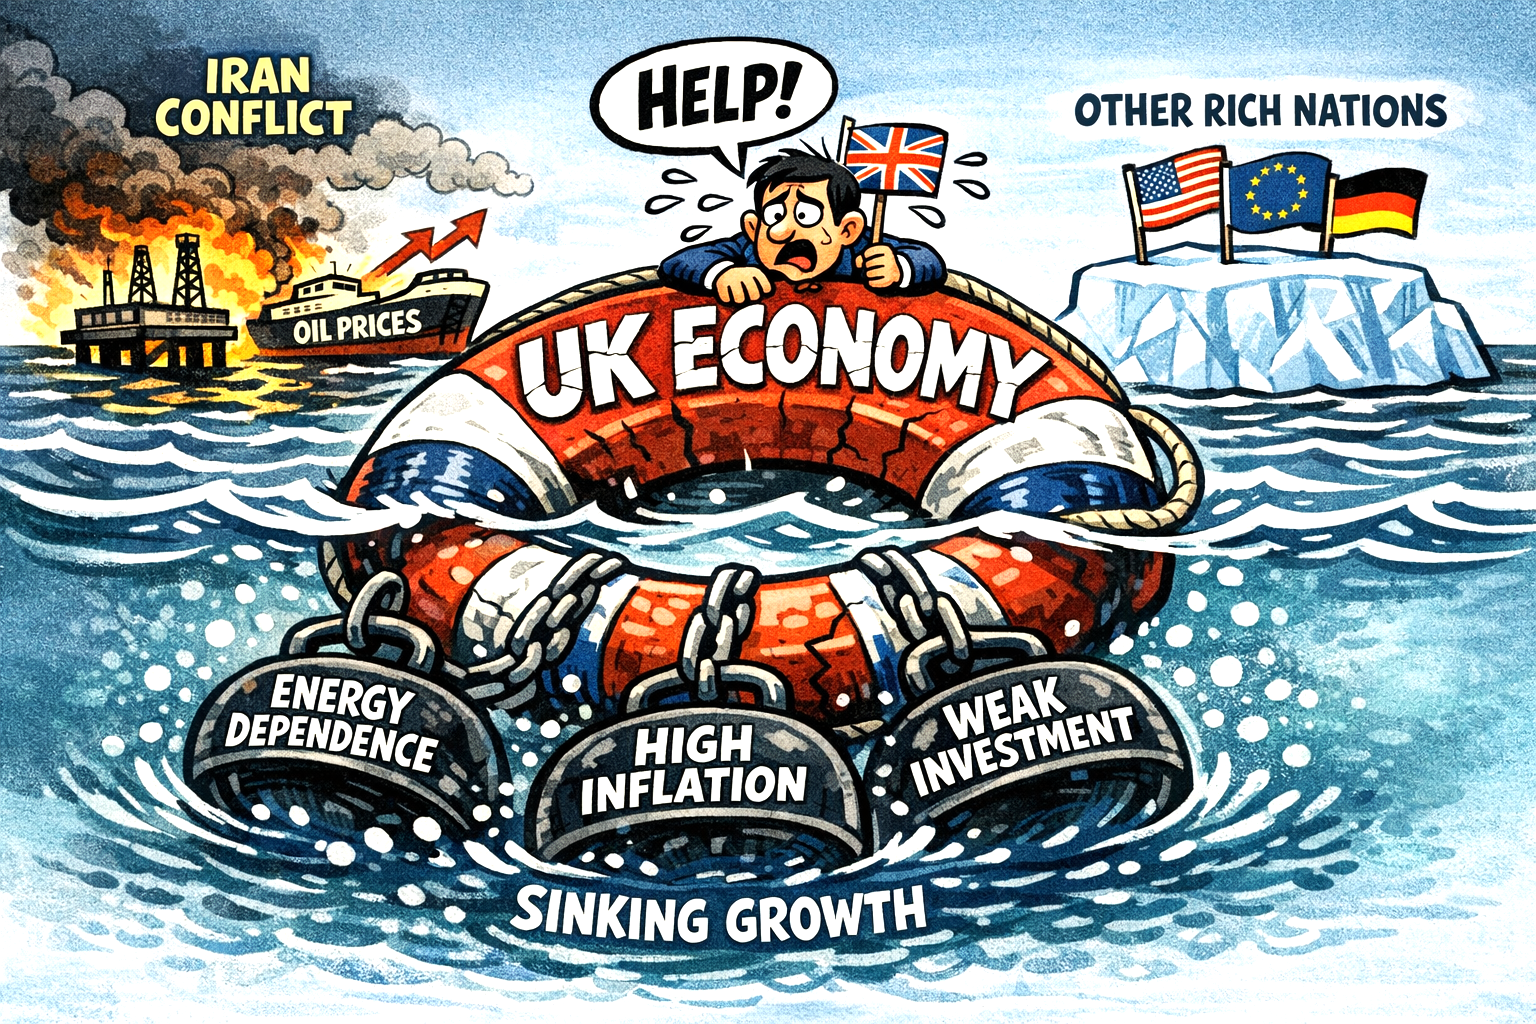
The IMF’s warning that the UK would suffer the sharpest growth hit among rich economies from an Iran‑related war is rooted in a simple structural reality.

Britain is unusually exposed to energy‑price shocks, yet unusually weak in the buffers that normally absorb them according to the IMF.

Why the UK will be hit harder than its peers

The UK enters this crisis with three vulnerabilities

  • High dependence on imported energy. North Sea output has declined for years, leaving Britain reliant on global LNG markets. When Middle Eastern supply is disrupted, LNG prices spike first and hardest. The U.S. and eurozone have deeper domestic energy bases or cheaper pipeline access.
  • A structurally fragile inflation profile. The UK’s inflation has been stickier than that of other G7 economies, driven by food, energy and services. A renewed oil shock feeds directly into household bills and transport costs, forcing the Bank of England to keep rates higher for longer.
  • Weak productivity and stagnant investment. Britain has less momentum to absorb an external shock. When energy prices rise, UK firms cut back faster, and consumers retrench more sharply.
  • UK Government policy. Ed Miliband and his ‘likely’ misguided staunch defence of Net Zero policies and expensive energy costs have left the UK seriously exposed to shocks – such as this.

The IMF’s logic

The Fund argues that a prolonged disruption in the Strait of Hormuz would push global oil prices sharply higher.

For the UK, this translates into

  • Higher wholesale gas costs, because LNG markets reprice off oil‑linked benchmarks.
  • A renewed inflation surge, delaying rate cuts and tightening financial conditions.
  • A squeeze on real incomes, hitting consumption—the UK’s main growth engine.
  • A fall in business investment, already one of the weakest in the OECD.

The IMF’s modelling suggests that the UK’s growth rate could fall more steeply than that of the U.S., Germany or France because those economies either have stronger industrial bases, more resilient energy systems or more fiscal space to cushion the blow.

The broader picture

This is less about geopolitics and more about structural brittleness. A global energy shock exposes the UK’s unresolved weaknesses: high import dependence, fragile inflation dynamics and a decade of under‑investment.

Tesla beats earnings forecast in third quarter 2024

Tesla


Tesla shares climbed 12% in extended trading after the company’s third-quarter earnings beat Wall Street estimates, following a long slump.

However, Tesla’s revenue for that period, up 8% year on year, marginally missed expectations. “Vehicle growth” will hit up to 20%-30% next year, said CEO Elon Musk, thanks to “lower cost vehicles” and the “advent of autonomy.” Apparently, this was presented as a ‘best guess’.

Profit margins reportedly received a boost from $739 million in automotive regulatory credit revenue during the quarter. Automakers must acquire a certain number of regulatory credits annually. Those unable to meet the requirement can buy credits from companies like Tesla, which has a surplus due to its exclusive production of electric vehicles.

Automotive revenue reportedly rose 2% to $20 billion, up from $19.63 billion in the same quarter the previous year, and has remained roughly stable since late 2022. Energy generation and storage revenue reportedly surged 52% to $2.38 billion, while services and other revenue, which includes income from non-warranty Tesla vehicle repairs, increased by 29% to $2.79 billion.

Tesla quarterly revenues by business section

Tesla quarterly revenues by business section

Tesla share price and close and ‘after hours’ trading 23rd October 2024 (09:15 BST)

Tesla share price and close and ‘after hours’ trading 23rd October 2024 (09:15 BST)

Wind power is being wasted adding £40 to household energy bills, according to think tank

Wind turbine and battery

Wasted wind power will add £40 to the average UK household’s electricity bill in 2023, according to a think tank.

That figure could increase to £150 in 2026, Carbon Tracker has estimated.

When it is very windy, the grid cannot handle the extra power generated. So, wind farms are paid to switch off and gas-powered stations are paid to fire up. The cost is passed on to consumers.

The government said major reforms will halve the time it takes to build energy networks to cope with extra wind power. Energy regulator Ofgem announced new rules in November 2023, which it said would speed up grid connections.

Bottleneck

Most of the UK’s offshore wind farms are in England. Dogger Bank, off the coast of Yorkshire is the largest in the world. Meanwhile, around half of onshore wind farms are in Scotland but most electricity is used in south-east England.

Carbon Tracker said the main problem in getting electricity to where it is needed is a bottleneck in transmission.

Wind curtailment

The practice of switching off wind farms and ramping up power stations is known as wind curtailment. This cost is passed on to consumers, it said. Carbon Tracker researches the impact of climate change on financial markets. It said since the start of 2023, wind curtailment payments cost £590m, adding £40 to the average consumer bill.

It warned the costs were set to increase adding £180 per year to bills by 2030. Wind farms are being built faster than the power cabling needed to carry the electricity.

Cable issue

‘The problem is, there are not enough cables. The logical solution would be to build more grid infrastructure,‘ said an analyst at Carbon Tracker. ‘It’s not even that expensive,’ he added, compared with mounting wind curtailment costs.

Industry group RenewableUK reportedly said that grid constraints, ‘reflect a chronic lack of investment in the grid.’

‘We need to move from a grid which is wasteful, to one that’s fit for purpose as fast as possible.’

However, historically it has taken between 10 and 15 years for new transmission cables to be approved.

Maybe more battery storage plants around the UK would help reduce the bottlenecks? As renewable power continues to expand, this would enable the extra power to be stored to use later.

This would be better than firing up antiquated fossil fuel power plants.

Desert location for energy and power generation

Electricity infrastructure

Will these projects alter the world weather pattern?

According to a study, installing large-scale wind and solar farms in the Sahara desert could increase rainfall and vegetation in the region. The researchers simulated the effects of covering 20% of the Sahara with solar panels and wind turbines and found that it would trigger a feedback loop of more monsoon rain and more plant growth.

This could have benefits for the local environment and the global climate, as well as providing a huge amount of clean energy for the world.

Could it also create a detrimental effect to the ecosystem too?

10.5 GW solar energy

The desert project would produce 10.5 GW of solar power and 3 GW of wind power. However, there are also challenges and uncertainties involved, such as the cost, feasibility, and environmental impacts of such a massive undertaking.

The Sahara is a desert on the African continent. With an area of 9,200,000 square kilometres, it is the largest hot desert in the world and the third-largest desert overall, smaller only than the deserts of Antarctica and the northern Arctic.

Daily global electricity energy demand

The global electricity energy demand is the amount of electricity that the world needs in a given day. It can be calculated by multiplying the average global electricity demand in GW by 24 hours. According to the International Energy Agency (IEA), the average global electricity demand in 2020 was about 3 TW or 3 000 GW. This means that the global electricity energy demand in 2020 was about 72 000 GWh or 72 TWh per day. However, this is an average value, and the actual demand may vary depending on the season, time of day, weather, and other factors.

The global electricity energy demand is expected to increase in the future, as population grows and living standards improve. The IEA projects that the average global electricity demand will reach 3.8 TW or 3 800 GW by 2030 and 5.2 TW or 5 200 GW by 2050 in the Announced Pledges Scenario, which reflects the full implementation of net-zero emissions targets by some countries and regions. This implies that the global electricity energy demand will reach 91 200 GWh or 91.2 TWh per day by 2030 and 124 800 GWh or 124.8 TWh per day by 2050.

Energy sources

The sources of electricity generation will also change in the future, as renewable technologies such as solar PV and wind become more dominant and coal use declines. The IEA reports that the main sources of electricity generation in 2020 were coal (34%), natural gas (23%), hydropower (16%), nuclear (10%), wind (8%), solar PV (4%), biofuels and waste (3%), and other renewables (2%).

The researchers simulated the effects of covering 20% of the Sahara with solar panels and wind turbines and found that it would trigger a feedback loop of more monsoon rain and more plant growth.

In the Announced Pledges Scenario, renewables in electricity generation rise from 28% in 2021 to about 50% by 2030 and 80% by 2050.

Powering the UK from energy created in Morocco

Powering the UK from energy generated in Morocco

Energy from Xlinks project

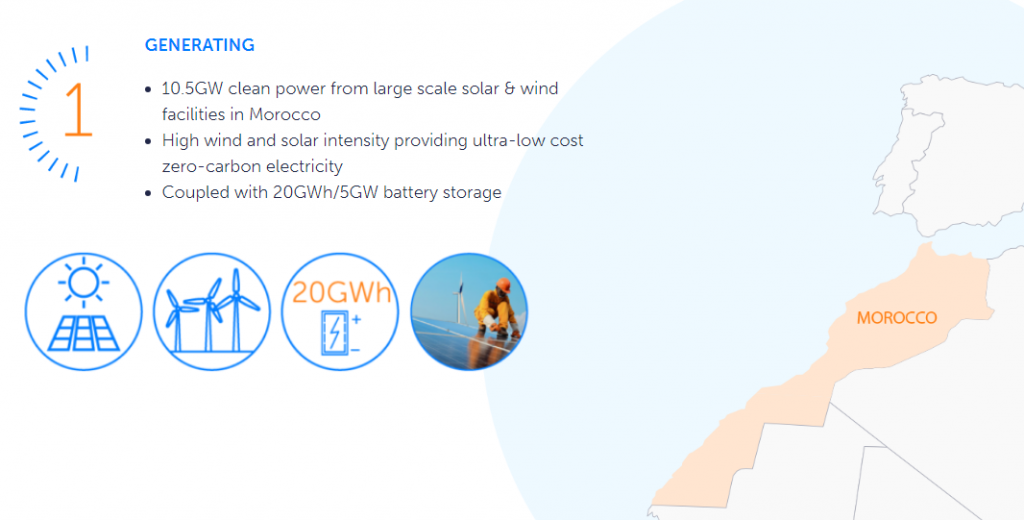
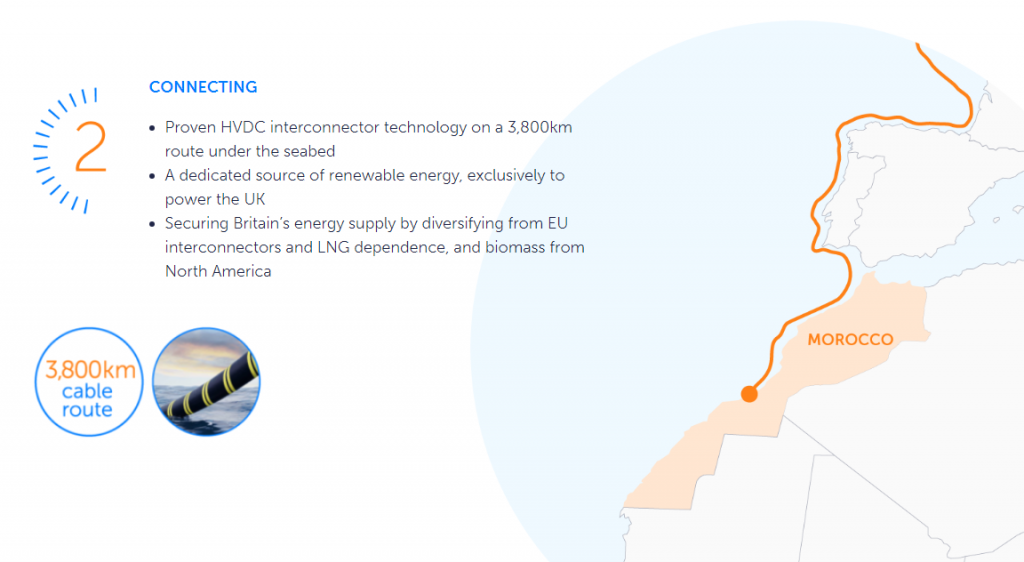
The Xlinks Morocco-UK Power Project is a proposal to create a large-scale renewable energy complex in Morocco and feed the electricity to the UK via a long underwater cable.

Key facts

12 million solar panels, 530 wind turbines over 62 square miles.

  • The project aims to produce 10.5 GW of clean power from solar and wind facilities in Morocco’s Guelmim Oued Noun region. This is equivalent to about 10% of the UK’s electricity demand.
  • The project also plans to build a 20 GWh/5 GW battery storage facility to ensure a stable and reliable supply of electricity.
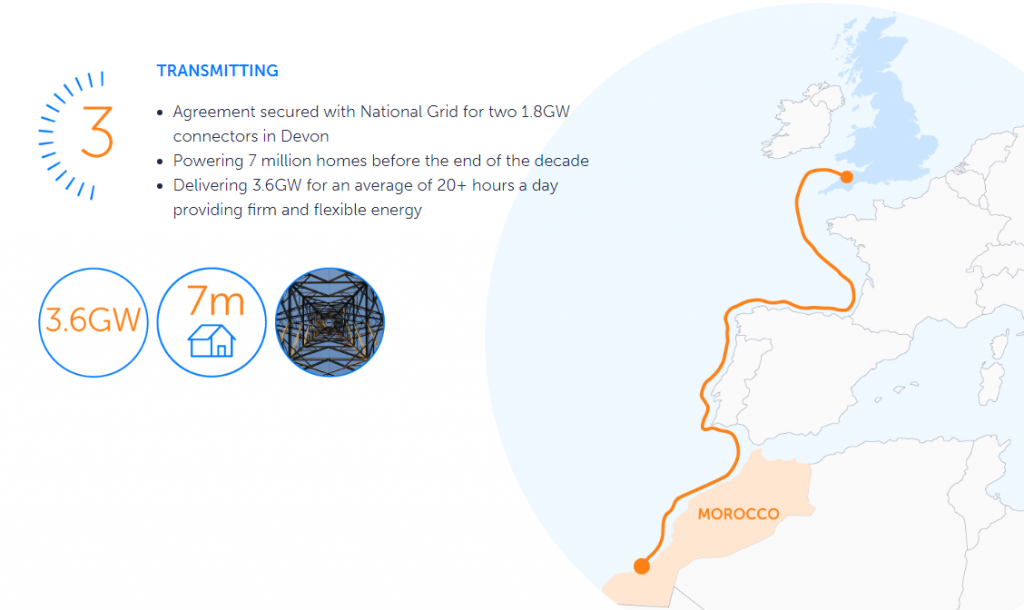
  • The project will use proven high-voltage direct current (HVDC) interconnector technology to transmit the electricity to the UK via a 3,800 km route under the seabed. The cable will connect to two locations in Devon and Wales, each with a capacity of 1.8 GW.
  • The project will create over 11,000 new green jobs in the UK and Morocco, and contribute to their renewable industrial ambitions. It will also diversify the UK’s energy sources and reduce its dependence on EU interconnectors, LNG imports, and biomass from North America.

This image has an empty alt attribute; its file name is image-1-1024x562.png

  • The project is seeking a 25-year contract with the UK government to guarantee a fixed electricity price and secure financing for the £20 billion investment. 
  • It hopes to start construction in 2024 and deliver power to the UK by 2028.

Entirely powered by sun and wind

The Xlinks Morocco-UK Power Project will be a new electricity generation facility entirely powered by solar and wind energy combined with a battery storage facility. Located in Morocco’s renewable energy rich region of Guelmim Oued Noun, it will be connected exclusively to Great Britain via 3,800km HVDC sub-sea cables.

Zero carbon power generation

When domestic renewable energy generation in the United Kingdom drops due to low winds and short periods of sun, the project will harvest the benefits of long hours of sun in Morocco alongside the consistency of its convection Trade Winds, to provide a firm but flexible source of zero-carbon electricity.

UK to issue new oil and gas licences for energy independence

Fossil fuels still needed for energy security

Green?

The UK government has announced a plan to issue over 100 new oil and gas licences in the North Sea, as part of its drive to make Britain more energy independent and reduce reliance on imports. The Prime Minister said that even when the UK reaches net zero by 2050, a quarter of its energy needs will still come from oil and gas.

Carbon Capture

The new licences will be subject to a climate compatibility test and will aim to unlock carbon capture and storage and hydrogen opportunities in the region. The government has also approved two new carbon capture projects in Scotland and the Humber, which are expected to be delivered by 2030.

Criticised

The move has been criticised by environmental groups, who argue that opening up new fossil fuel projects is incompatible with the UK’s climate goals and will undermine its leadership ahead of the COP26 summit in Glasgow. 

They also question the claim that domestic production is cleaner than imports, as the UK’s oil and gas sector is still responsible for significant emissions.

The government has said that it will support the transition of the North Sea industry to low-carbon technologies and protect more than 200,000 jobs in the sector. The UK government has also pledged to invest in renewable energy sources, such as offshore wind, to diversify the UK’s energy mix.